18 Matrix Product Unitaries
Matrix product unitaries describe translation-invariant unitary operators generated by local tensor networks [ 16 ] . The nil-matrix bounds of Theorem 18.1 and Theorem 18.2 establish the blocking lengths required for structural reduction.
Let a Lie algebra \(L\) act nilpotently on a finite-dimensional vector space \(V\) over a field \(K\). Write \(C_r(L,V)\) for the \(r\)th term of the lower central series of this action. Then
As long as \(C_r(L,V)\) is nonzero, nilpotency prevents two consecutive terms from being equal: equality would make every later term equal, in contradiction with eventual vanishing. Thus each nonzero step strictly lowers dimension, and at most \(\dim _K(V)\) such steps are possible.
Let \(V\) be a finite-dimensional vector space over a field \(K\), and let \(A\subseteq \operatorname {End}_K(V)\) be a not necessarily unital associative subalgebra. If every element of \(A\) is nilpotent, then every ordered product of \(\dim _K(V)\) elements of \(A\) is zero. The empty product in dimension zero is also zero because the identity endomorphism of the zero space is zero.
Regard \(A\) as a Lie algebra under the commutator bracket. Engel’s theorem makes \(V\) a nilpotent Lie module, so the dimension bound gives
For every nonnegative integer \(r\), every ordered family \(a_1,\ldots ,a_r\) in \(A\), and every vector \(v\) in \(V\), induction on \(r\) gives
Taking \(r=\dim _K(V)\) proves that the product annihilates every vector and is therefore zero.
Let \(A\) be a not necessarily unital associative subalgebra of \(n\times n\) matrices over a field. If every matrix in \(A\) is nilpotent, then every ordered product of \(n\) matrices from \(A\) vanishes.
Transport the matrix algebra to the endomorphisms of the coordinate space through the standard algebra equivalence. Nilpotency, membership, and the ordered product are preserved, so the finite-dimensional nil-matrix theorem applies; injectivity of the equivalence returns the zero matrix.
The bound \(n\) is sharp for strictly upper-triangular matrices, correcting the intermediate strict inequality in [ 16 ] . Applied once to an algebra of \(D^2\times D^2\) matrices, it gives the blocking length \(D^2\) of Theorem 18.3.24.
18.1 The matrix product unitary condition
Let \(\mathcal U=\{ U^{ij}\} _{i,j=0}^{d-1}\) be a matrix product operator tensor of bond dimension \(D\), and write \(U^{(N)}\) for the periodic operator obtained by closing a chain of \(N\) copies of \(\mathcal U\).
Let \(I\) and \(J\) be finite sets, let \(e\colon I\to J\) be a bijection, and let \(A\) be a unitary matrix indexed by \(I\). The matrix indexed by \(J\) whose \((j,k)\) entry is
is unitary.
Simultaneous reindexing preserves the identity and matrix multiplication, and it commutes with the conjugate transpose. Reindex the equation \(AA^\dagger =\mathbb {1}\).
The tensor \(\mathcal U\) generates matrix product unitaries if \(U^{(N)}\) is unitary for every integer \(N{\gt}1\). This is the matrix product unitary condition in [ 16 , Section III, equation (10) ] .
Let \(d=D=3\) with indices in \(\mathbb Z_3\) and \(M^{ij}=|{-(i+j)})(j|\). The operator on \(N\geq 1\) sites is the matrix of the map \(j\mapsto i\), \(i_n=-(j_{n-1}+j_n)\), which is \(\mathbb Z_3\)-linear, injective for odd \(N\), and not injective for even \(N\). Hence \(M^{(N)}\) is unitary for odd \(N\) and not unitary for even \(N\) (at \(N=2\) the inputs \(01\) and \(10\) have the same image \(22\)), so the tensor does not generate matrix product unitaries. Its ranks are \(r=9\) and \(\ell =3\).
Let \(d=2\), \(D=4\), bond indices \(\alpha =(\alpha _1,\alpha _2)\in \{ 0,1\} ^2\), and \(U^{ij}_{\alpha \beta }=\delta _{ij}\delta _{\alpha _2\beta _1}\delta _{\beta _2i}(-1)^{\alpha _1i}\). For \(N\geq 1\) the operator on \(N\) sites is diagonal with entries \(\prod _n(-1)^{i_ni_{n+2}}\) (indices modulo \(N\)), so the tensor generates matrix product unitaries, and for \(N\geq 3\) the product of controlled-\(Z\) gates between next-nearest neighbours. The tensor is not simple, its blocking of two sites is simple with boundary vectors \(\Omega \) and \(\Omega /4\), and the ranks are \(r=\ell =4\) for the tensor and for its blocking. The simplicity of the blocking follows from a general criterion: a tensor whose double-layer letters are \(\delta _{ij}|X_i)(Y_i|\) with \((Y_i|X_k)=(Y_i|b)(a|X_k)\) and \((a|X_i)(Y_i|b)=1\) is simple with boundary vectors \(a,b\).
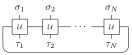
If \(\mathcal U\) generates matrix product unitaries and \(N{\gt}1\), then
Expand the unitary-group condition for \(U^{(N)}\).
If \(\mathcal U\) generates matrix product unitaries and \(N{\gt}1\), then
This is the unitarity equation displayed in [ 16 , Section III, equation (12) ] .
Use the equivalent left-multiplied characterization of a unitary matrix.
Let \(\mathcal U\) and \(\mathcal V\) be matrix product unitary tensors with the same physical dimension. Contracting the output index of \(\mathcal U\) with the input index of \(\mathcal V\) gives a matrix product unitary tensor whose periodic operator is \(U^{(N)}V^{(N)}\), in that order. This is the concatenation tensor \(\mathcal W\) in the proof of [ 16 , Theorem IV.6(ii) ] .
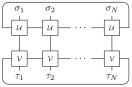 \(=\bigl(U^{(N)}V^{(N)}\bigr)_{\sigma ,\tau }\)
For every \(N{\gt}1\), both \(U^{(N)}\) and \(V^{(N)}\) are unitary. The defining contraction of the product tensor gives the periodic operator \(U^{(N)}V^{(N)}\), which is unitary because the unitary matrices form a group under multiplication.
Suppose that \(\mathcal U\) generates matrix product unitaries. For every positive integer \(L\), the tensor \(\mathcal U^{[L]}\) obtained by blocking \(L\) adjacent sites also generates matrix product unitaries. This is the blocking operation of [ 16 , Definition II.5 and equation (9) ] ; preservation of the MPU property under blocking is used in the proof of [ 16 , Proposition III.3 ] .
At system size \(N\), closing the blocked tensor gives \(U^{(NL)}\), up to the canonical bijection between \(N\) blocked configurations and \(NL\) unblocked configurations. If \(N{\gt}1\) and \(L{\gt}0\), then \(NL{\gt}1\), so \(U^{(NL)}\) is unitary. Simultaneous reindexing preserves unitarity.
18.2 Simple matrix product unitary tensors
For an MPO tensor \(\mathcal U\), let \(\mathcal W\) be the double-layer tensor obtained by placing the physical adjoint above \(\mathcal U\) and contracting the adjacent physical legs:
The bond space of \(\mathcal W\) is the product of the two original bond spaces. The physical adjoint exchanges and conjugates the physical indices without reversing the order of the virtual chain, exactly as in the barred upper layer of Figures II_Simple1.png and II_Simple2.png of [ 16 ] .
 \(=\)

For every chain length \(N\), closing the double layer gives
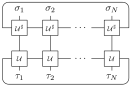 \(=\)
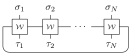
The operator family is multiplicative under the local product tensor, and the physical adjoint generates the conjugate transpose without reflecting the chain.
The physical adjoint is involutive. If \(\mathcal U\) generates matrix product unitaries, then so does \(\mathcal U^\sharp \), and for every chain length \(N\),
Applying the physical adjoint twice conjugates every entry twice and exchanges the physical indices twice. Closing a physical-adjoint tensor exchanges the two physical configurations and conjugates the resulting scalar. Hence its periodic operator is the conjugate transpose. The first MPU unitarity equation for \(U^{(N)}\) is therefore the second unitarity equation for \((U^\sharp )^{(N)}\).
Order the left doubled bond as \((\alpha ,\gamma )\) and the right doubled bond as \((\beta ,\delta )\). Then the double layer whose lower tensor is \(\mathcal U^\sharp \) has entries
Expand the double layer and then apply the physical adjoint to its upper factor. The two exchanges of physical indices leave the contracted index \(j\) in the second physical position of both factors. The product-index convention keeps \((\alpha ,\gamma )\) and \((\beta ,\delta )\) in the displayed order.
The tensor \(\mathcal U\) is simple if there are vectors \(a,b\) in the double-layer bond space such that, for all physical indices \(i,j,k,\ell \),
Thus (11) closes one double-layer letter to the physical identity, while (12) inserts the rank-one operator \(|b)(a|\) between adjacent letters. These are precisely the two diagrams in [ 16 , Definition III.2 ] .
 \(=\)

 \(=\)


If \(\mathcal U\) is simple and \(N{\gt}1\), then
\(=\) 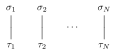
Apply (12) sequentially between neighboring letters. The inserted rank-one operators split the periodic contraction into the product of the one-letter contractions \((a|W^{\sigma _x\tau _x}|b)\). Identity (11) turns this product into \(\prod _x\delta _{\sigma _x,\tau _x}\), which is the matrix element of the physical identity.
Every simple tensor generates matrix product unitaries. This is [ 16 , Proposition III.3(i) ] .
For every \(N{\gt}1\), the closed-double-layer identity and the sequential contraction give
Hence \(U^{(N)}\) is unitary.
18.3 Double-layer blocking and mixed physical traces
For every blocking length \(L\), physical adjunction commutes with blocking, and consequently
The virtual order is unchanged on both sides.
Assume \(d{\gt}0\), and let \(E\) be the normalized transfer matrix of \(\mathcal U\). After blocking \(L\) sites, the normalized physical diagonal of the double layer is exactly \(E^L\). More precisely, if
is the standard product encoding, then its entries are
Thus the row and column reindexings have the same explicit orientation. If \(\mathcal U\) is an MPU and \(D{\gt}1\), then at the stabilization exponent \(J\) this diagonal is the same reindexing of the rank-one projector \(|\rho )(\Phi |\).
On one site, expanding the diagonal double-layer contraction gives the transfer matrix after the stated product reindexing. The factor \(d^{-1}\) is the square of the local factor \(d^{-1/2}\). Summing blocked diagonal letters over words and distributing the ordered product shows that normalized diagonals turn blocking into powers. Simultaneous reindexing preserves multiplication, giving the displayed formula. Transfer stabilization gives the final rank-one specialization.
Let \(\mathcal W\) be an MPO tensor of physical dimension \(d\), and let
be its normalized physical diagonal. Here and in the two diagonal-tail identities below, scalar inverses are the totalized complex-field inverses, so \(0^{-1}=0\). For every \(K\geq 0\),
At \(K=0\), the word product is the identity matrix. This is the algebraic diagonal-tail expansion used in the source-factor networks of [ 16 , Theorem III.8, Section III.B, equations (31)–(32) ] .
Expand the \(K\)th power of the finite sum defining \(R\). Distributivity indexes the resulting terms by physical words \(\tau \), and each term is the ordered diagonal word displayed above.
If \(d{\gt}0\), the identity matrix extends to a basis of \(M_{d}(\mathbb {C})\) whose other elements are traceless.
The trace functional is nonzero on the identity. Extend the identity by a basis of the kernel of the trace.
Assume \(d{\gt}0\). For every double-layer tensor \(\mathcal W\), there is a basis \(\{ \sigma _0,\sigma _\alpha \} \) of the physical matrix algebra and virtual matrices \(E,S_\alpha \) such that \(\sigma _0=\mathbb {1}\) and, for every nonzero index \(\alpha \), \(\operatorname{tr}(\sigma _\alpha )=0\), while
Here \(E\) is the normalized physical diagonal. Equivalently, contraction against a physical matrix \(X\) separates as
where the second physical argument is traceless. This is equation WIsom in [ 16 , Proposition III.3(ii) ] .
The trace functional is nonzero on the identity. Extend the identity to a basis adapted to the kernel of the trace; all remaining basis vectors are therefore traceless. The bilinear pairing \((X,Y)\mapsto \operatorname{tr}(XY)\) is nondegenerate. Its dual basis gives the virtual coefficients by physical contraction. The dual vector paired with the identity is \(d^{-1}\mathbb {1}\), so its virtual coefficient is precisely \(E\). Expanding matrix units in the dual basis yields the decomposition. Subtracting the trace component gives the equivalent residual formula.
Suppose a length-\(N\) closed tensor equals the physical identity. For arbitrary physical matrices \(X_0,\ldots ,X_{N-1}\),
In particular this applies to the double layer of an MPU whenever \(N{\gt}1\).
Expand each contraction and distribute the ordered product. The closed tensor coefficient is a Kronecker delta between the two physical words, so only equal words survive. The remaining independent diagonal sums factor into the product of the physical traces.
Let \(\mathcal U\) be an MPU with physical dimension \(d{\gt}0\). Every closed product of positive length that contains at least one residual coefficient has zero trace. In particular, this includes a single residual coefficient. This corresponds to the mixed-trace property in [ 16 , Proposition III.3(ii) ] .
At lengths greater than one, represent identity factors by \(d^{-1}\mathbb {1}\) and residual factors by traceless physical arguments. The multilinear contraction identity then vanishes. For a single residual coefficient \(A\), repeat the same coefficient at every length \(q{\gt}1\) to obtain \(\operatorname{tr}(A^q)=0\). Thus the one-letter case is recovered after the longer words: the shifted zero-trace-power theorem makes \(A\) nilpotent, and therefore \(\operatorname{tr}(A)=0\).
Let \(\mathcal U\) be an MPU with physical dimension \(d{\gt}0\), and let \(N{\gt}1\). Every closed product of \(N\) identity and residual coefficients that contains at least one residual coefficient has zero trace. If the normalized diagonal is rank one, then every nonempty residual word \(P\) satisfies
The same conclusion holds after blocking \(J{\gt}0\) sites whenever the \(J\)th normalized transfer power is \(|\rho )(\Phi |\), with both virtual indices reindexed by \(q^{-1}:\{ 0,\ldots ,D^2{-}1\} \longrightarrow \{ 0,\ldots ,D{-}1\} \times \{ 0,\ldots ,D{-}1\} \).
Represent identity factors by \(d^{-1}\mathbb {1}\) and residual factors by their traceless physical arguments. Since \(N{\gt}1\), the multilinear contraction identity applies, and one trace factor vanishes. For a nonempty residual word, adjoin \(E\) as one extra factor; its closed trace has length at least two and therefore vanishes. Cyclicity of trace and
give \(EPE=0\). The blocked statement follows from the transfer-power formula with the same product-index reindexing in both matrix indices.
Let \(\mathcal U\) have bond dimension \(D\). Contract the double layer against arbitrary physical matrices, subtract the normalized diagonal coefficient, and let \(\mathcal S\) be the resulting set of residual matrices in \(M_{D^2}(\mathbb C)\). The residual algebra \(\mathfrak S\) is the not necessarily unital algebra generated by \(\mathcal S\). This is the algebra generated by the matrices \(S'_\alpha \) in [ 16 , Proposition III.3(ii) ] .
If \(\mathcal U\) is an MPU with positive physical dimension, then every nonempty product of residual generators has zero trace. Consequently, for every \(A\in \mathfrak S\) and every integer \(N{\gt}1\),
and every element of \(\mathfrak S\) is nilpotent.
A nonempty product in the multiplicative semigroup generated by \(\mathcal S\) is a nonempty residual word, so its trace vanishes by the positive-length mixed residual identity. The generated nonunital algebra is the linear span of this semigroup. Linearity of the trace therefore gives \(\operatorname{tr}(A)=0\) for every \(A\in \mathfrak S\). Since every positive power of \(A\) remains in \(\mathfrak S\), the same argument gives \(\operatorname{tr}(A^N)=0\) for \(N{\gt}1\). The shifted zero-trace-power theorem now implies that \(A\) is nilpotent.
Let \(\mathcal U\) be an MPU of bond dimension \(D\) and positive physical dimension. Every ordered product of exactly \(D^2\) elements of \(\mathfrak S\) vanishes. In particular, for arbitrary residual generators,
This is equation Sprime=0 in [ 16 , Proposition III.3(ii) ] , with the corrected exact length \(D^2\) in place of the unsupported strict intermediate bound.
The algebra \(\mathfrak S\) acts on a space of dimension \(D^2\), and every element is nilpotent. The finite-dimensional nil-matrix theorem therefore annihilates every ordered product of \(D^2\) elements. Each residual generator belongs to \(\mathfrak S\), giving the stated specialization.
Let \(E\) be the normalized diagonal after the first blocking and let \(\mathfrak S\) be its residual nonunital algebra. Define
This is the basis-independent sum of the three forms in equation sprimeforms of [ 16 , Proposition III.3(ii) ] .
Suppose \(E^2=E\), \(EAE=0\) for every \(A\in \mathfrak S\), and every ordered product of \(N{\gt}0\) elements of \(\mathfrak S\) vanishes. For scalars \(c_k\) and elements \(S_k\in \mathfrak S\),
Products are taken in increasing site order and need not commute.
Expand the product as a sum over binary choices of \(E\) or \(S_k\), retaining the original order. The all-\(E\) choice is the subtracted term because \(E^q=E\) for \(q{\gt}0\). The all-residual choice vanishes by the length-\(N\) hypothesis. In every remaining word, contiguous copies of \(E\) collapse. If two resulting copies of \(E\) are separated by a nonempty residual word, the factor \(EAE\) makes the word zero. Thus each surviving word has one contiguous projector block and belongs to one of the three summands of \(\mathcal T\).
Let the first-block tensor be an MPU of bond dimension \(D{\gt}0\). Assume its normalized double-layer diagonal \(E\) is a rank-one idempotent. After a second blocking of exactly \(D^2\) sites, every residual coefficient belongs to \(\mathcal T\).
The conclusion is membership in the sum of the three subspaces. It does not assign one exclusive type to a coefficient in an arbitrary physical basis.
First extend \(EPE=0\) from nonempty residual words \(P\) to every element of \(\mathfrak S\) by writing the generated algebra as the linear span of the multiplicative semigroup of residual generators. For a blocked matrix unit, each local double-layer entry is
The ordered expansion theorem applies with \(N=D^2\). Its all-\(E\) coefficient is the blocked Kronecker delta and is exactly removed by the residual slice. Hence every blocked matrix-unit residual lies in \(\mathcal T\). Expanding an arbitrary physical matrix in matrix units and using linearity proves the result.
Suppose \(E^2=E\) and \(EAE=0\) for every \(A\in \mathfrak S\). For all \(X,Y\in \mathcal T\),
It is enough by bilinearity and linearity of trace to consider the generators \(EA\), \(AE\), and \(AEB\) of the three summands. Representative products reduce as
The remaining generator pairs follow by the same use of associativity, \(E^2=E\), and \(EAE=0\) for \(A\in \mathfrak S\).
Let \(\mathcal V\) be an MPU of positive physical and bond dimensions whose normalized double-layer diagonal is
Then blocking \(\mathcal V\) by exactly \(D^2\) sites produces a simple tensor with witnesses \(a=\Phi \) and \(b=\rho \).
The pairing normalization makes \(E\) idempotent. Write every blocked double-layer coefficient as \(\delta _{ij}E+R_{ij}\), where \(R_{ij}\in \mathcal T\). The trace identity for \(R_{ij}E\) gives the diagonal contraction, and \(R_{ij}R_{k\ell }=R_{ij}ER_{k\ell }\), together with \(E^2=E\), gives the rank-one insertion identity after expanding both coefficients.
For a bijection \(e\) between two physical index sets, the reindexed tensor and its action on length-\(N\) configurations are
For ket and bra words \(i,j\), physical reindexing gives
Induct simultaneously along the two words. The empty pair gives the identity matrix, mismatched lengths give zero, and the nonempty case applies the defining equality to the first letters and the induction hypothesis to the tails.
At every length \(N\), the sitewise configuration bijection identifies
Apply the word identity to every pair of configurations and take the virtual trace. This is simultaneous row and column reindexing by \(e_*\).
For every physical-index bijection \(e\), taking the double layer commutes with physical reindexing:
This follows entrywise from the definitions of physical reindexing and the double layer.
Let \(e\) be the canonical bijection which groups a word of length \(mn\) into \(n\) consecutive words of length \(m\). Iterating blocking at lengths \(m\) and \(n\), then applying this physical reindexing, agrees with direct blocking at length \(mn\):
Expand the two blocked words. The canonical regrouping concatenates their \(n\) words of length \(m\) into the direct word of length \(mn\).
Let \(\mathcal U\) have bond dimension \(D\). The double-layer algebra \(\mathcal A\subseteq M_{D^2}(\mathbb C)\) is the not necessarily unital algebra generated by the double-layer letters \(W^{ij}\). It contains every \(W^{ij}\) and, as a linear combination of them, the normalized diagonal \(E\).
Let \(\mathcal U\) be an MPU of positive physical and bond dimensions, and let \(\mathcal A\) be its double-layer algebra. The normalized diagonal \(E\) has trace one. Every nonempty word satisfies
Consequently \(\operatorname{tr}(ab)=\operatorname{tr}(a)\operatorname{tr}(b)\) for all \(a,b\in \mathcal A\).
Let \(E^J=|\rho )(\Phi |=p\) with \(J{\gt}0\), \((\Phi |\rho )=1\) and \(E|\rho )=|\rho )\). Then \(Ep=pE=p^2=p\), so \((E-p)^N=E^N-p\) for \(N{\gt}0\) and \(E-p\) is nilpotent. Hence \(\operatorname{tr}E=\operatorname{tr}p=1\). Writing \(W^{ij}=\delta _{ij}E+R_{ij}\) with a traceless residual \(R_{ij}\) gives the one-letter case. For \(N{\gt}1\), the trace of the word is a matrix entry of \((\mathcal U^{(N)})^\dagger \mathcal U^{(N)}=\mathbb {1}\). The algebra \(\mathcal A\) is the linear span of nonempty words, and the trace of a concatenated word is the product of the traces of its two parts; bilinearity gives multiplicativity on \(\mathcal A\).
Every MPU of positive physical and bond dimensions becomes simple after blocking exactly \(D^2\) sites, and hence after blocking any \(k\geq D^2\) sites. The witnesses at length \(D^2\) are the normalized fixed vectors \(\Phi \) and \(\rho \) of the transfer matrix. Simplicity is preserved under every further iterated blocking by a positive factor and under a bijective relabeling of the physical basis.
The length \(D^2\) is the one stated in [ 246 , Theorem 2 ] ; [ 16 , Proposition III.3(ii) ] gives a length below \(D^4\).
Let \(\mathcal A\) be the double-layer algebra, \(p=E^J=|\rho )(\Phi |\) the stabilized transfer power, and
Since the trace is a character on \(\mathcal A\), the set \(\mathcal N\) is a subalgebra, and \(\operatorname{tr}(n^m)=\operatorname{tr}(n)^m=0\) for every \(n\in \mathcal N\) and \(m{\gt}0\). Every element of \(\mathcal N\) is therefore nilpotent, and by the nil-matrix theorem every product of \(D^2\) elements of \(\mathcal N\) vanishes. Moreover \(p\in \mathcal A\) and \(\operatorname{tr}p=1\), so
The ordered expansion theorem, applied with \(p\) in place of the projector and \(\mathcal N\) in place of the residual algebra, writes every blocked letter of length \(D^2\) as \(\delta _{IJ}p+t_{IJ}\) with \(t_{IJ}\) in the three-form subspace of \(p\) and \(\mathcal N\). The three-form contraction identity \(t\, t'=t\, p\, t'\) and \(p^2=p\) give
MPU unitarity then gives the one-letter contraction with the same witnesses, and simplicity persists at every later blocking.
Let \(\mathcal U\) be an MPU of positive physical and bond dimensions. Suppose that \(\rho \) has trace one and that, for some positive integer \(J\), the normalized transfer matrix satisfies
Put \(K=JD^2\). After the standard product reindexing of the physical coordinates, the direct length-\(K\) block satisfies the contractions (11) and (12) with the specific witnesses \(\rho \) and \(\mathbb {1}\) from this transfer-power identity.
First block \(J\) sites. The normalized diagonal of this block is the reindexed rank-one matrix \(|\rho )(\mathbb {1}|\), and the trace-one condition is exactly \((\mathbb {1}|\rho )=1\). The exact second-block contraction theorem then supplies both identities after a further \(D^2\) sites. The canonical equivalence between iterated blocking and direct length-\(JD^2\) blocking transports each double-layer coefficient without changing either virtual witness.
Let \(\mathcal U\) be an MPO tensor with \(d,D{\gt}0\), let \(E\) be the transfer matrix of its normalized flattening, and suppose that for some \(J\geq 0\) and some trace-one \(\rho \),
Then the normalized diagonal of the double layer of the direct length-\(JD^2\) block is the same rank-one matrix, after the standard product reindexing of the doubled bond.
Trace normalization gives \((\mathbb {1}|\rho )=1\), so \(|\rho )(\mathbb {1}|\) is idempotent and every positive power of it equals itself. The blocked normalized diagonal is the corresponding power of \(E\), and \(E^{JD^2}\) is the \(D^2\)-th power of \(E^J\).
Let \(d{\gt}0\), let \(\mathcal U\) be an MPU, and let \(K\geq 0\). For \(p,q\in \{ 0,\ldots ,d{-}1\} \times \{ 0,\ldots ,d{-}1\} \), separate the first two input sites from a common input tail \(\tau \in \{ 0,\ldots ,K{-}1\} \to \{ 0,\ldots ,d{-}1\} \). Then
The global contraction is the input-first unitarity \((U^{(K+2)})^\dagger U^{(K+2)}=\mathbb {1}\). This is the input-oriented tail contraction supporting the network calculation in [ 16 , Theorem III.8, Section III.B, equations (31)–(32) ] .
Apply input-first unitarity for each fixed tail. The inner output sum is \(\delta _{p,q}\). Summing over the \(d^K\) tails and multiplying by \(d^{-K}\) leaves the same Kronecker delta.
Let \(\mathcal U\) generate an MPU. If specified vectors \(a,b\) satisfy the two-letter insertion identity
then the same vectors satisfy
If the direct length-\(k\) block is simple for some \(k{\gt}0\), then its direct length-\(k'\) block is simple for every \(k'\geq k\), without any divisibility condition on \(k'\) by \(k\) [ 16 , Proposition III.3 ] .
First suppose vectors \(a,b\) satisfy the rank-one insertion identity
Set \(x_{ij}=(a|W^{ij}|b)\). Applying this identity around the constant two-site and three-site words, and then using MPU unitarity, gives
Hence \(x_{ii}=1\), while \(x_{ij}=0\) for \(i\ne j\), so the same vectors obey the one-letter contraction \((a|W^{ij}|b)=\delta _{ij}\).
For the successor step, take four words \(I,J,K,L\) of length \(k+1\) and write \(W^{I,J}=W^{i_0j_0}\cdots W^{i_kj_k}\), with the analogous notation for \(W^{K,L}\). Apply the length-\(k\) rank-one insertion identity to the suffixes \(I_+=(i_1,\ldots ,i_k)\), \(J_+=(j_1,\ldots ,j_k)\) and the prefixes \(K_-=(k_0,\ldots ,k_{k-1})\), \(L_-=(\ell _0,\ldots ,\ell _{k-1})\). Then
Thus the length-\((k+1)\) block has the same insertion witnesses, and the two- and three-site argument gives their one-letter contraction. Induction on \(k'-k\) proves the claim.
Let \(\mathcal U_1,\mathcal U_2\) be MPU tensors with positive physical and bond dimensions, which may differ between the tensors. There is a length \(k{\gt}0\) for which both direct length-\(k\) blockings are simple. The same conclusion holds for three such tensors \(\mathcal U_1,\mathcal U_2, \mathcal U_3\), with one common length \(k\). This is a finite-family consequence of [ 16 , Proposition III.3 ] , not an additional hypothesis on the tensors.
A tensor of bond dimension \(D\) is simple after blocking any \(k\geq D^2\) sites. The sum of the squares of the bond dimensions is positive and bounds every square from above, so it is a common simple blocking length for two or for three tensors.
Let \(d,D{\gt}0\). Every bond-\(D\) MPU tensor becomes simple after blocking exactly \(D^4\) sites. For each fixed \(L\), the map
is continuous. Consequently, if \(x\mapsto \mathcal W(x)\) is a continuous family of bond-\(D\) MPU tensors, then \(x\mapsto \mathcal W(x)_{D^4}\) is a continuous family of simple tensors. This provides the common-blocking step for Proposition 18.9.107.
Every tensor is simple after blocking any \(k\geq D^2\) sites, in particular after blocking \(D^4\geq D^2\) sites. For fixed blocked ket and bra words, every matrix entry of the blocked tensor is a finite sum of products of entries of the original tensor. These entries are continuous, and the finite product and sum operations preserve continuity. Applying this fixed blocking map to the original path proves the path statement.
Let \(\mathcal U\) be simple with positive physical dimension, let \(W\) be its double layer, and let \(E\) be the normalized diagonal of \(W\). Suppose that for some \(J{\gt}0\),
Then the simple insertion identity holds with these same supplied witnesses:
Choose the witnesses \(a,b\) from simplicity and put \(R=|b)(a|\). Expanding the normalized diagonal as the average of the diagonal letters, the two defining simple contractions give
Indeed, insert \(R\) on both sides of each diagonal letter; its middle sandwich is \(R W^{qq}R=R\) by the first contraction, and the normalized sum contains \(d\) equal terms. The same identity makes \(W^{ij}E^N=W^{ij}E\) for every \(N{\gt}0\). Hence
Substituting the supplied equality \(E^J=|\rho )(\Phi |\) proves the claim. No uniqueness of rank-one factorizations is used.
Let \(R\) be the normalized physical diagonal of the double layer of an MPO tensor. Suppose
Then the two boundaries of the stabilized diagonal tail are fixed:
This is the fixed-pair normalization from the canonical-form-II fixed-point equations in [ 16 , equations (6a)–(6b) ] and underlies the tail contractions in [ 16 , Theorem III.8, Section III.B, equations (31)–(32) ] .
Substitute \(R^J=\lvert \rho )(\Phi \rvert \) in each expression and use \((\Phi \rvert \rho )=1\).
Let \(W\) be the double layer of an MPO tensor, and let \(R\) be its normalized physical diagonal. If
then, for all physical indices \(i,j,k,\ell \),
This is the exact diagonal-word tail between the two retained letters in [ 16 , Theorem III.8, Section III.B, equations (31)–(32) ] .
Replace the rank-one insertion by \(R^J\), apply the diagonal-word expansion, and distribute the two retained letters across the normalized finite sum.
In the setting of Theorem 18.3.33, suppose in addition that the same fixed pair satisfies the supplied two-letter contraction
for all physical indices. Then
Thus the supplied insertion and its stabilized transfer power occur in one aligned network, as required in the calculation of [ 16 , Theorem III.8, Section III.B, equations (31)–(32) ] .
Apply the supplied two-letter contraction and then replace its rank-one insertion by the normalized diagonal-word tail.
For every MPU of positive physical and bond dimensions there are normalized left and right fixed vectors \(\Phi \) and \(\rho \) of the transfer matrix such that the unblocked double layer satisfies
The unblocked tensor need not satisfy the rank-one insertion identity.
Let \(E^J=|\rho )(\Phi |\) be a stabilized transfer power. Decompose \(W^{ij}=\delta _{ij}E+R_{ij}\). Fixedness and normalization give
The mixed residual trace identity applied to one residual factor followed by \(J\) diagonal factors gives
Since \(E^J=|\rho )(\Phi |\), these two trace identities are exactly the displayed contraction.
18.4 Trace-power lemma
In the transfer-matrix spectrum analysis of [ 16 , Proposition 1 ] , a matrix whose positive powers all have trace \(1\) has characteristic polynomial \(X^{n-1}(X-1)\). Assuming this trace condition only for powers with exponent strictly greater than one determines the nonzero spectrum as a set.
For an index \(i_0\) in a finite set \(I\) of cardinality \(n\), let \(M_{i_0}\) be the \(n\times n\) diagonal matrix with a \(1\) at position \(i_0\) and zeros elsewhere.
The matrix \(M_{i_0}\) from definition 18.4.1 satisfies
\(M_{i_0}^k = M_{i_0}\) for every \(k\ge 1\),
\(\operatorname{tr}(M_{i_0}^k) = 1\) for every \(k\ge 1\),
\(\chi _{M_{i_0}}(X) = X^{\, n-1}(X-1)\).
The first two items follow from \(1^k=1\) and \(0^k=0\) for \(k\ge 1\). The characteristic polynomial is computed from \(\chi _{\operatorname{diag}(d)}(X) = \prod _i (X - d_i)\).
Let \(A\) be an \(n\times n\) complex matrix with \(n\ge 1\). If \(\operatorname{tr}(A^k)=1\) for every \(k\) with \(1\le k\le n\), then
Choose any index \(i_0\) (the hypothesis \(n\ge 1\) makes this possible) and let \(B\) be the rank-one diagonal idempotent from Lemma 18.4.2. For \(1\le k\le n\) we have \(\operatorname{tr}(A^k)=1=\operatorname{tr}(B^k)\). The finite-range half of the Newton–Girard the corresponding theorem in the companion quantum-channel volume [ 216 , “Newton–Girard trace recursion” ] then yields \(\chi _A = \chi _B = X^{\, n-1}(X-1)\).
Let \(A\) be an \(n\times n\) complex matrix. If \(\operatorname{tr}(A^k)=1\) for every \(k\ge 1\), then
(The hypothesis already forces \(n\ge 1\) because the trace of a \(0\times 0\) matrix is \(0\), contradicting \(\operatorname{tr}(A)=1\).)
If \(n=0\) the hypothesis \(\operatorname{tr}(A)=1\) contradicts the fact that the trace of an empty matrix is \(0\); the conclusion follows vacuously. When \(n\ge 1\), the hypothesis on all positive powers implies the finite-range hypothesis of Theorem 18.4.3.
Let \(A\) be an \(n\times n\) complex matrix such that \(\operatorname{tr}(A^k)=1\) for every \(k{\gt}1\), and let \(m{\gt}1\). Then \(\operatorname{tr}((A^m)^r)=1\) for every \(r\ge 1\).
For \(r\ge 1\), one has \((A^m)^r=A^{mr}\) and \(mr{\gt}1\), so the hypothesis at exponent \(mr\) gives the result.
Let \(A\) be an \(n\times n\) complex matrix. If \(\operatorname{tr}(A^k)=1\) for every integer \(k{\gt}1\), then
Thus \(1\in \sigma (A)\) and every nonzero spectral value equals \(1\) [ 16 , Proposition III.1 ] .
For every positive integer \(r\), the shifted moments give
Hence
If \(\mu \in \sigma (A)\) is nonzero, spectral mapping places \(\mu ^2\) in \(\sigma (A^2)\) and \(\mu ^3\) in \(\sigma (A^3)\), so
Conversely, spectral mapping from \(1\in \sigma (A^2)\) supplies a nonzero spectral value of \(A\), which must be \(1\).
For a complex square matrix \(A\), write \(G_1(A)\) for its maximal generalized eigenspace at the eigenvalue \(1\). Then
The commuting factorization
gives, for every nonnegative integer \(k\),
Therefore every vector annihilated by a power of \(A-\mathbb {1}\) is annihilated by the corresponding power of \(A^2-\mathbb {1}\).
For every complex square matrix \(A\),
With \(G_1\) as above, algebraic multiplicity equals the dimension of the maximal generalized eigenspace. Hence
Let \(A\) be an \(n\times n\) complex matrix. If \(\operatorname{tr}(A^k)=1\) for every integer \(k{\gt}1\), then
Thus \(1\) is the sole nonzero eigenvalue and has algebraic multiplicity one. This is the exact shifted-moment conclusion of [ 16 , Proposition III.1 ] .
Applying the all-positive trace-power theorem to \(A^2\) gives
The multiplicity inequality therefore bounds \(\operatorname {mult}_{1}(\chi _A)\) by one. The set-spectrum theorem shows that \(1\) occurs, so this multiplicity is positive and hence equals one. The same set-spectrum theorem excludes every other nonzero root. Splitting the monic characteristic polynomial now yields
Let \(V\) be a finite-dimensional complex vector space and let \(S\) be a semisimple endomorphism of \(V\). Suppose that \(c\in \mathbb C\) is nonzero and
for every integer \(k{\gt}1\). Then
If \(N\) is nilpotent and commutes with \(S\), then, for every positive integer \(k\),
There is an integer \(J{\gt}0\) such that, for every \(k\geq J\),
This is the generic Jordan–Chevalley step in [ 221 , Proposition 20, lines 3839–3866 ] .
Choose an arbitrary basis of \(V\) and represent \(cS\) by a matrix \(A\). The shifted trace-power theorem gives
Since \(cS\) is semisimple, its generalized zero-eigenspace is its ordinary zero-eigenspace, namely its kernel. The dimension of the generalized zero-eigenspace is the root multiplicity of zero in the characteristic polynomial, so
Rank–nullity and \(c\ne 0\) therefore give \(\dim \operatorname {range}(S)=1\).
For \(k{\gt}0\), commutation gives the binomial expansion
If \(m{\gt}0\), write \(N^m=N N^{m-1}\). The first factor commutes with the remaining factors, so nilpotence of \(N\) makes the entire summand nilpotent and its trace vanishes. Only the term \(m=0\) remains, giving \(\operatorname{tr}((N+S)^k)=\operatorname{tr}(S^k)\). This is the trace reduction used in [ 221 , Proposition 20, line 3865 ] .
Commutation makes \(\operatorname {range}(S)\) invariant under \(N\). The restriction of \(N\) to this one-dimensional space is both nilpotent and a scalar endomorphism, hence zero. Therefore \(NS=0\), and commutation also gives \(SN=0\). For every positive \(k\), induction using these two identities yields
Taking \(J\) at least the nilpotency index of \(N\) removes the first summand.
Let \(A\) be an \(n\times n\) complex matrix. If \(\operatorname{tr}(A^k)=0\) for every integer \(k\geq 1\), then
The zero matrix has the same positive trace powers as \(A\) and characteristic polynomial \(X^n\). Newton–Girard therefore identifies the two characteristic polynomials. This is the characteristic-polynomial consequence of the all-positive trace condition obtained in [ 16 , proof of Proposition III.3 ] .
Let \(A\) be an \(n\times n\) complex matrix such that \(\operatorname{tr}(A^k)=0\) for every \(k{\gt}1\), and let \(m{\gt}1\). Then \(\operatorname{tr}((A^m)^r)=0\) for every \(r\geq 1\). This auxiliary result supports the generalization below to a weaker hypothesis; the source itself supplies vanishing for every positive exponent.
For \(r\geq 1\), one has \((A^m)^r=A^{mr}\) and \(mr{\gt}1\), so the hypothesis at exponent \(mr\) gives the result.
Let \(A\) be an \(n\times n\) complex matrix. If \(\operatorname{tr}(A^N)=0\) for every integer \(N{\gt}1\), then \(A\) is nilpotent and
The source obtains the all-positive trace hypothesis in [ 16 , proof of Proposition III.3 ] ; its specialization is the elementwise nilpotence assertion used before the nil-matrix theorem. The result above is a stronger generalization because it assumes vanishing only for \(N{\gt}1\). It is useful independently and requires no positivity, normality, or diagonalizability.
Every positive power of \(A^2\) has vanishing trace. Hence
If \(\mu \) is a spectral value of \(A\), spectral mapping shows that \(\mu ^2\) is a root of this characteristic polynomial. Therefore \(\mu ^2=0\), and hence \(\mu =0\). Thus every root of the split monic polynomial \(\chi _A\) is zero, so \(\chi _A(X)=X^n\). Cayley–Hamilton now proves that \(A\) is nilpotent.
The standard-form construction uses the compact singular-value decomposition in which the intermediate dimension is the rank rather than the smaller ambient dimension.
Let \(M\in M_{m,n}(\mathbb {C})\) be a complex matrix of rank \(r\). There are matrices \(V\in M_{r,m}(\mathbb {C})\) and \(U\in M_{r,n}(\mathbb {C})\) and strictly positive real numbers \(s_0,\ldots ,s_{r-1}\) such that, for \(D=\operatorname{diag}(s_0,\ldots ,s_{r-1})\),
Thus no zero singular values occur in the intermediate space. This is the compact decomposition used in the standard-form construction of [ 16 , Section III ] .
Apply the spectral theorem to \(MM^\dagger \). Its nonzero eigenvalues are positive, and their number is \(\operatorname {rank}(MM^\dagger )=\operatorname {rank}(M)=r\). For an orthonormal eigenvector \(e_j\) with eigenvalue \(\lambda _j{\gt}0\), put \(w_j=M^\dagger e_j\). Then \(\langle w_j,w_k\rangle =\lambda _j\delta _{jk}\). Hence the vectors \(\lambda _j^{-1/2}w_j\) are orthonormal. Expanding each column of \(M\) in the eigenbasis and discarding the zero-eigenvalue terms gives
which has the form in (99).
Singular-value decompositions of a matrix product unitary tensor in Section III of [ 16 ] rely on two cut matrices. Write \(\mathcal U^i_{j,\alpha ,\beta }\) for the entries of the tensor, where \(i,j\) are physical indices and \(\alpha ,\beta \) are auxiliary indices.
The matrix \(M_1\) is obtained by combining the upper physical index with the right auxiliary index, and the left auxiliary index with the lower physical index. Thus
Transporting the row and column indices along the standard product enumerations gives a matrix \(\widetilde M_1\) indexed by \(\{ 0,\ldots ,dD-1\} \times \{ 0,\ldots ,Dd-1\} \). Its entries are obtained by applying \(M_1\) to the inverse images of the enumerated indices, and
The matrix \(M_2\) is obtained by combining the left auxiliary index with the upper physical index, and the lower physical index with the right auxiliary index. Thus
Transporting the row and column indices along the standard product enumerations gives a matrix \(\widetilde M_2\) indexed by \(\{ 0,\ldots ,Dd-1\} \times \{ 0,\ldots ,dD-1\} \). Its entries are obtained by applying \(M_2\) to the inverse images of the enumerated indices, and
The right rank is
The left rank is
Physical adjunction exchanges the two source cuts and takes their adjoints:
Physical adjunction exchanges the upper and lower physical indices and complex conjugates every entry. Under the source-cut regroupings, it also exchanges rows and columns. Hence the first cut becomes the conjugate transpose of the second, and conversely.
On the flattened physical alphabet, define the involution
This acts on physical coordinates and is distinct from the doubled-bond exchange used in reflected transfer calculations.
The normalized flattening of the physical adjoint satisfies
For every pair of physical indices \((i,j)\),
where the intermediate steps follow by definition of normalized flattening, physical adjunction, and the reality of \(d^{-1/2}\).
Given canonical-form-II data for \(\widetilde{\mathcal U}\), define the transformed tuple by
These data reconstruct \(\widetilde{\mathcal U^\sharp }\).
If \(\widetilde{\mathcal U}\) is in canonical form II, then \(\widetilde{\mathcal U^\sharp }\) is in canonical form II.
Theorem 7.6.4 independently preserves normality and left-canonical normalization under entrywise conjugation, and Theorem 7.6.8 preserves these properties under the physical-pair swap. Conjugating the coisometry equation gives
Conjugating the reconstruction at the swapped physical index gives
Finally, each diagonal positive matrix \(\Lambda _k\) is real, and therefore
Physical relabeling leaves this transfer map unchanged, which proves the transformed fixed-point equation.
If canonical-form-II data for \(\widetilde{\mathcal U}\) have full support, then the data from Definition 18.4.22 also have full support.
Complex conjugation of the weights leaves the block indices and their bond dimensions unchanged, so the full-support sum is unchanged.
Physical adjunction exchanges the two source ranks:
Apply Theorem 18.4.19 and use invariance of matrix rank under conjugate transpose.
A bijective relabeling of the physical basis simultaneously relabels the physical component of every source-cut row and column. Hence
with the right and left orientations unchanged.
Evaluate each cut after relabeling. In both cuts the upper physical index lies in the row and the lower physical index lies in the column, with the virtual index occupying the other product coordinate. Applying \(e\) to both physical coordinates gives the two displayed row-and-column equivalences.
Bijective physical relabeling preserves both source ranks:
Matrix rank is unchanged by bijective row and column relabelings. Apply this fact to the two source-cut identities.
Let \(A=\{ A^i\} _{i\in \{ 0,\ldots ,d{-}1\} }\) and \(B=\{ B^k\} _{k\in \{ 0,\ldots ,e{-}1\} }\) have auxiliary dimensions \(D\) and \(E\), respectively. Write
for the standard finite-product coordinate bijection. Their independent tensor product \(A\boxtimes B\) has physical dimension \(de\), auxiliary dimension \(DE\), and local matrices determined by
For every \(N\), the same coordinates give the pointwise splitting
This is infrastructure for the tensoring clause in the proof of the MPU Index Theorem IV.6(ii) [ 16 , lines 824–845 ] , not a separately stated theorem of that paper. The notation \(A=\{ A^i\} _i\) agrees with the canonical-form block notation in [ 13 , Section 2.3, lines 214–245 ] .
If \(w\) has length \(n\) and
then
Induct on the length of \(w\). For the empty word, use \(\mathbb {1}_D\otimes \mathbb {1}_E=\mathbb {1}_{DE}\) and invariance of the identity under the coordinate bijection. For a leading letter \(\pi _{d,e}(i,k)\), equation (125) and the induction hypothesis reduce the claim to
after transporting multiplication through the same coordinate bijection.
Let \(S_N(A)=\operatorname{span}_{\mathbb {C}}\{ A^w:|w|=N\} \). The pointwise splitting of length-\(N\) words gives
In particular, if \(S_N(A)=M_{D}(\mathbb {C})\) and \(S_N(B)=M_{E}(\mathbb {C})\), then \(S_N(A\boxtimes B)=M_{DE}(\mathbb {C})\). If \(A\) and \(B\) are algebraically normal, then \(A\boxtimes B\) is algebraically normal.
This is the homogeneous-word infrastructure for the tensoring sentence in the proof of the MPU Index Theorem IV.6(ii) [ 16 , lines 824–845 ] , not a separate theorem stated there. It applies to the retained blocks in the canonical-form decomposition [ 13 , Section 2.3, lines 214–245 ] .
For every product word \(w\), let \((u,v)\) be its pointwise component words. The bijection between \(w\) and \((u,v)\) and Theorem 18.4.29 give
which proves (132) after taking linear spans. Pure tensors span \(M_{D}(\mathbb {C})\otimes M_{E}(\mathbb {C})\). The Kronecker linear equivalence, followed by simultaneous reindexing along \(\pi _{D,E}\), is an isomorphism onto \(M_{DE}(\mathbb {C})\); this proves the fixed-length consequence. If \(S_{N_A}(A)=M_{D}(\mathbb {C})\) and \(S_{N_B}(B)=M_{E}(\mathbb {C})\) for positive \(N_A,N_B\), then persistence at positive multiples gives
Applying the fixed-length consequence at \(N_A N_B\) proves algebraic normality of \(A\boxtimes B\).
Let \(A\) and \(B\) be CPSV normal tensors, and suppose that
Then \(A\boxtimes B\) is a CPSV normal tensor and is left-canonical:
This is the retained-normal-block infrastructure for the tensoring sentence in the proof of the MPU Index Theorem IV.6(ii) [ 16 , lines 824–845 ] , not a separate theorem stated there. The retained-normal-block terminology is that of the canonical-form decomposition in [ 13 , Section 2.3, lines 214–245 ] ; the two left-canonical identities are explicit infrastructure hypotheses, not an additional assertion attributed to that passage.
The adjoint and multiplication laws for Kronecker products, together with the fact that simultaneous reindexing preserves adjoints, products, and finite sums, give
proving (136). Spectral normality gives positive lengths \(N_A,N_B\) at which the two homogeneous word spans are full. Theorem 18.4.30 therefore makes \(A\boxtimes B\) algebraically normal at the common length \(N_A N_B\). The algebraically normal, left-canonical tensor is CPSV normal by Theorem 7.6.3.
Let \(\mathcal U\) and \(\mathcal V\) have physical dimensions \(d,e\) and auxiliary dimensions \(D,E\), respectively. Their independent tensor product \(\mathcal U\boxtimes \mathcal V\) has dimensions \(de\) and \(DE\) and entries
A product-valued physical configuration splits sitewise into one configuration for \(\mathcal U\) and one for \(\mathcal V\).
A blocked word of \(L\) product letters separates canonically into two blocked words:
The map decodes the length-\(L\) word, splits every letter into its \(d\) and \(e\) components, and re-encodes the two resulting words.
If \(q\) denotes the blocked product-alphabet equivalence, then each site \(s\) satisfies
Each equality follows by composing the inverse product encoding at every site with the corresponding projection.
For every system size \(N\), the sitewise configuration bijection identifies the finite-size operator with
Grouping the two auxiliary indices makes every closed-word matrix a Kronecker product. The identity
then gives the stated finite-size operator after the sitewise configuration bijection.
The independent tensor product of two matrix product unitary tensors is a matrix product unitary tensor. This is the tensoring operation in the proof of [ 16 , Theorem IV.6(ii) ] .
The multiplication rule \((A\otimes B)(C\otimes D)=AC\otimes BD\) gives
Simultaneous reindexing preserves this unitarity equation.
For every blocking length \(L\), separating each blocked product letter by the canonical equivalence \(q\) gives the exact identity
The ordering of the two component words agrees with the independent tensor-product convention.
Evaluate both sides on blocked ket and bra letters. Word multiplication of local Kronecker products gives
The two decoding identities identify \(I_1,I_2\) and \(J_1,J_2\) with the corresponding letters of \(q(I)\) and \(q(J)\).
For four finite index sets, the source-cut shuffle sends
It is applied to the row and column products with the orders appropriate to \(M_1\) and \(M_2\).
The source cuts satisfy
Thus the paper’s right and left orientations are unchanged.
Evaluate both source cuts entry by entry after the displayed row and column shuffles. Each entry is the product of the corresponding entries of the two source cuts.
The right and left source-cut ranks are multiplicative:
This is the rank-multiplication ingredient for the tensoring case in the proof of [ 16 , Theorem IV.6(ii) ] .
Matrix rank is unchanged by row and column bijections and satisfies \(\operatorname {rank}(A\otimes B)=\operatorname {rank}(A) \operatorname {rank}(B)\).
Let \(W_{\mathcal U}\) and \(W_{\mathcal V}\) be the double layers of \(\mathcal U\) and \(\mathcal V\). Identify the double-layer bond space of \(\mathcal U\boxtimes \mathcal V\) with the tensor product of the two double-layer bond spaces by \(((\alpha ,\gamma ),(\alpha ',\gamma '))\mapsto ((\alpha ,\alpha '),(\gamma ,\gamma '))\). Under this identification,
The contracted physical index of the product runs over pairs \((m,n)\), and each summand factors as a product of an entry of \(\sum _m(\mathcal U^{mi})^{*}\otimes \mathcal U^{mj}\) and an entry of \(\sum _n(\mathcal V^{nk})^{*}\otimes \mathcal V^{n\ell }\).
If \(\mathcal U\) and \(\mathcal V\) are simple, then \(\mathcal U\boxtimes \mathcal V\) is simple. If \(a,b\) are witnesses for \(\mathcal U\) and \(a',b'\) are witnesses for \(\mathcal V\), then \(a\otimes a'\) and \(b\otimes b'\) are witnesses for the product. This is the step behind the sentence “The case of tensoring is trivial” in the proof of [ 16 , Theorem IV.6(ii) ] .
By Lemma 18.4.41, and since \(|b\otimes b')(a\otimes a'|=|b)(a|\otimes |b')(a'|\),
The rule \((A\otimes B)(C\otimes D)=AC\otimes BD\) reduces (12) for the product to the same identity for each factor.
Let \(\mathcal U^{[L]}\) denote the direct blocking of \(L\) sites of a tensor \(\mathcal U\) with physical dimension \(d\), and let \(r_L\) and \(\ell _L\) be its right and left source-cut ranks. Then
These are the one-site forms of the two upper bounds in the proof of [ 16 , Proposition IV.2 ] .
For the first cut, choose a compact factorization of the source matrix of \(\mathcal U^{[L]}\) through a space of dimension \(r_L\). Split each physical word of length \(L+1\) into its first letter and its remaining word of length \(L\). For suitable rectangular matrices \(A_{1,L}\) and \(B_{1,L}\), the successor source matrix factors as
The intermediate space is \(\mathbb C^d\otimes \mathbb C^{r_L}\), and hence
Interchanging the upper and lower physical indices gives matrices \(A_{2,L}\) and \(B_{2,L}\) with
This factorization passes through \(\mathbb C^d\otimes \mathbb C^{\ell _L}\), so
If \(L_0\leq L\), then
These are the two blocking upper bounds used in the proof of [ 16 , Proposition IV.2 ] .
Induct on \(L-L_0\). The case \(L=L_0\) is equality. For the right rank, the successor bound and the induction hypothesis give
The same multiplication by \(d\) gives
Let \(d{\gt}0\) and \(L_0\leq L\). Suppose the endpoint source-cut ranks satisfy the supplied product identities
Then the blocking bounds are exact:
This is the saturation step in the proof of [ 16 , Proposition IV.2 ] .
The blocking bounds give
Their upper bounds have product
Since \(d{\gt}0\), the latter product is positive, so both \(r_L\) and \(\ell _L\) are positive. Hence neither upper bound can be strict, and both equalities follow.
The row space of \(M_1\) has product order \((\text{upper physical},\text{right auxiliary})\). For \(\rho \in M_{D}(\mathbb {C})\), define
This is the source weight in [ 16 , equation labelled Y1Y1X1X1 ] .
If \(\rho \) is positive definite, then \(W_\rho \) is positive definite.
The Kronecker product of the positive-definite matrices \(\mathbb {1}_d\) and \(\rho \) is positive definite.
Choose compact singular-value decompositions
with intermediate dimensions \(r\) and \(\ell \), respectively. For \(\rho \in M_{D}(\mathbb {C})\), define the compressed positive metric
The inverse square root \(A^{-1/2}\), rather than \(A\) itself, is the normalization factor used in the first weighted source factor. This is the source-factor construction of [ 16 , Section III ] .
If \(\rho \) is positive definite, then \(A\) is positive definite.
The map \(V_1^\dagger \) is injective because \(V_1V_1^\dagger =\mathbb {1}_r\). Positive definiteness of \(W_\rho \) is therefore preserved by this congruence.
Let \(\rho \in M_{D}(\mathbb {C})\) be positive definite and let compact decompositions of the two source cuts be given (any; the chosen ones of Definition 18.4.48 are one value). Define
These are the factors in [ 16 , Section III ] .
Since \(A\) is positive definite, its support projection is the identity and
Therefore
For the second cut, \(V_2V_2^\dagger =U_2U_2^\dagger =\mathbb {1}_\ell \) and \(D_2D_2^{-1}=\mathbb {1}_\ell \) give
Two compact decompositions \(M=V^\dagger DU=V'^\dagger D'U'\) of one source cut have \(V^\dagger V=V'^\dagger V'\) and \(U^\dagger U=U'^\dagger U'\), and \(x=V'V^\dagger \) is a unitary of the intermediate space with \(V'=xV\) and \(D'U'=xDU\). With the unitaries \(x_1\), \(x_2\) of the two cuts, the factors built from the second decompositions are \(X_i'=X_ix_i^\dagger \), \(Y_i'=x_iY_i\), \(Z_i'=Z_ix_i^\dagger \), and the gates are \(u'=(x_2\otimes x_1)u\) and \(v'=v(x_1^\dagger \otimes x_2^\dagger )\). The source does not fix a decomposition (line 479: "using a singular value decomposition, we can write"); this theorem shows that none of its gate statements depends on the choice.
From \(UU^\dagger =\mathbb {1}\) and the invertibility of \(D\), \(V^\dagger =MU^\dagger D^{-1}\), and \(V'^\dagger V'M=M\); hence \(V'^\dagger V'\, V^\dagger V=V^\dagger V\), and by symmetry the other product; both projections are Hermitian, so they are equal. Then \(x=V'V^\dagger \) is unitary with \(xV=V'\) and \(D'U'=V'M=xVM=xDU\). The compressed metric transforms as \(A'=x_1Ax_1^\dagger \), and the continuous functional calculus commutes with a unitary conjugation, so \(A'^{\pm 1/2}=x_1A^{\pm 1/2}x_1^\dagger \); the factor and gate identities follow by substitution.
Let \(\mathcal U\) be a matrix product unitary in canonical form II with \(\rho \) its fixed matrix, and let the factors and gates be built from any compact decompositions of its two source cuts. Then \(u\) is an isometry; \(\mathcal U\) is simple if and only if \(u\) is unitary, if and only if \(v\) is unitary; if \(\mathcal U\) is simple, its two-site block carries standard-form data with these gates; and if \(\mathcal U\), \(\mathcal V\) are simple, in canonical form II, of the same bond dimension, with equal periodic operators at every length greater than one, then for any decompositions of the cuts of each there are identifications of the rank spaces and unitaries \(x\), \(y\) with \(u_{\mathcal V}=(x\otimes y)u_{\mathcal U}\) and \(v_{\mathcal V}=v_{\mathcal U}(y^\dagger \otimes x^\dagger )\); conversely, gates so related give equal operators on every ring of even length. The two-site operator is \(v\) times the swapped \(u\) for the factors of any decomposition, and the factor relations under a bond unitary hold for any decompositions of the two tensors. Standard-form data transport along gate gauges: from data with gates \(u,v\) and unitaries \(x\), \(y\) one obtains data with gates \((x\otimes y)u\), \(v(y^\dagger \otimes x^\dagger )\).
The gates of any choice are those of the fixed choice multiplied by the unitaries \(x_2\otimes x_1\) and \(x_1^\dagger \otimes x_2^\dagger \); isometry and unitarity are preserved, the standard-form data transport along the gauge, and the gate relation of the fundamental theorem composes with the change-of-decomposition unitaries of each tensor.
The two factorizations are
These are the source decompositions in [ 16 , Section III ] .
 \(=\)
 \(=\)

The source-factor construction supplies \(M_1=X_1Y_1\). The second compact singular-value decomposition gives \(M_2=X_2Y_2\) directly.
The entries of the two products satisfy
These are the two graphical entry identifications in [ 16 , Section III ] .
Evaluate the two matrix factorizations at \(((i,\beta ),(\alpha ,j))\) and \(((\alpha ,i),(j,\beta ))\), respectively.
The left factors satisfy
These are [ 16 , Section III ] .
The source-factor construction supplies \(X_1^\dagger W_\rho X_1=\mathbb {1}_r\); evaluating at \((r,r')\) gives the displayed weighted sum. Since \(X_2=V_2^\dagger \), the coisometry identity \(V_2V_2^\dagger =\mathbb {1}_\ell \) gives \(X_2^\dagger X_2=\mathbb {1}_\ell \); evaluating at \((l,l')\) gives the second displayed entry sum.
For every tensor \(\mathcal U\), physical indices \(p,q\), and auxiliary indices \(a,b\),
Thus the factor indexed by \((p,a)\) is starred and the factor indexed by \((q,b)\) is unstarred. This is the second-cut rotation used in [ 16 , Theorem III.8, Section III.B, equations (31)–(32) ] . The identity requires no Matrix Product Unitary, dimension, positivity, or simple-tensor hypothesis.
Substitute the entry factorization \(M_2=X_2Y_2\) into the left-hand side and reorder the finite sums. The contraction of the two \(X_2\) factors is \(X_2^\dagger X_2=\mathbb {1}_\ell \), so the two source indices coincide and the remaining sum is the displayed Gram matrix of \(Y_2\).
The right source factors are recovered from the two source matrices by
Here \(W_\rho =I_d\otimes \rho \) in the product-index order \((\text{upper physical},\text{right auxiliary})\).
Multiply \(M_1=X_1Y_1\) on the left by \(X_1^\dagger W_\rho \) and use \(X_1^\dagger W_\rho X_1=I_r\). Similarly, multiply \(M_2=X_2Y_2\) on the left by \(X_2^\dagger \) and use \(X_2^\dagger X_2=I_\ell \).
The right factors satisfy
This is [ 16 , Section III ] .
The source-factor construction supplies \(Y_1Z_1=\mathbb {1}_r\). For the second cut,
Given source-cut decompositions \(M_1=X_1Y_1\) and \(M_2=X_2Y_2\), define
Thus \(u:\mathbb {C}^{d^2}\to \mathbb {C}^{\ell r}\) has source order \(\ell \times r\), while \(v:\mathbb {C}^{r\ell }\to \mathbb {C}^{d^2}\) has source order \(r\times \ell \). These are the literal triangle contractions in [ 16 , Section III, equations uuvv–vdagger ] .
 \(=\)

 \(=\)

Identify a two-site physical configuration with an ordered pair in \(\{ 0,\ldots ,d{-}1\} \times \{ 0,\ldots ,d{-}1\} \). Then
where \(\operatorname {swap}_{r,\ell }\) reorders the source index of \(u\) from \(\ell \times r\) to the \(r\times \ell \) order carried by the columns of \(v\) and reverses the two physical input coordinates. This is the exact two-site factorization through the paper gates \(u\) and \(v\) of CPSV17 SVDforms2–uuvv.
Expand the periodic trace through \(M_1=X_1Y_1\) and \(M_2=X_2Y_2\). Reordering the four scalar finite sums gives
Reindexing both physical configuration spaces and swapping \((l,r)\) to \((r,l)\) gives the matrix identity.
For \(q=(q_1,q_2)\) and \(j=(j_1,j_2)\), the untraced two-site product is
The intermediate contraction is
Expand \(v\) as the contraction of \(X_1\) with \(X_2\). Contracting \(X_1\) with \(Y_1\) gives the first tensor letter, while contracting \(X_2\) with \(Y_2\) gives the second. Reordering the finite sums proves the open product identity. The concrete blocked formula follows by encoding both physical pairs through \(\{ 0,\ldots ,d{-}1\} \times \{ 0,\ldots ,d{-}1\} \simeq \{ 0,\ldots ,({-}1\} d^2)\).
The same untraced two-site product also satisfies
The product indices of \(u\) are \((l,r)\) on the source side and \((j_1,j_2)\) on the physical side.
Expand the first tensor letter through \(M_2=X_2Y_2\) and the second through \(M_1=X_1Y_1\). The common auxiliary index contracts \(Y_2\) with \(Y_1\) to give \(u\). Summing the two remaining source indices gives the formula. The concrete blocked identity follows by decoding its physical indices into ordered pairs.
Assume \(d{\gt}0\). For any MPO tensor \(\mathcal U\), tail length \(K\), and \(p,q\in \{ 0,\ldots ,d{-}1\} \times \{ 0,\ldots ,d{-}1\} \), let \(W\) be its double layer and let \(E=d^{-1}\sum _i W^{ii}\) be the normalized physical diagonal. Then
Thus \(p\) labels the starred input and \(q\) the unstarred input. This is the closed input-tail expression occurring on the right-hand side of [ 16 , equation uUnitary and lines 550–556 ] .
Closing the common output word gives the double-layer identity
Set \(\sigma =(p,\tau )\) and \(\sigma '=(q,\tau )\). Splitting off the two retained sites rewrites the right-hand side as
Finally,
Substitute this expansion and use linearity of the trace.
Put
with source-bond order \(r\times \ell \). Thus \(Y\) maps \((\mathbb {C}^D\otimes \mathbb {C}^d)\otimes (\mathbb {C}^d\otimes \mathbb {C}^D)\) to \(\mathbb {C}^r\otimes \mathbb {C}^\ell \), and \(Z\) maps in the opposite direction. The regrouping of the open indices is
where \(\operatorname {flat}:\{ 0,\ldots ,D{-}1\} \times \{ 0,\ldots ,D{-}1\} \simeq \{ 0,\ldots ,({-}1\} D^2)\) is the canonical product enumeration. The dressed source-\(v\) Gram equation is
These are the tensorized factors surrounding \(v^\dagger v\) in [ 16 , Theorem III.8, Section III.B, equations (31)–(32) ] .
Let \(p=(p_1,p_2)\) be the starred physical pair, \(q=(q_1,q_2)\) the unstarred pair, and let \(a=(a_1,a_2)\) and \(b=(b_1,b_2)\) be virtual paths. The weighted first-cut contraction is
The entry of two ordinary double-layer letters from row \((a_1,b_1)\) to column \((a_2,b_2)\) is
Set
Inserting \(|\rho '\rangle \! \langle \Phi '|\) between the two letters gives
Finally, the Gram entry of \(Y_1\otimes Y_2\) expands as
Expand the ordinary and rank-one-inserted matrix products entrywise. For the tensorized Gram entry, use \(X_1^\dagger (\mathbb {1}_d\otimes \rho )X_1=\mathbb {1}_r\) on the first cut and \(X_2^\dagger X_2=\mathbb {1}_\ell \) on the second cut, then reorder the finite sums. No ambient identity \(X_2X_2^\dagger =\mathbb {1}\) is used.
Let \(\rho {\gt}0\). For \(z=(z_1,z_2)\), \(p=(p_1,p_2)\), and \(a=(a_1,a_2)\),
This is the local open-leg identity for the literal gate \(v=X_1\mathbin {-}X_2\).
Expand the matrix product and tensor product, reorder the finite sums, and contract \(X_1Y_1\) and \(X_2Y_2\) by the two source-cut factorizations.
The tensorized source factors satisfy
Multiplicativity of the Kronecker product gives
For every positive definite source weight \(\rho \), and for \(x=R^{-1}(p,a)\) and \(y=R^{-1}(q,b)\), the dressed Gram equation is equivalent to
Here \(p,q\in \{ 0,\ldots ,d{-}1\} \times \{ 0,\ldots ,d{-}1\} \), \(a,b\in \{ 0,\ldots ,({-}1\} D^2)\), the indices \(s,t\) range over \(\{ 0,\ldots ,r{-}1\} \times \{ 0,\ldots ,\ell {-}1\} \), and \(z\) ranges over \(\{ 0,\ldots ,d{-}1\} \times \{ 0,\ldots ,d{-}1\} \).
Evaluate both sides of \(Y^\dagger (v^\dagger v)Y=Y^\dagger Y\) at \((x,y)\) and expand the three matrix products. Conversely, apply the displayed equality after regrouping each pair of open source-cut indices by \(R\).
If \(Y\) has a right inverse \(Z\), so that \(YZ=\mathbb {1}\), then for every square matrix \(G\) on the row space of \(Y\),
Multiplying \(Y^\dagger GY=Y^\dagger Y\) by \(Z^\dagger \) on the left and \(Z\) on the right, and using \(YZ=\mathbb {1}\), gives
The converse is immediate.
For every positive definite source weight \(\rho \),
Apply right-inverse cancellation with \(G=v^\dagger v\) and \(Z=Z_1\otimes Z_2\).
If the physical and auxiliary dimensions are \(d\) and \(D\), respectively, then
The matrix \(M_1\) has \(dD\) columns. Its rank is at most its number of columns, hence at most \(dD=Dd\).
If the physical and auxiliary dimensions are \(d\) and \(D\), respectively, then
The matrix \(M_2\) has \(dD\) columns. Its rank is at most its number of columns, hence at most \(dD=Dd\).
18.5 Full-support canonical representatives
Let
be CPSV canonical-form data in ambient bond dimension \(D\), where every \(A_k\) has positive bond dimension \(D_k\). The data have full support when
Let \(d,D{\gt}0\), let \(U\) be an MPU tensor of physical dimension \(d\) and bond dimension \(D\), and let \(\widetilde U=d^{-1/2}U\) be its normalized doubled-index tensor. There are an integer \(D_{\mathrm{red}}{\gt}0\), a normal tensor \(A_{\mathrm{red}}\) of bond dimension \(D_{\mathrm{red}}\), canonical-form-II data for \(A_{\mathrm{red}}\), and a matrix \(\rho \) on the ambient bond space of \(A_{\mathrm{red}}\) such that, for every integer \(N{\gt}0\) and every word \(\sigma \) of length \(N\),
and \(\rho \) is positive definite and diagonal with
This organizes the dimension-bounded canonical replacement used in [ 16 , lines 257–294 and 319–326 ] . Its irreducible reduction and canonical-form-II gauge are those of [ 13 , lines 195–255 and 1058–1077 ] . The shifted transfer argument is the one used in [ 16 , lines 344–356 ] , and the diagonal positive trace-one ambient right fixed matrix is the one of [ 16 , lines 269–281 ] .
Remove the zero irreducible blocks of \(\widetilde U\) and write
for every \(N{\gt}0\) and every word \(\sigma \) of length \(N\). At \(N=2\) the common self-overlap is one, so the retained sum is nonempty and \(D_0=\sum _kD_k{\gt}0\). For every integer \(N{\gt}1\), overlap invariance gives
Let \(J_k:\mathbb C^{D_k}\to \mathbb C^{D_0}\) be the inclusion of the \(k\)th block. Then
Thus every nonzero transfer eigenvalue of \(B_k\) is a nonzero eigenvalue of \(E_{A_0}\) and hence equals one by (231). Perron–Frobenius theory supplies \(\rho _k{\gt}0\) and \(s_k{\gt}0\) with \(\mathcal{E}_{B_k}(\rho _k)=s_k\rho _k\). Therefore \(s_k=1\), and every peripheral eigenvalue of \(B_k\) is also one. Each \(B_k\) is consequently normal.
The direct sum now has literal canonical-form data with full support. Apply the nonsingular blockwise canonical-form-II gauge. It preserves the block dimensions and all periodic vectors, so the resulting tensor \(A_1\) still satisfies
for every integer \(N{\gt}1\). The shifted traces force \(r=1\) and \(\left|\mu _1\right|=1\), and full support identifies the unique retained block with the ambient bond space, so its inclusion \(J_1\) is a unitary of \(\mathbb C^{D_{\mathrm{red}}}\):
The retained block carries a diagonal positive definite fixed matrix \(\Lambda _0\) of its own transfer map; rescale it to \(\Lambda =\operatorname{tr}(\Lambda _0)^{-1}\Lambda _0\), so that
the last equality because \(\left|\mu _1\right|=1\). Now conjugate the ambient tensor by \(J_1\) and read the block matrix in the resulting coordinates:
Since \(J_1\) is unitary this is a change of ambient coordinates: \(A_1^i=J_1A_{\mathrm{red}}^iJ_1^\dagger \), so \(A_1\) and \(A_{\mathrm{red}}\) have the same matrix product vectors at every positive length. The canonical-form-II data travel along the same factor: if \(\Phi \) is the ambient coisometry reconstructing \(A_1\) from the blocks \(B_k\) and the weights \(\mu _k\), then \(\Phi J_1\) is again a coisometry and reconstructs \(A_{\mathrm{red}}\) from those same blocks and weights,
The fixed matrix transports along the same conjugation:
and \(\rho \) is positive definite, diagonal, and of trace one because \(\Lambda \) is. This is (228).
It remains to see that the conjugated tensor is normal. Transport the trace identity to it: for every integer \(N{\gt}1\),
These shifted traces force the spectral radius of \(E_{A_{\mathrm{red}}}\) to be one and \(E_{A_{\mathrm{red}}}\) to be primitive. Together with \(r=1\) and full support, both preserved by the conjugation, they make \(A_{\mathrm{red}}\) normal.
Let \(d,D{\gt}0\) and let \(U\) be an MPU tensor. There are \(D_{\mathrm{red}}{\gt}0\) and an MPO tensor \(U_{\mathrm{red}}\) of bond dimension \(D_{\mathrm{red}}\) carrying a canonical-form-II presentation in the sense of Definition 18.8.8 such that, for every integer \(N{\gt}0\),
In particular \(U_{\mathrm{red}}\) is an MPU, the retained block dimensions of its normalized doubled-index tensor sum to \(D_{\mathrm{red}}\), and the ambient right fixed matrix of that presentation is positive definite, diagonal, and of trace one. No equality is asserted at length zero, and no virtual gauge is asserted between the two potentially unequal-dimensional bond spaces.
Apply Theorem 18.5.2 and write its representative as \(A_{\mathrm{red}}\). Define
Since \(d{\gt}0\), normalization recovers \(A_{\mathrm{red}}\) exactly. For every \(N{\gt}0\) and every ket–bra pair \((\sigma ,\tau )\), the doubled-index coefficient identity gives
Hence the periodic operators agree at every positive length. For \(N{\gt}1\) the right side is unitary, so \(U_{\mathrm{red}}\) is an MPU. Its normalized doubled-index tensor is \(A_{\mathrm{red}}\), so the canonical-form-II data, the full-support identity, and the diagonal positive trace-one ambient right fixed matrix supplied by Theorem 18.5.2 assemble into a canonical-form-II presentation of \(U_{\mathrm{red}}\).
Suppose that canonical-form data have full support:
Then every positive physical blocking of these data also has full support.
Positive blocking supplies canonical-form data with the same block dimensions, so the full-support sum is unchanged.
A bijective relabeling of the physical alphabet preserves full support of canonical-form data.
Physical relabeling leaves the blocks and their bond dimensions unchanged, so the full-support sum is unchanged.
If a block has bond dimension \(D\), then the ambient tensor \(A\) is irreducible.
If \(k\) is the block with \(D_k=D\), the total-dimension bound gives
Since every retained block dimension is positive, these equalities force \(k\) to be the only retained block. After reindexing its bond coordinates, the ambient coisometry \(U\) is square, hence unitary, and reconstruction reads
where \(B\) is the reindexed normal block and \(\mu _k\ne 0\). Thus Theorem D.3.4 transports irreducibility of \(B\) through the nonzero rescaling and unitary conjugation.
Canonical-form data with one block and full support reconstruct an irreducible ambient tensor.
Let \(k\) be the unique block. The singleton sum and full-support identity give
Thus \(k\) has ambient bond dimension, so Theorem 18.5.6 applies.
Suppose that canonical-form data have one block and full support. If the transfer map has spectral radius one and is primitive, then the ambient tensor is a normal tensor.
Combine Theorem 18.5.7 with the supplied spectral-radius and primitivity properties.
18.6 Transfer-matrix identities
Let \(D\) be a positive integer and let \(T:M_D(\mathbb C)\to M_D(\mathbb C)\) be a linear map. The transfer matrix \(\widehat T\) of \(T\) under the column-stacking identification \(M_D(\mathbb C)\cong \mathbb C^{D^2}\) is developed in the companion quantum-channel volume [ 216 , “Transfer matrix of a matrix endomorphism”, “Transfer matrix in one family”, “Functoriality of transfer matrices”, “Trace preservation fixes the vectorized identity on the left”, “Powers and traces of transfer matrices” ] .
A complex number \(\mu \) is an eigenvalue of \(T\) if and only if it is an eigenvalue of \(\widehat T\).
Column stacking is a linear bijection and intertwines \(T\) with multiplication by \(\widehat T\). It therefore carries nonzero eigenmatrices to nonzero eigenvectors and conversely.
For a matrix product tensor \(A\), write \(V^{(N)}(A)_\sigma \) for the coefficient of its length-\(N\) periodic vector at the configuration \(\sigma \).
Let \(A\) and \(B\) be matrix product tensors with the same positive bond dimension, and let \(F_{A,B}(X)=\sum _i A^iX(B^i)^\dagger \) be their mixed transfer map. Then
In particular, taking \(B=A\) identifies the trace of the \(N\)th power of the ordinary transfer matrix with the length-\(N\) self-overlap.
Replace the matrix power by the transfer matrix of the corresponding operator power, identify matrix trace with operator trace, and expand the latter over periodic words. For the ordinary self-transfer statement, specialize to \(B=A\) and use the identity \(F_{A,A}=\mathcal E_A\) from Theorem B.1.1.
For an MPO tensor \(U\) of physical dimension \(d{\gt}0\), its normalized flattening is the doubled-physical-index MPS tensor
This is the normalization used in the normal-tensor argument of [ 16 , Section III, equation (13) ] .
Write \(\pi _{m,n}:\{ 0,\ldots ,m{-}1\} \times \{ 0,\ldots ,n{-}1\} \to \{ 0,\ldots ,mn{-}1\} \) for the standard product coordinate bijection. For natural numbers \(d,e\), the canonical doubled product-coordinate equivalence \(s_{d,e}:\{ 0,\ldots ,(de)^2{-}1\} \to \{ 0,\ldots ,d^2e^2{-}1\} \) and its inverse satisfy
Let \(\mathcal U\) and \(\mathcal V\) have physical dimensions \(d,e\) and auxiliary dimensions \(D,E\), respectively. With the coordinate equivalence \(s_{d,e}\) of Definition 18.6.4, normalized flattening obeys
For positive physical dimensions this uses the normalization of [ 16 , Section III, equation (13) ] . With the totalized inverse convention \(0^{-1}=0\), the algebraic identity also holds when \(d=0\) or \(e=0\). This identity expresses the normalized-flattening compatibility for the tensor product in [ 16 , Theorem IV.6(ii), lines 824–845 ] .
Apply the two product-coordinate entry formulas after the regrouping in (256). The scalar normalizations agree because
Multiplying this identity by \(\mathcal U^{i,j}_{\alpha ,\beta } \mathcal V^{k,\ell }_{\gamma ,\delta }\) gives (257).
Let \(A\) and \(B\) have chosen canonical-form-II data with retained blocks \(A_a\) and \(B_b\), dimensions \(D_a\) and \(E_b\), weights \(\mu _a\) and \(\nu _b\), diagonal positive-definite fixed points \(\Lambda _a\) and \(\Gamma _b\), and ambient coisometries \(V_A\) and \(V_B\). Write \(\pi _{m,n}\) for the standard product-coordinate equivalence and let \(\chi \) be the retained-coordinate equivalence
The product ambient coisometry is
For each retained pair \((a,b)\), the chosen product data are
and
The exact reconstruction is
Thus the retained direct sum is conjugated by the reindexed Kronecker ambient coisometry, rather than identified directly with the ambient tensor. For MPO tensors \(\mathcal U\) and \(\mathcal V\), the doubled physical equivalence of Theorem 18.6.5 identifies these data with canonical-form-II data for \(\widetilde{\mathcal U\boxtimes \mathcal V}\).
Full support is a supplied reduced-representative restriction. If the two chosen input data satisfy
and
then the chosen product data satisfy
Identifying canonical-form-II data along an equality of ambient tensors leaves this retained-dimension sum unchanged. This full-support assertion is not stated by the tensoring sentence in [ 16 , Theorem IV.6(ii) ] ; it is the supplied restriction documented in [ 58 ] .
For the independent tensor product, the raw source ranks satisfy \(r(\mathcal U\boxtimes \mathcal V)=r(\mathcal U)r(\mathcal V)\) and \(\ell (\mathcal U\boxtimes \mathcal V)=\ell (\mathcal U)\ell (\mathcal V)\) by Theorem 18.4.40.
For physical labels \(i\) and \(k\), set
and
Regrouping retained coordinates by \(\chi \) gives the weighted-block-diagonal identity
Substitute \(A^i=V_A^\dagger \mathsf B_A^iV_A\) and \(B^k=V_B^\dagger \mathsf B_B^kV_B\). The mixed-product law for Kronecker products and the definition of \(W\) then give (265). The relation \(W W^\dagger =\mathbb {1}\) follows from \(V_AV_A^\dagger =\mathbb {1}\) and \(V_BV_B^\dagger =\mathbb {1}\). Left-canonicality and normality follow from Theorem 18.4.31.
For arbitrary matrices \(X\) and \(Y\), direct expansion of the finite Kraus sums gives
Taking \(X=\Lambda _a\) and \(Y=\Gamma _b\) proves the fixed-point equation; Kronecker products and bijective reindexing preserve positive definiteness and diagonality. The finite double-sum identity proves the supplied full-support conclusion. Finally apply the normalized-flattening identity and physical relabeling to obtain the MPO statement.
Let \(\mathcal U\) and \(\mathcal V\) be MPUs in canonical form II, with recorded ambient right fixed matrices \(\rho _U\) and \(\rho _V\). Their independent tensor product is in canonical form II in the product bond coordinates. Its recorded matrix is
In particular, the product presentation has full support. This is the canonical-form-II consequence of the independent-product construction used in [ 16 , Theorem IV.6(ii) ] ; the full-support convention is recorded in [ 58 ] .
Tensor the chosen canonical blocks and their diagonal positive fixed matrices, then apply the doubled physical-coordinate relabeling. The retained dimensions multiply and their sum is the product bond dimension. Independent tensor products preserve the MPU property. The product of the two ambient fixed matrices is positive definite, diagonal, and of trace one. In the product bond coordinates, the transfer identity gives
Let \(\mathcal U\) and \(\mathcal V\) be MPO tensors with the same positive physical dimension \(d\), and let
be their composition tensor. Under the canonical identification of its auxiliary space with \(\mathbb {C}^{D_U}\otimes \mathbb {C}^{D_V}\), the normalized flattenings satisfy
This identity combines the raw composition tensor used in the proof of [ 16 , Theorem IV.6(ii) ] with the normalization in [ 16 , Section III, equation (13) ] ; it is not a separately stated result of that proof.
Substitute \(U^{ij}=\sqrt d\, \widetilde U^{ij}\) and \(V^{jk}=\sqrt d\, \widetilde V^{jk}\) into the defining contraction for \(W^{ik}\), and then multiply the result by \(d^{-1/2}\).
Let \(\mathcal U\) be an MPO tensor of physical dimension \(d\), and let \(L\geq 0\). For the normalized-tensor interpretation assume \(d{\gt}0\), as in Definition 18.6.3; with the convention \(0^{-1}=0\), the algebraic identity below also holds for \(d=0\). Pairing the ket and bra letters at each site gives a canonical bijection
If \(\widetilde{\mathcal U}=d^{-1/2}\mathcal U\) denotes normalized flattening, then
Thus normalized flattening commutes with blocking, up to the canonical doubled-index relabeling. This is the normalized form of the blocking operation in [ 16 , Definition II.5 and equation (9) ] .
A blocked letter is a product of \(L\) original letters. The identity
identifies its normalization with the product of the \(L\) one-site normalizations. Theorem 20.15.2 identifies the two physical indexings for every \(L\geq 0\); at \(L=0\) both blocked words are empty and both local matrix products are the identity.
Suppose that an MPS tensor \(A\) is left-canonical:
Then for every \(L\geq 0\) its blocked tensor is left-canonical:
If \(e\) is a bijection of physical alphabets, then \(e^*A\) is left-canonical if and only if \(A\) is:
Let \(A\) have canonical-form-II data with retained weights \(\mu _k\), blocks \(A_k\), and positive definite diagonal fixed matrices \(\Lambda _k\). For every positive integer \(L\), the blocked tensor \(A^{[L]}\) has canonical-form-II data with weights \(\mu _k^L\), blocks \(A_k^{[L]}\), and the same matrices \(\Lambda _k\). The retained blocks remain left-canonical:
A bijective relabeling of the physical alphabet likewise preserves canonical-form-II data, including both the matrices \(\Lambda _k\) and the left-canonical identities.
Consequently, if the normalized flattening \(\widetilde{\mathcal U}\) of an MPO tensor has canonical-form-II data, then for every \(L{\gt}0\) the normalized flattening of \(\mathcal U^{[L]}\) has the data obtained by first blocking and then relabeling by \(\vartheta _L\) from Theorem 18.6.9. Theorem 18.6.10 preserves the left-canonical identity under both operations. For each retained block, Lemma D.4.9 gives
where (285) follows by iterating \(\mathcal{E}_{A_k}(\Lambda _k)=\Lambda _k\). Thus the same positive definite diagonal matrix is fixed after blocking. A physical bijection leaves the transfer map unchanged. The final construction applies these two operations to (279).
Let \(\mathcal U\) be an MPU in canonical form II, with recorded ambient right fixed matrix \(\rho \). For every positive physical blocking length \(p\), the blocked tensor \(\mathcal U^{[p]}\) is in canonical form II in the same bond coordinates, with full support and the same matrix \(\rho \). This is the positive-blocking assertion following [ 16 , Proposition III.1 ] .
Block each canonical tensor and relabel the blocked physical alphabet. Blocking leaves the retained bond dimensions unchanged, so their sum is still the ambient bond dimension. The transfer identities in Definition 18.6.11, together with invariance under physical relabeling, give
Positive definiteness, diagonality, and trace normalization of \(\rho \) are unchanged, and blocking preserves the MPU property.
For a matrix product tensor \(A\), a complex number \(c\), and a nonnegative integer \(N\), scaling every local matrix by \(c\) gives
Consequently, if \(d{\gt}0\) and \(U\) is an MPO tensor of physical dimension \(d\), then
Let \(U\) be an MPU tensor with positive physical and bond dimensions, and let \(E\) be the transfer matrix of its normalized flattening. For every integer \(N{\gt}1\),
This is the trace identity in the proof of the normal-tensor result [ 16 , Proposition III.1 ] .
Scaling both tensor copies by \(1/\sqrt d\) multiplies the length-\(N\) self-overlap by \(d^{-N}\). The doubled-index overlap identity and MPU unitarity give the complete chain
Here (290) uses \(N{\gt}1\), so that the MPU equation applies.
18.7 Block transfer multiplicity
Let the blocks be indexed by \(k\in \{ 0,\ldots ,r{-}1\} \), let \(n_k\) be their nonnegative dimensions, and put \(n=\sum _{k\in \{ 0,\ldots ,r{-}1\} }n_k\). The standard block-order bijection is
For each \(k\in \{ 0,\ldots ,r{-}1\} \), define \(J_k:\mathbb C^{n_k}\to \mathbb C^n\) by
The inclusions satisfy the following identities, with the second holding for distinct \(k\) and \(\ell \):
If \(B^i=\bigoplus _k\mu _k A_k^i\) is a weighted block-diagonal tensor, then
Reindex the canonical dependent-summand inclusion along the equivalence between dependent pairs and flattened coordinates. Transporting its isometry, cross-block orthogonality, and block-diagonal intertwining identities gives the three displayed formulas.
If \(U\) is the reconstruction coisometry and \(J_k\) is the inclusion of the \(k\)th retained block, define
For every retained block and physical index \(i\),
The coisometry \(UU^\dagger =\mathbb {1}\) and \(J_k^\dagger J_k=\mathbb {1}\) give
The canonical reconstruction and block-diagonal intertwining give
For a block \(k\), define its weighted transfer eigenvalue by
If the ambient transfer matrix satisfies \(\operatorname{tr}(E^N)=1\) for every integer \(N{\gt}1\), then every block satisfies
Choose a nonzero fixed matrix \(X_k\) for the unweighted normal block and set \(Y_k=V_kX_kV_k^\dagger \). The isometry and intertwining identities give
Thus \(q_k\) lies in the ambient transfer spectrum; it is nonzero because \(\mu _k\ne 0\). The shifted trace-power spectrum is \(\{ 0,1\} \), hence \(q_k=1\).
If there is exactly one block \(k\) and the blocks fill the ambient bond space, then
The full-support sum reduces to the unique summand:
Therefore \(V_k\) is a square matrix. Since \(V_k^\dagger V_k=\mathbb {1}\), finite equal-dimensional inverse symmetry gives \(V_kV_k^\dagger =\mathbb {1}\).
Let \(A\) have literal CPSV canonical-form data with \(r\) blocks. If its transfer matrix \(E\) satisfies \(\operatorname{tr}(E^N)=1\) for every integer \(N{\gt}1\), then
This is the block multiplicity consequence used in [ 16 , Proposition III.1 ] .
Each normal block \(A_k\) has a nonzero transfer fixed vector \(X_k\). Let \(U\) be the reconstruction coisometry and let \(J_k\) be the flattened inclusion of the \(k\)th block. Define the ambient inclusion and transported matrix by
The matrix \(Y_k\) is nonzero and is an ambient transfer eigenmatrix with eigenvalue \(q_k=\mu _k\overline{\mu _k}\ne 0\). Theorem 18.4.6 gives \(q_k=1\).
For distinct \(k\) and \(\ell \), the inclusion identities give
Hence the matrices \(Y_k\), for \(1\le k\le r\), are linearly independent. Vectorizing gives
For every \(r\ge 1\), the shifted traces and Theorem 18.4.4 give
The eigenspace dimension is bounded by the algebraic multiplicity, so
Finally, if \(r\) were zero, the retained direct sum and therefore \(A\) would vanish, contradicting \(\operatorname{tr}(E^2)=1\). Consequently \(r=1\).
18.8 Normalized transfer spectrum and conditional normality
Let \(T:M_D(\mathbb C)\to M_D(\mathbb C)\) be a linear map with \(D{\gt}0\). If \(\operatorname{tr}(\widehat T^{\, N})=1\) for every integer \(N{\gt}1\), then
This is the radius-and-primitivity part of [ 16 , Proposition III.1 ] .
The shifted traces give
Column stacking identifies the eigenvalues of \(T\) and \(\widehat T\). Consequently every spectral value of \(T\) is zero or one, and one occurs, so
Restricting to eigenvalues of modulus one gives
which is primitivity.
Let \(U\) be an MPU tensor with positive physical and bond dimensions, and let \(E\) be the transfer matrix of its normalized flattening. Then
This is the transfer-matrix conclusion of [ 16 , Proposition III.1 ] .
For every integer \(N{\gt}1\), the normalized transfer identity gives
Applying the exact shifted trace-power theorem in dimension \(D^2\) yields
Let \(U\) be an MPU tensor with physical dimension \(d{\gt}0\) and bond dimension \(D{\gt}1\), and let \(E\) be the transfer matrix of its normalized flattening. There is an integer \(J\) satisfying
and vectors \(\rho ,\Phi \) satisfying
such that
For every integer \(k\geq J\),
Thus blocking \(J\) sites removes the entire generalized zero-eigenspace. The one-dimensional case is stated separately below.
This is the Jordan-elimination step in [ 16 , proof of Proposition III.2(ii) ] .
The exact characteristic polynomial is
Cayley–Hamilton gives \(E^{D^2}=E^{D^2-1}\). Hence every power from \(J=D^2-1\) onward is equal, and \(P=E^J\) is idempotent. Since \(J{\gt}1\), the normalized transfer trace identity gives \(\operatorname{tr}(P)=1\). The range of an idempotent has dimension equal to its trace, so \(P\) has rank one and factors as \(P=\lvert \rho )(\Phi \rvert \). Taking the factors with \((\Phi \mid \rho )=1\) gives the displayed fixed-point identities from \(EP=PE=P\).
Let \(P=E^J\) be a stabilized rank-one transfer power with normalized left and right factors. If \(\rho '\) and \(\Phi '\) are any other fixed vectors with \((\Phi '\mid \rho ')=1\), then
Applying \(P\) to \(\rho '\) and applying \(\Phi '\) to \(P\) shows that the two pairs of rank-one factors differ by reciprocal scalars. Their normalized pairings force the product of those scalars to be one.
Suppose \(d{\gt}0\), \(D{\gt}1\), and \(\mathcal U\) is an MPU whose normalized flattening is presented by chosen canonical-form-II data with blocks filling the bond space. There is a unique block \(k\). Normalize its diagonal positive definite fixed matrix \(\Lambda _k\) to have trace one, and let \(V_k\) be its inclusion into the ambient bond space. Then
where \((\Phi \rvert \) is the vectorized identity. Consequently,
The diagonal matrix is the block matrix \(\Lambda _k\) in the canonical-form-II fixed-point equations in [ 16 , equations (6a)–(6b) ] ; its ambient transport \(\rho \) need not be diagonal, corresponding to the reduced representative in [ 16 , proof of Proposition III.2(ii) ] .
The shifted trace identities satisfy \(\operatorname{tr}(E^N)=1\) for every integer \(N{\gt}1\) and give
Let \(k\) be this block. Canonical form II supplies a diagonal \(\Lambda _0{\gt}0\) fixed by the unweighted block transfer map. Normalize it by
If \(\omega _k\) is its weight, then
where \(E_k\) is the transfer map of the weighted block \(\widetilde B_k=\omega _k B_k\). Full support makes the block inclusion \(V=V_k\) both isometric and onto:
Hence \(\rho =V\Lambda V^\dagger \) is positive definite with trace one, and the intertwining equations \(A_iV=V\widetilde B_k(i)\) give the fixedness transport
The blockwise left-canonical identity transports similarly:
Finally,
where the last equality is the uniqueness of the normalized fixed-pair factorization for the stabilized power.
Let \(\mathcal U\) be an MPU in canonical form II, with ambient fixed matrix \(\rho \). Put \(J=\max (D^2-1,1)\) and \(W=\mathcal U_{JD^2}\). With the vectorized pair \(\rho ',\Phi '\) of \(\rho \) and of the identity, the blocked tensor \(W\) satisfies the two aligned simple contractions
If the physical dimension satisfies \(d{\gt}0\) and the bond dimension is \(D=1\), then the normalized transfer matrix satisfies
Consequently its powers stabilize at the positive exponent one.
In dimension one the characteristic polynomial identity reduces to \(\chi _E(X)=X-1\), and Cayley–Hamilton gives \(E=1\).
Let \(\mathcal U\) be an MPO tensor, and write \(\widetilde{\mathcal U}=d^{-1/2}\mathcal U\) and \(E=\mathcal E_{\widetilde{\mathcal U}}\). A canonical-form-II presentation of \(\mathcal U\) consists of the MPU condition, a literal CPSV canonical-form-II representation
The ambient fixed pair has \(\Phi =\mathbb {1}_D\) and positive coefficients \(\rho _0,\ldots ,\rho _{D-1}\). It satisfies
Thus the retained blocks have literal full support, and \(\rho \) is a positive diagonal trace-one right fixed point in the ambient bond coordinates. This is the standing convention of [ 16 , lines 269–281, 344–356, and 488–502 ] .
Let \(\mathcal U\) generate an MPU, suppose its normalized flattening \(\widetilde{\mathcal U}\) is normal, and let \(L\) be positive definite with \(\mathcal E_{\widetilde{\mathcal U}}^*(L)=L\). There is a unitary \(V\) on the same bond space such that
admits a full-support canonical-form-II presentation. For every \(N\geq 0\), the periodic operators satisfy \(O_N(\mathcal B)=O_N(\mathcal U)\). Both source ranks are preserved: \(r[\mathcal B]=r[\mathcal U]\) and \(\ell [\mathcal B]=\ell [\mathcal U]\). This is the canonical-gauge construction used in the proof of [ 16 , Proposition IV.5, lines 798–804 ] .
Put \(S=L^{1/2}\) and \(\mathcal G^{ij}=S\mathcal U^{ij}S^{-1}\). The adjoint fixed-point equation gives
This is the positive-fixed-point gauge construction of the companion quantum-channel volume [ 216 , Trace-preserving gauge from an adjoint fixed point, Kraus form ] . Normality is preserved by similarity. Theorem 7.10.1 therefore supplies a unitary \(V\) and a positive diagonal fixed matrix \(\Lambda \) after conjugating \(\widetilde{\mathcal G}\) by \(V\). Replace \(\Lambda \) by \(\rho =\Lambda /\operatorname{tr}(\Lambda )\). Positivity gives \(\operatorname{tr}(\Lambda ){\gt}0\), and linearity preserves the fixed-point equation. The resulting normal, left-canonical tensor has a one-block canonical-form-II presentation with weight one and no omitted bond coordinates. Finally, put \(T=S^{-1}V\), so that \(\mathcal B^{ij}=T^{-1}\mathcal U^{ij}T\). The interior factors \(TT^{-1}\) cancel, and cyclicity of the trace removes the outer pair:
Since these traces are the coefficients of the periodic operators, \(O_N(\mathcal B)=O_N(\mathcal U)\) for every \(N\). Since \(S\), \(S^{-1}\), \(V\), and \(V^\dagger \) are invertible, Theorem 18.9.100 applied to the two successive bond transformations proves equality of both source ranks.
If an MPO tensor \(\mathcal U\) admits a canonical-form-II presentation, then its bond space is nonempty and its physical dimension is positive:
Both dimensions are forced by the normalization \(\operatorname{tr}(\rho )=1\) of (344). If \(D=0\), the ambient bond index set is empty and every trace over it vanishes,
If \(d=0\), the physical index set is empty, so the normalized transfer map is an empty sum,
The fixed-point equation \(E(\rho )=\rho \) of (344) then gives \(\rho =0\), hence \(\operatorname{tr}(\rho )=0\neq 1\).
A tensor \(A\) of physical dimension \(d\) and bond dimension \(D\) is in MPU canonical form if there are positive block dimensions \(D_k\), nonzero weights \(\mu _k\in \mathbb C\), tensors \(A_k\) of bond dimension \(D_k\), and a coisometry
such that \(\sum _k D_k=D\) and
Every \(A_k\) is irreducible and the spectral radius of its transfer map is one. The blocks may be periodic, so no uniqueness condition is imposed on their peripheral eigenvalues. This is the canonical form of [ 16 , lines 259–267 ] ; normal tensors form a strictly stronger class. The nonzero-weight and full-support conventions are recorded in [ 77 , 58 ] .
Let \(d\geq 1\). A matrix product unitary tensor in canonical form II is in canonical form.
Canonical form II gives a block decomposition of \(d^{-1/2}\mathcal U\) with normal blocks filling the bond space; a normal block is irreducible with a transfer map of spectral radius one, so the same blocks with the weights multiplied by \(d^{1/2}\) decompose \(\mathcal U\) as canonical form requires.
Let \(d,D\geq 1\) and let \(\mathcal U\) be a matrix product unitary tensor in canonical form. There is an invertible \(X\) on the bond space such that the tensor with letters \(XU^{ij}X^{-1}\) is in canonical form II; it generates the same operators.
The normalized tensor \(d^{-1/2}\mathcal U\) is normal. The adjoint transfer map of a normal tensor has a positive definite fixed point \(\sigma \), and \(\sigma ^{1/2}(\cdot )\sigma ^{-1/2}\) makes the tensor left-canonical and keeps it normal; a unitary then diagonalizes the positive definite fixed point of the transfer map, and division by its trace gives trace one. The result is a one-block canonical-form-II datum with that fixed matrix.
Let \(U\) be an MPU tensor with positive physical and bond dimensions. Suppose that the original local tensor is in canonical form, with nonzero weights and blocks occupying the full ambient bond space. Then the normalized flattening is a normal tensor.
This is the normality assertion of [ 16 , Proposition III.1 ] for the canonical representative adopted before that proposition. The nonzero-weight and full-support conventions are recorded in [ 77 , 58 ] . The spectral assertion of the proposition is Theorem 18.8.2.
Normalizing the local tensor multiplies each weight \(\mu _k\) by \(d^{-1/2}\ne 0\) and leaves each block unchanged. Write \(\widetilde U\) for the normalized flattening and \(E\) for its transfer matrix. For every integer \(N{\gt}1\), unitarity gives
Every nonzero eigenvalue of a weighted block transfer map is an eigenvalue of the ambient transfer map, hence equals one. Irreducibility and the positive Perron eigenvector therefore make each weighted block normal. Absorbing its weight into the block gives a decomposition into normal blocks. The block-multiplicity and transfer-spectrum results then give \(r=1\), \(r(\mathcal E_{\widetilde U})=1\), and \(\operatorname {peripheral}(\mathcal E_{\widetilde U})=\{ 1\} \). Since the canonical blocks occupy the whole bond space,
Thus the unique normal block has ambient dimension \(D\). Its irreducibility, together with the spectral identities, makes \(\widetilde U\) normal.
Let \(d,D{\gt}0\). If an MPO tensor \(\mathcal U\) has a canonical-form-II presentation in the sense of Definition 18.8.8, then its normalized flattening \(\widetilde{\mathcal U}=d^{-1/2}\mathcal U\) is a normal tensor. This is the normality assertion of [ 16 , Proposition III.1 ] in the ambient convention (344).
The canonical-form-II presentation has normal blocks and full support. The shifted transfer traces give one block, transfer spectral radius one, and peripheral spectrum \(\{ 1\} \). The unique block has dimension \(D\) and makes \(\widetilde{\mathcal U}\) irreducible.
Let \(\mathcal U\) be an MPU in canonical form II with ambient fixed matrix \(\rho \), and put \(J=\max (D^2-1,1)\). Then
Let \(q:\{ 0,\ldots ,D{-}1\} \times \{ 0,\ldots ,D{-}1\} \to \{ 0,\ldots ,D^2{-}1\} \) be the standard product encoding, let \(R\) be the normalized physical diagonal of the double layer \(\mathcal W(\mathcal U)\), and let \(\rho ',\Phi '\) be the vectorizations of \(\rho \) and of \(\Phi =\mathbb {1}_D\) in the doubled bond coordinates \(\{ 0,\ldots ,D^2{-}1\} \), that is \(\rho '_{q(m,n)}=\rho _{mn}\) and \(\Phi '_{q(m,n)}=(\mathbb {1}_D)_{mn}\). Then also
The exponent is positive in every bond dimension, so no separate one-dimensional branch is needed.
If \(D=1\), the normalized transfer matrix is the identity, \(\rho =1\) by \(\operatorname{tr}(\rho )=1\), and both identities hold at \(J=1\). If \(D{\gt}1\), then \(J=D^2-1\), and Theorem 18.8.5 applied to the canonical-form-II data of the presentation produces a positive trace-one matrix \(\sigma \) with \((\Phi \rvert E=(\Phi \rvert \) and \(E^J=\lvert \sigma )(\Phi \rvert \). Since \(\rho \) is a fixed point of \(E\),
so \(\sigma =\rho \). For the double-layer form, Theorem 18.3.2 identifies the normalized diagonal of the \(J\)-fold block with the \(J\)-th power of the normalized transfer matrix after the encoding \(q\), so (353) gives, for all \(a,b\in \{ 0,\ldots ,D^2{-}1\} \),
which is (354).
Let \(\mathcal U\) be an MPU with physical dimension \(d{\gt}0\), and let \(E\) be the transfer matrix of its normalized flattening. Suppose that \(\rho \in M_{D}(\mathbb {C})\) is positive definite and diagonal and that, for some integer \(K\geq 0\),
Then \(\operatorname{tr}(\rho )=1\), and \(\mathcal U\) is in canonical form II in its original bond coordinates, with ambient right fixed matrix \(\rho \). This is the converse to the stabilized form of [ 16 , Proposition III.1 ] .
Write \(t=\operatorname{tr}(\rho )\) and \(P=\lvert \rho )(\Phi \rvert \). Then \(P^2=tP\) and \(\operatorname{tr}(P)=t\). If \(K\geq 2\), the normalized transfer trace at length \(K\) gives \(t=1\). If \(K=1\), lengths two and three give \(t^2=t^3=1\), hence \(t=1\). If \(K=0\), then \(P=\mathbb {1}_{D^2}\); its rank is at most one, so \(D=1\). In that dimension the normalized transfer matrix is the identity, and the first power also equals \(P\).
Thus there is a positive integer \(J\) with \(E^J=P\) and \(t=1\). Since \(E\) commutes with \(P\) and \(\operatorname{tr}(E^{J+1})=1\), the rank-one identity gives \(PEP=\operatorname{tr}(EP)P=P\), hence \(EP=PE=P\). Therefore \(\rho \) is fixed by the transfer map and its trace functional is fixed by the adjoint map, so the normalized flattening is left-canonical. Every fixed matrix \(X\) satisfies \(X=E^JX=\operatorname{tr}(X)\rho \). Positivity of \(\rho \) and this uniqueness imply irreducibility. The normalized transfer traces also give spectral radius one and primitivity. Taking the normalized flattening itself as the sole normal block gives the asserted canonical-form-II presentation.
18.9 Standard form, index, and symmetry classification
Let \(\widetilde{\mathcal U}=d^{-1/2}\mathcal U\) be the normalized flattening, and let \(E\) be its transfer matrix. A reduced full-support source datum for \(\mathcal U\), with physical dimension \(d{\gt}0\) and positive bond dimension, consists of an integer \(J{\gt}0\), a diagonal positive definite matrix \(\rho \) with \(\operatorname{tr}(\rho )=1\), and \((\Phi \rvert =\operatorname {vec}(\mathbb {1}_D)^{\mathsf T}\) such that
The one-dimensional case is supplied directly: if \(D=1\), take \(J=1\) and \(\rho =\mathbb {1}_1\) using Theorem 18.8.7. If \(D{\gt}1\), chosen canonical-form-II data with full support give a positive trace-one ambient fixed point with \(J=D^2-1\) by Theorem 18.8.5. Diagonality of this ambient fixed point is an additional hypothesis: the theorem gives a diagonal matrix in the unique block coordinates, but conjugation into the ambient coordinates need not preserve diagonality. For \(D{\gt}1\), this states the fixed-pair convention in [ 16 , equations labelled Erightleft and II_UTransfer, and proof of Proposition III.2(ii) ] . The \(D=1\) branch is the direct one-dimensional specialization. When \(\mathcal U\) is an MPU, Theorem 18.8.17 gives a canonical-form-II presentation of this same tensor whose ambient fixed matrix is the supplied \(\rho \); it makes no assertion about continuous choices along a path.
Let \(M_i=X_iY_i\) be supplied source factorizations for \(\mathcal U\) and the weight \(\rho \). For retained physical pairs \(p=(p_1,p_2)\) and \(q=(q_1,q_2)\), one has
The \(p\) entries are starred and the \(q\) entries are unstarred. This is precisely the staggered reflected–direct four-tensor expression obtained from \(u=Y_2\mathbin {-}Y_1\) and the two identities in [ 16 , equations X1X2b and uUnitary ] .
Since the first cut has rows \((i,\beta )\) and columns \((\alpha ,j)\), its weighted normalization gives
The unweighted normalization of the second cut gives
Expand both copies of \(u_{(l,r),(i_1,i_2)}=\sum _\alpha (Y_2)_{l,(i_1,\alpha )}(Y_1)_{r,(\alpha ,i_2)}\) and substitute these two Gram identities. Reordering the finite sums yields the stated formula.
Let \(\mathcal U\) be an MPO tensor, let \(\rho \) be a bond matrix, and let \(M_i=X_iY_i\) be supplied source factorizations for \(\mathcal U\) and \(\rho \). Construct the source tensor \(u=Y_2\mathbin {-}Y_1\). For retained physical pairs \(p=(p_1,p_2)\) and \(q=(q_1,q_2)\), let \(W^{ij}\) denote the \((i,j)\) double-layer letter, let \(\lvert \rho ^{\mathsf T})\) be the column-stacking vector of \(\rho ^{\mathsf T}\), and set \((\Phi \rvert =\operatorname {vec}(\mathbb {1}_D)^{\mathsf T}\). Then
Thus the fixed-pair weight is genuinely transposed at this stage. In the diagonal canonical-form-II coordinates fixed above, \(\rho ^{\mathsf T}=\rho \); this is the identification used in the complete contraction below.
Enumerate each doubled-bond coordinate as \(\operatorname {flat}(\alpha ,\alpha ')\). Expanding a diagonal entry of the matrix under the trace gives
Since \((\rho ^{\mathsf T})_{\beta ',\beta }=\rho _{\beta ,\beta '}\), summing over \(\alpha ,\alpha '\) gives the identity in Theorem 18.9.2.
Let \(\mathcal U\) be an MPO tensor with physical dimension \(d{\gt}0\), let \(W\) be its double layer, and put \(E=d^{-1}\sum _iW^{ii}\). Let \(\rho \) be symmetric, set \((\Phi \rvert =\operatorname {vec}(\mathbb {1}_D)^{\mathsf T}\), and suppose that for some \(K\geq 0\),
For supplied source factors built from the same weight \(\rho \), the paper gate \(u=Y_2\mathbin {-}Y_1\) satisfies
If \(\rho \) is diagonal, the same quantity is
Thus only the \(K\)-site interior is blocked; the two endpoint letters remain one-site tensors. The \(p\) entries are conjugated and the \(q\) entries are not. This is the supplied-fixed-pair contraction in [ 16 , Lemma III.7 ] .
Let \(\mathcal U\) be an MPU tensor with physical dimension \(d{\gt}0\) and bond dimension \(D{\gt}0\). Let \(\rho {\gt}0\) be diagonal with \(\operatorname{tr}(\rho )=1\), and put \((\Phi \rvert =\operatorname {vec}(\mathbb {1}_D)^{\mathsf T}\). Suppose that for some \(J{\gt}0\) the normalized transfer matrix satisfies
Construct the source factors and \(u\) from \(\mathcal U\) using \(\rho \), and set \(K=JD^2\). For retained physical pairs \(p,q\in \{ 0,\ldots ,d-1\} ^2\), the complete source-\(u\) contraction satisfies
Here \(\tau \) ranges over input words of length \(K\), and \(\eta \) ranges over output words of length \(K+2\). This is the supplied-fixed-pair form of the complete-network equality in [ 16 , Lemma III.7 ] .
Set \(K=JD^2\). Trace normalization makes the supplied rank-one transfer matrix idempotent, and the normalized blocked-transfer identity therefore gives
Diagonality gives \(\rho ^{\mathsf T}=\rho \), so Theorem 18.9.4 applies at this \(K\) and yields the displayed normalized input-tail sum.
Let \(\rho {\gt}0\), and compute both source cuts, the source operator \(v\), and the right source factors \(Y_1,Y_2\) from the same tensor \(\mathcal U\) using \(\rho \). Let \(W\) be the double layer of \(\mathcal U\), let \(\lvert \rho ^{\mathsf T})\) be the column-stacking vector of \(\rho ^{\mathsf T}\), and let \((\Phi \rvert =\operatorname {vec}(\mathbb {1}_D)^{\mathsf T}\). For the starred physical pair \(p=(p_1,p_2)\), the unstarred pair \(q=(q_1,q_2)\), and virtual paths \(a=(a_1,a_2)\) and \(b=(b_1,b_2)\), put \(x=((a_1,p_1),(p_2,a_2))\) and \(y=((b_1,q_1),(q_2,b_2))\). Then
Consequently the dressed Gram equation
holds if and only if
for all \(i,j,k,\ell \). The source gate and source factors use the same weight \(\rho \) throughout. The transpose occurs only in the inserted column-stacking vector. In the source, \(\rho \) is diagonal, so this vector equals \(\lvert \rho )\) and the displayed equivalence is exactly [ 16 , equation vUnitary and proof of Theorem III.8 ] .
Regrouping gives \((Y_1\otimes Y_2)^\dagger v^\dagger v(Y_1\otimes Y_2) =\bigl(v(Y_1\otimes Y_2)\bigr)^\dagger v(Y_1\otimes Y_2)\), and Theorem 18.4.66 closes each factor by the two source-cut factorizations:
Summing the conjugate of this expression against the corresponding expression for \(y\) over \(z\) and reordering the finite sums gives the ordinary two-letter entry of Theorem 18.4.65, which proves (373). For (374), the same theorem expands the Gram entry of \(Y_1\otimes Y_2\) with the weight \(\rho _{\beta \beta '}\) attached to the starred index \(\beta \), and expands the inserted entry with \((\rho ^{\mathsf T})_{\alpha '\alpha }=\rho _{\alpha \alpha '}\) attached to the starred index \(\alpha \); the two finite sums agree after reordering. Both directions of the equivalence compare the two entry identities at every \(x\) and \(y\). The network is kept combined, and neither source cut is contracted separately.
Let \(\mathcal U\) be simple and in canonical form II, with ambient fixed matrix \(\rho \). Let \(v\) be the source operator of \(\mathcal U\) built from that same weight \(\rho \). Then \(v^\dagger v=\mathbb {1}_{r\ell }\), and consequently \(r\ell \le d^2\). This is the implication \(1\to 2\) in [ 16 , proof of Theorem III.8 ] , before the standing isometry of \(u\) is used.
Theorem 19.5.6 gives the insertion identity for the recorded canonical boundaries: \(W^{ij}W^{k\ell }=W^{ij}\lvert \rho )(\Phi \rvert W^{k\ell }\). Since \(\rho \) is diagonal, \(\rho ^{\mathsf T}=\rho \), so Theorem 18.9.6 gives the dressed Gram equation for the factors built from the same weight \(\rho \). Then Theorem 18.4.70 cancels the dressing. Since \(v^\dagger v=\mathbb {1}\) on \(\mathbb {C}^r\otimes \mathbb {C}^\ell \), the map \(v\) is injective, so \(r\ell \le d^2\).
Let \(\mathcal U\) be an MPU in canonical form II, with recorded weight \(\rho \). If \(p{\gt}0\) and \(\mathcal U^{[p]}\) is simple, then the source operator \(v\) computed from the source cuts of \(\mathcal U^{[p]}\), using this same \(\rho \), satisfies \(v^\dagger v=\mathbb {1}\). In particular, some integer \(1\leq p\leq D^2\) gives a simple blocked tensor and this source-\(v\) isometry. The statement includes \(D=1\).
The blocked tensor retains canonical form II with the same recorded matrix \(\rho \). The source-\(v\) contraction for a simple tensor therefore applies to its own source cuts and gives the isometry. The blocking length \(D^2\) is simple for every MPU, including in bond dimension one.
Let \(\mathcal U\) be an MPU tensor, let \(\rho {\gt}0\), and let \(v\) be its source operator built from \(\rho \). If \(v^\dagger v=\mathbb {1}_{r\ell }\), then \(\mathcal U\) is simple, with witnesses \((\Phi \rvert \) and \(\lvert \rho ^{\mathsf T})\). This is the implication \(4\to 1\) in [ 16 , proof of Theorem III.8 ] .
By Theorem 18.4.70, \(v^\dagger v=\mathbb {1}\) gives the dressed Gram equation, and Theorem 18.9.6 turns it into \(W^{ij}W^{k\ell }=W^{ij}\lvert \rho ^{\mathsf T})(\Phi \rvert W^{k\ell }\). The same-witness implication in Theorem 18.3.28 supplies \((\Phi \rvert W^{ij}\lvert \rho ^{\mathsf T})=\delta _{ij}\) from unitarity, so both simple contractions hold.
For any MPU tensor \(\mathcal U\) under the source’s standing canonical-form-II convention, let \(r\) and \(\ell \) be the two source-cut ranks and let \(u\) be the source operator. Then
Consequently \(u\) is an isometry and \(r\ell \geq d^2\). This is the unrestricted statement of [ 16 , Lemma III.7 ] .
The convention records a positive diagonal ambient weight \(\rho \) and, by Theorem 18.8.16, the stabilized power \(E^J=\lvert \rho )(\Phi \rvert \) at the positive exponent \(J=\max (D^2-1,1)\). Lemma 18.9.11, applied to the source factors built from that same weight, gives \(u^\dagger u=\mathbb {1}\) and \(d^2\le r\ell \).
Let \(\mathcal U\) be an MPU tensor with physical dimension \(d{\gt}0\). Let \(W\) be its double layer, put \(E=d^{-1}\sum _iW^{ii}\), and let \(\rho {\gt}0\) be diagonal. Put \((\Phi \rvert =\operatorname {vec}(\mathbb {1}_D)^{\mathsf T}\) and suppose that for some \(K\geq 0\),
Let \(r\) and \(\ell \) be the source-cut ranks, and construct the compact-SVD source factors and \(u\) from \(\mathcal U\) using \(\rho \). Then
Thus the compact-SVD paper gate is an isometry. This is the supplied-fixed-pair version of [ 16 , Lemma III.7 ] .
The retained-interior identity and input-first MPU unitarity give, for all physical pairs \(p,q\),
Hence \(u^\dagger u=\mathbb {1}\). Since \(u\) maps a space of dimension \(d^2\) isometrically into one of dimension \(r\ell \), one also has \(d^2\leq r\ell \).
Let \(\mathcal U\) be an MPU tensor under the source’s standing canonical-form-II convention. Let \(r\) and \(\ell \) be its source-cut ranks, and let \(u\) and \(v\) be its source operators, both built from the ambient weight \(\rho \) recorded by the convention. Then the following conditions are equivalent:
\(\mathcal U\) is simple;
\(r\ell =d^2\);
\(u\) is unitary;
\(v\) is unitary.
This is the unrestricted statement of [ 16 , Theorem III.8 ] .
The convention gives \(u^\dagger u=\mathbb {1}\) and \(d^2\leq r\ell \) before any of the four conditions is assumed. Follow the cycle \(1\to 2\to 3\to 4\to 1\).
If \(\mathcal U\) is simple, the source-\(v\) contraction for the same weight \(\rho \) gives \(v^\dagger v=\mathbb {1}\), hence \(r\ell \leq d^2\) and therefore \(r\ell =d^2\). Conversely, this equality makes the standing isometry \(u\) square, hence unitary. The two-site factorization gives
Reindexing preserves unitarity. Since \(U^{(2)}\) and \(u\) are unitary, cancellation makes \(v\) unitary. Finally, \(v^\dagger v=\mathbb {1}\) gives the second simple contraction, while the MPU identity gives the first, so \(\mathcal U\) is simple.
Let \(\mathcal U\) be a simple tensor under the source’s standing canonical-form-II convention. Its standard form is the depth-two form of the two-site block \(\mathcal U_2\) determined by the source unitaries
On four consecutive blocked legs its unitary is
This is the unrestricted definition of [ 16 , Definition III.9 ] .
Let \(d,D,\ell ,r\) be positive integers and let \(W\) be a two-site tensor of physical dimension \(d^2\) and bond dimension \(D\). A standard form with supplied gates consists of unitary maps
and half factors \(X_1,X_2\) such that
This is the open contraction underlying [ 16 , Definition III.9 ] . No unitary periodic operator is assumed for \(W\).
 \(=\)

Let \(N{\gt}0\). Write each physical output and input label as an ordered pair \(i_x=(i_{x,1},i_{x,2})\) and \(j_x=(j_{x,1},j_{x,2})\), and each intermediate label as \(h_x=(h_{x,1},h_{x,2})\in \{ 0,\ldots ,\ell -1\} \times \{ 0,\ldots ,r-1\} \). Indices \(x\) are taken modulo \(N\). Define the unshifted and shifted layer matrices by
The cyclic relabeling of pairs is \(h\mapsto \bigl((h_{x,2},h_{x+1,1})\bigr)_x\), with inverse \(q\mapsto \bigl((q_{x-1,2},q_{x,1})\bigr)_x\). The alphabet of the two-site tensor is identified with ordered pairs \((i_{x,1},i_{x,2})\). This is the ordering in [ 16 , Equation StandardForm ] .
If the supplied gates \(u\) and \(v\) are unitary between their stated coordinate spaces, then for every \(N{\gt}0\) both \(C_{u,N}\) and \(C_{v,N}\) are unitary between their corresponding configuration spaces.
The two Gram matrices of the product of a rectangular gate factor sitewise: for example,
The reverse Gram identity is analogous. The shifted layer is the product of \(v\) on relabeled configurations, and the cyclic relabeling preserves both Gram identities.
Let \(W\) have supplied two-site standard-form data \((u,v,X_1,X_2)\). For every \(N{\gt}0\) and pair configurations \(i,j\),
Thus, after the stated identification of pair configurations with the two-site alphabet, \(U^{(N)}(W)=C_{v,N}C_{u,N}\). This includes \(N=1\). The formula is the positive-length closed contraction of the supplied open form in [ 16 , Equations uuvv and StandardForm ] .
Expand the periodic trace as a sum over closed bond configurations. Insert the supplied \(X_2\)–\(u\)–\(X_1\) expression at each site. For each \(x\), the bond label between sites \(x\) and \(x+1\) contracts \((X_1)_{(i_{x,2},\beta ),h_{x,2}}\) with \((X_2)_{(\beta ,i_{x+1,1}),h_{x+1,1}}\); their sum is precisely \(v_{(i_{x,2},i_{x+1,1}),(h_{x,2},h_{x+1,1})}\). The remaining factors form \(C_{u,N}\), giving the displayed matrix product in its stated order.
If \(W\) has supplied two-site standard-form data, then
for every \(N{\gt}0\). In particular, \(W\) is an MPU under the source’s \(N{\gt}1\) length convention.
The periodic operator is the product \(C_{v,N}C_{u,N}\) of two unitary layers, and the physical-pair identification preserves unitarity.
For a two-site tensor \(W\) with supplied standard-form data, write \(L(i)_{\alpha t}=X_2(\alpha ,i_1)_t\), \(R(i)_{s\gamma }=X_1(i_2,\gamma )_s\), \(u(j)_{ts}=u_{(t,s),j}\), and \(v(i,i')_{st}=v_{(i_2,i'_1),(s,t)}\). For every nonempty word of complete two-site blocks, with the product ordered in increasing \(x\),
The equality is an equality of matrices with both virtual indices free; arbitrary matrices may therefore be inserted at the two ends before taking the trace.
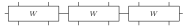 \(=\)
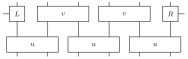
A single letter factors as \(W^{i,j}=L(i)u(j)R(i)\). For adjacent letters, \(R(i)L(i')=v(i,i')\) by the definition of the shifted gate. Induction over the remaining letters gives the displayed product. Multiplying it by the two end matrices and taking the trace preserves the equality.
Let \(W\) have supplied two-site standard-form data. Fix virtual indices \(\alpha ,\gamma \), exterior output half-sites \(e_-,e_+\), and exterior input pairs \(j_0,j_2\). For two neighboring output pairs \(a=(a_0,a_1)\), \(b=(b_0,b_1)\) and a middle input pair \(j\), set
For an observable \(A\) on the middle input pair, let \(C=uAu^{\dagger }\) and define the matrix on the two neighboring output pairs by
The link coordinates are ordered as \((r,\ell ,r,\ell )\). For arbitrary virtual matrices \(P,Q\) and complete-block word pairs \((\sigma ^{L},\tau ^{L})\) and \((\sigma ^{R},\tau ^{R})\), set
where \(W^{\sigma ,\tau }\) denotes word evaluation. These are finite contractions of [ 16 , Equations uuvv and StandardForm ] .
For every supplied two-site standard form and every observable \(A\) on the middle input pair,
for every choice of \(\alpha ,\gamma ,e_-,e_+,j_0,j_2\). In particular, neither virtual end is closed in this identity, and \(B(A)\) acts only on the four output half-sites forming the two neighboring pairs.
The two internal contractions \(X_1X_2\) give one \(v\) gate on each neighboring output pair. Thus, for suitable exterior factors \(L,R\),
where \(L\) and \(R\) retain the exterior half factors and input gates. Since \(u\) and \(v\) are unitary between their stated spaces, \(uA=(uAu^{\dagger })u\) and \((v\otimes v)\widetilde C=B(A)(v\otimes v)\). Inserting these two identities into the displayed contraction proves the matrix equality without a virtual trace.
Replace the open word in \(F_{\alpha ,\gamma }\) by its virtual trace with arbitrary matrices \(P,Q\) at the left and right ends. The resulting matrix \(F_{P,Q}\) obeys
The same conclusion holds when \(P\) and \(Q\) are the matrix products of arbitrary complete-block prefix and suffix words, respectively. Their physical row and column words remain explicit and may have different lengths on the two sides of the three-block window.
If \(E\) is the open three-letter word, cyclicity of the virtual trace gives
The open identity therefore survives this linear combination. For complete-block prefix and suffix words, apply word concatenation twice to identify their product with \(PEQ\), leaving both factors intact.
Let \(\mathcal U\) be a matrix product unitary in full-support canonical form II, with bond dimension \(D\) and physical dimension \(d\). Its normalized flattening \(A^{ij}=d^{-1/2}U^{ij}\) is left-canonical:
This is the ambient normalization implicit in [ 16 , lines 269–281 and 344–356 ] .
The normalized transfer traces satisfy \(\operatorname{tr}(E^N)=1\) for \(N{\gt}1\). Hence the canonical form has one retained block \(B\), with coefficient \(\mu \) satisfying \(|\mu |^2=1\). Let \(W\) be its inclusion into the ambient bond space. Full support gives \(W^\dagger W=\mathbb {1}\) and \(WW^\dagger =\mathbb {1}\), while the reconstruction gives \(A^{ij}W=W(\mu B^{ij})\). Therefore
Let \(\mathcal U\) and \(\mathcal V\) be matrix product unitaries on the same physical space, each in full-support canonical form II, with bond dimensions \(D_{\mathcal U}\) and \(D_{\mathcal V}\). Suppose that their periodic operators agree at every length \(N{\gt}1\):
Then \(D_{\mathcal U}=D_{\mathcal V}\), and, after identifying their bond spaces by this equality, there is a unitary \(z\in \mathrm U(D_{\mathcal V})\) such that, for every \(i,j\),
This is the virtual-bond implication underlying the local relation in [ 16 , Equations (SFuu) and (SFvv), lines 624–652 ] . The full-support convention is recorded in [ 58 ] .
Write \(A_{\mathcal U}^{ij}=d^{-1/2}U^{ij}\) and \(A_{\mathcal V}^{ij}=d^{-1/2}V^{ij}\). Both are normal tensors. Equality of periodic operators for \(N{\gt}1\) makes their matrix product vectors equal at these lengths. The normal-tensor phase alternative gives a unit scalar \(a\) such that
at every positive length. At \(N=2,3\) the normalized states are nonzero, so the given equality yields \(a^2=a^3=1\), hence \(a=1\). Gauge recovery for normal tensors now gives equal bond dimensions and an invertible \(X\) and nonzero scalar \(\zeta \) satisfying \(A_{\mathcal V}^{ij}=\zeta XA_{\mathcal U}^{ij}X^{-1}\). Applying this relation to lengths two and three, where the common states are nonzero, gives \(\zeta ^2=\zeta ^3=1\), so \(\zeta =1\). Theorem 18.9.23 makes both tensors left-canonical, so the irreducible unitary-gauge theorem replaces \(X\) by a unitary \(z\). Cancelling the common factor \(d^{-1/2}\) gives the asserted relation for \(U^{ij}\) and \(V^{ij}\).
Let \(\mathcal U\) be simple and have a reduced full-support canonical-form-II presentation with positive diagonal fixed matrix \(\rho \). The two-site tensor \(\mathcal U_2\) has the supplied standard form with the source gates \(u,v\) and the source half factors \(X_1,X_2\). In particular,
The full-support restriction is recorded in [ 58 ] .
The source-cut factorization gives the open contraction of \(\mathcal U_2\) through \(X_2,u,X_1\), while the definition of \(v\) gives its \(X_1,X_2\) contraction. The simple-tensor equivalence makes both source gates unitary. Its rank identity \(r\ell =d^2\) also makes the two intermediate dimensions positive.
Let \(\mathcal U\) be simple and have a reduced full-support canonical-form-II presentation with positive diagonal fixed matrix \(\rho \). Let \(u\) and \(v\) be its source gates. For \(N{\gt}0\), flatten each pair configuration by the bijection \(\Phi _N\) given by
Then the original chain of \(2N\) sites satisfies
In particular, numbering four original sites from \(1\) to \(4\) gives
Apply the supplied circuit identity to the two-site block of \(\mathcal U\). The two physical-blocking identities identify its length-\(N\) periodic operator with \(U^{(2N)}(\mathcal U)\) under \(\Phi _N\). For \(N=2\), the two shifted pairs are \((2,3)\) and \((4,1)\).
Let \(\mathcal U\) have a reduced full-support canonical-form-II presentation. There is an integer \(k\) with \(0{\lt}k\leq D^2\) such that \(\mathcal U^{[k]}\) is simple and its two-site block has the open source standard form of Definition 18.9.25. If \(\eta _{d,k}\) identifies a word of length \(2k\) with two consecutive words of length \(k\), the corresponding physical relabeling satisfies
The source cuts and both gates are formed on the same tensor \(\mathcal U^{[k]}\), using the fixed matrix of the given presentation.
Choose the simple blocking length \(k=D^2\). Canonical form II persists under this positive blocking, with the same fixed matrix, so Definition 18.9.25 applies to \(\mathcal U^{[k]}\). Two-site blocking is direct blocking by \(2k\) after the displayed relabeling: first identify the ordinary two-site block with length-two blocking, then group the direct word into consecutive length-\(k\) subwords and use \(k\cdot 2=2k\).
Let \(U\) be any MPO tensor, let \(k,p,m,s\in \mathbb N\), and write \(W=(U^{[k]})_2\). For a word \(\sigma \) of \(m\) blocks of length \(2k\), let \(\eta \sigma \) relabel each block as two consecutive words of length \(k\); use the same convention for \(\tau \). If \(i^-,j^-\) are words of length \(p\) and \(i^+,j^+\) are words of length \(s\), then
Both residual products remain present, including when \(m=0\); no unitarity, canonical form, or divisibility of the total length is assumed.
Residual-site blocking gives the trace with middle factor \((U^{[2k]})^{\sigma ,\tau }\). The two-site relabeling identifies this factor, letter by letter and in the same order, with \(W^{\eta \sigma ,\eta \tau }\); the prefix and suffix products are unchanged.
Suppose \(W=(U^{[k]})_2\) has supplied two-site standard-form data. Let three consecutive blocks of length \(2k\) lie between an arbitrary original-site prefix of length \(p\) and suffix of length \(s\). Under the two-site relabeling, suppose their output labels are \((e_-,a_0),(a_1,b_0),(b_1,e_+)\) and their input labels are \(j_0,j,j_2\). Let \(P=U^{i^-,j^-}\) and \(Q=U^{i^+,j^+}\) be the residual products. The corresponding entry of the original length-\(p+6k+s\) MPO is
The equality holds for every choice of the residual words and window labels; no unitarity or MPU hypothesis on \(U\) is required.
Apply the residual-word identity to the three middle blocks. Their relabeled words are precisely the three displayed letters, so the middle product is the one defining \(F_{P,Q}\).
Suppose \(W=(U^{[k]})_2\) has supplied two-site standard-form data. Let \(i^-,j^-\) be original-site words of length \(p\) and \(i^+,j^+\) original-site words of length \(s\). Let \((\sigma ^{L},\tau ^{L})\) and \((\sigma ^{R},\tau ^{R})\) be complete-block word pairs, with \(|\sigma ^{L}|=|\tau ^{L}|\). For each choice of the window labels \(a,b,j\), let \(\sigma (a,b)\) and \(\tau (j)\) be words of \(m\) blocks of length \(2k\) whose relabelings in the sense of the residual-word identity are
Put
Then the original-chain coefficient matrix \(F^U\) satisfies
Both equalities are finite-chain identities with every exterior physical label fixed; the virtual boundary is not discarded.
The residual-word identity first leaves both original-site products in the trace. Two word concatenations split the relabeled middle product into the left complete-block word, the three window letters, and the right complete-block word, yielding (423) entrywise with \(P\) and \(Q\) the displayed end products. Applying the arbitrary-virtual-end three-block identity to these two matrices yields (424).
Let \(W=(U^{[k]})_2\) have supplied two-site standard-form data. For arbitrary original-site prefix and suffix word pairs, put \(P=U^{i^-,j^-}\) and \(Q=U^{i^+,j^+}\). The three-block coefficient contracted against these end matrices satisfies
Thus the local observable on the two neighboring output pairs is independent of both residual words.
Apply the virtual-end identity with the stated word products as its two end matrices.
Let \(\mathcal U\) and \(\mathcal V\) be simple tensors written in standard form, with source unitaries \((u_{\mathcal U},v_{\mathcal U})\) and \((u_{\mathcal V},v_{\mathcal V})\). They generate the same MPU for every \(N\),
if and only if their standard forms are related by the local unitary gauges of [ 16 , Eqns. (SFuu) and (SFvv) ] : there are unitaries \(x\), \(y\), and \(z\) on the three corresponding source and canonical-form-II legs. In particular, the source unitaries obey the local relation
while the two canonical-form-II tensors are related on their virtual leg by \(z\) and on their source legs by \(x\) and \(y\). This records the source’s unblocked all-length wording. Its converse has the odd-length parity obstruction of Theorem 18.9.38; the blocked-family interpretation is distinguished in [ 157 ] . The correct form of this theorem is Theorem 18.9.33 together with Theorems 18.9.34 and 18.9.35: equality of the operators at every length is equivalent to a unitary conjugation of the letters, the gate relations follow from it, and the gate relations give equality of the operators on rings of even length only.
Let \(\mathcal U\) and \(\mathcal V\) be tensors in canonical form II with bond dimensions \(D_1\) and \(D_2\). Then \(U^{(N)}=V^{(N)}\) for every \(N\ge 2\) if and only if \(D_1=D_2\) and there is a unitary \(z\) on \(\mathbb C^{D_1}\) with \(V^{ij}=zU^{ij}z^\dagger \) for all \(i,j\).
The forward direction is the unitary virtual gauge obtained from equal operators. For the converse, conjugating every letter by \(z\) leaves each trace \(\operatorname {tr}(V^{i_1j_1}\cdots V^{i_Nj_N})\) unchanged.
Let \(\mathcal U\) and \(\mathcal V\) be simple tensors in canonical form II of the same bond dimension with \(U^{(N)}=V^{(N)}\) for every \(N\ge 2\). Then \(\mathcal V=z\, \mathcal U\, z^\dagger \) letterwise for a unitary \(z\), the source ranks of the two tensors agree, and after identifying the rank spaces there are unitaries \(x\) on \(\mathbb C^{\ell }\) and \(y\) on \(\mathbb C^{r}\) with \(u_{\mathcal V}=(x\otimes y)u_{\mathcal U}\) and \(v_{\mathcal V}=v_{\mathcal U}(y^\dagger \otimes x^\dagger )\), the gates being those of the selected factorizations.
Theorem 18.9.33 gives \(z\); the selected source gates of a unitary virtual conjugate are related to the transported gates by unitaries on the two rank spaces.
Let \(\mathcal U\) and \(\mathcal V\) be simple tensors in canonical form II of the same bond dimension whose selected source gates satisfy, after an identification of the rank spaces, \(u_{\mathcal V}=(x\otimes y)u_{\mathcal U}\) and \(v_{\mathcal V}=v_{\mathcal U}(y^\dagger \otimes x^\dagger )\) for unitaries \(x\), \(y\). Then \(U^{(2N)}=V^{(2N)}\) for every \(N\ge 1\). The same holds for any two tensors carrying two-site standard-form data with gates so related on the same internal legs.
Write both operators as the two-layer circuit of the standard form. In the circuit of \(\mathcal V\) the unitary placed on the internal leg of each site by the layer of \(u\) meets its adjoint placed there by the layer of \(v\), so the circuits coincide. The relabelling of the rank spaces is transported through the standard-form data.
For any tensor \(\mathcal U\) and scalar \(c\in \mathbb C\), \((c\mathcal U)^\sharp =\overline c\, \mathcal U^\sharp \). If \(\overline c c=1\), the double layers of \(c\mathcal U\) and \(\mathcal U\) agree.
Conjugation sends \(c\) to \(\overline c\), and contracting the two layers multiplies their scalars to \(\overline c c=1\).
For every physical dimension \(d\), the bond-one identity tensor \(\mathcal I^{ij}=\delta _{ij}\) is simple.
Its double-layer letters are \(\delta _{ij}\), so both simplicity identities hold with boundary vectors \(a=b=1\).
There are simple matrix product unitaries \(\mathcal U,\mathcal V\) of physical dimension two and bond dimension one whose two-site blocked tensors agree, but whose periodic operators differ at length three:
This is the parity obstruction to reading the converse of [ 16 , Theorem FundamentalMPU, lines 624–648 ] as an assertion about the original tensors at every length. Definition SF of that source concerns the two-site blocks; the explicit source factors and local unitary relations for this example are recorded in [ 157 ] .
Let \(\mathcal U^{ij}=\delta _{ij}\) on its one-dimensional bond space and set \(\mathcal V^{ij}=-\mathcal U^{ij}\). Their double-layer letters are both \(\delta _{ij}\), so the simplicity contractions hold with unit boundary vectors. Two-site blocking removes the pair of minus signs, whereas closing a chain of length three leaves one minus sign:
The two tensors of the parity obstruction are in canonical form II with \(\rho =1\), and have cut matrices \(\pm I_2\) and ranks \(r=\ell =2\). With the factors \(X_1=X_2=I\), \(Y_1=Y_2=Z_1=Z_2=I\) for the identity tensor and \(X_1=X_2=I\), \(Y_1=Y_2=Z_1=Z_2=-I\) for its negative, both satisfying the six factor identities with \(\rho =1\), the gates \(u\) and \(v\) computed from the factors are the same for both tensors: \(u_{(l,r),(i_1i_2)}=\delta _{li_1}\delta _{ri_2}\) and \(v_{(j_1j_2),(r,l)}=\delta _{j_1r}\delta _{j_2l}\).
With bond dimension one the gate formulas \(u=Y_2Y_1\) and \(v=X_1X_2\) have one term each, and \((-I)(-I)=I\).
The source-labelled Fundamental Theorem above remains unformalized. The source’s displayed standard forms concern \(\mathcal U_2,\mathcal V_2\); their local relations can control the blocked families, but do not distinguish the original families at odd lengths. The explicit local-gauge calculation and the possible corrected scopes are given in [ 157 ] . No odd-length premise has been inserted into the source-labelled statement.
Let \(A\) and \(B\) be finite matrices over a field. Then
Identify the image of the Kronecker product with the tensor product of the two images and multiply their dimensions.
For a specified tensor \(\mathcal U\) whose right and left source-cut ranks \(r\) and \(\ell \) are positive, define
This definition makes no choice of a simple blocking.
A specified tensor with equal positive source ranks \(r_{\mathcal U}=\ell _{\mathcal U}\) has \(\operatorname {ind}_{\mathrm{src}}(\mathcal U)=0\). Let \(\mathcal U\) and \(\mathcal V\) be specified tensors. Suppose that their source ranks obey
where \(c\), \(r_{\mathcal U}\), and \(\ell _{\mathcal U}\) are positive. Then
Let \(\mathcal U\), \(\mathcal V\), and \(\mathcal W\) instead have positive source ranks and suppose that
where \(c\) is a positive integer. Then
If \(d\), \(r_{\mathcal U}\), and \(\ell _{\mathcal U}\) are positive and a specified tensor has \(r_{\mathcal U}\ell _{\mathcal U}=d^2\), then
Expand the definition. Equal ranks give a vanishing difference of logarithms. For common scaling, apply \(\log _2(cx)=\log _2c+\log _2x\) to both ranks and cancel the two copies of \(\log _2c\). For the three-tensor identity, apply the product formula twice to each rank and cancel the common term. For the equivalent formulas, apply the same product identity to \(r_{\mathcal U}\ell _{\mathcal U}=d^2\) and use \(\log _2(x/y)=\log _2x-\log _2y\).
If \(\mathcal U\) and \(\mathcal V\) have positive right and left source ranks, then
This is the specified-tensor form of the tensoring case of [ 16 , Theorem IV.6(ii) ] ; it makes no choice of a simple blocking.
Both source ranks are multiplicative, so the logarithms add.
Let \(d{\gt}0\) and \(k_0\leq k\). Suppose that the endpoint source ranks satisfy
Then the specified source-index values agree:
This statement assumes the endpoint products; it neither selects a simple blocking nor defines the public index.
Exact blocking growth gives the common positive factor \(d^{k-k_0}\):
Its logarithm occurs once in each rank term and therefore cancels from their difference.
Let \(\mathcal U\) be a tensor in canonical form generating matrix product unitaries, let \(k\geq 1\) be any blocking length for which \(\mathcal U_k\) is simple, and let \(r\) and \(\ell \) be its right and left source-cut ranks. The source index is
Since \(r\ell =d^{2k}\), this is equivalently
This is the definition of [ 16 , Definition IV.1 ] , stated there for a tensor in canonical form with the ranks of its simple blocking, after the source has assumed without loss of generality that the tensor is in canonical form II (lines 294 and 356). The index of every matrix product unitary is taken through a canonical-form-II representative; for a tensor in canonical form this value is the displayed expression in the ranks of its own blocking, since these ranks are invariant under the similarity to canonical form II.
Let \(\mathcal U\) be an MPU in canonical form II. Choose any positive blocking length \(k\) for which \(\mathcal U_k\) is simple, and let \(r_k\) and \(\ell _k\) be its right and left source-cut ranks. Such a blocking exists, and both ranks are positive. Define
Since \(r_k\ell _k=d^{2k}\), one also has
This is the canonical-form-II representative case of [ 16 , Definition IV.1 ] .
Let \(U\) and \(V\) be full-support canonical-form-II tensors on the same physical space, possibly with different bond dimensions. If \(U^{(N)}=V^{(N)}\) for every \(N{\gt}1\), then their right and left source-cut ranks agree, and \(\operatorname {ind}(U)=\operatorname {ind}(V)\). This is a comparison of canonical representatives in the setting of [ 16 , Definition IV.1 and Proposition IV.2 ] .
Equality of the periodic operators gives a unitary virtual similarity, which preserves both source-cut ranks. Choose a common positive simple blocking length \(k\) for \(U\) and \(V\). The periodic operators of the \(k\)-site blocks agree, so the ranks \(r_k\) and \(\ell _k\) of these blocks satisfy \(r_k(U)=r_k(V)\) and \(\ell _k(U)=\ell _k(V)\). Hence
Let \(d,D{\gt}0\), and let \(U\) be an MPU tensor. Choose a reduced canonical-form-II representative \(U_{\mathrm{red}}\) with \(U_{\mathrm{red}}^{(N)}=U^{(N)}\) for every \(N{\gt}0\), and set
The definition does not identify the source-cut ranks of \(U\) itself with those of \(U_{\mathrm{red}}\).
Every canonical-form-II representative with the same positive-length periodic operators as \(U\) has index \(\operatorname {ind}(U)\). In particular, positive-dimensional MPU tensors \(U,V\) with \(U^{(N)}=V^{(N)}\) for all \(N{\gt}1\) have equal indices, even when their bond dimensions differ.
Choose reduced canonical-form-II representatives of \(U\) and \(V\). Their periodic operators agree for \(N{\gt}1\), so their canonical source indices agree by Theorem 18.9.48.
Let \(d{\gt}0\) and let \(\mathcal U\) be an injective MPU tensor of bond dimension \(D\). There are a canonical-form-II tensor \(\mathcal V\) of the same bond dimension and an invertible matrix \(X\) such that, for every \(N{\gt}0\),
This combines the canonical replacement in [ 16 , lines 319–356 ] with the equality case of [ 221 , Proposition 20 ] .
Choose a reduced canonical representative of bond dimension \(E\leq D\). Equality of the positive-length periodic operators identifies the doubled-index matrix product vectors. Since \(\mathcal U\) is injective, there are \(P\in \mathbb {C}^{D\times E}\) and \(Q\in \mathbb {C}^{E\times D}\) with \(PQ=I_D\) and \(P\mathcal V^{ij}Q=\mathcal U^{ij}\). Thus \(D\leq E\), and hence \(D=E\). For square matrices, \(PQ=I\) also gives \(QP=I\). Multiplying the letter identity by \(Q\) and \(P\) yields \(\mathcal V^{ij}=Q\mathcal U^{ij}P\), as required with \(X=Q\).
Let \(d{\gt}0\) and let \(\mathcal U\) be a simple injective MPU tensor. Its source-cut ranks \(r\) and \(\ell \) satisfy
These are the rank-product and index identities of [ 16 , lines 562–573 and 681–704 ] , for the simple injective tensors considered in [ 197 , lines 1403–1407 ] .
Pass to the same-dimensional canonical representative \(\mathcal V^{ij}=X\mathcal U^{ij}X^{-1}\). Simplicity is preserved by this bond similarity, as are both source ranks. The simple canonical tensor therefore has rank product \(d^2\). Its one-site blocking only relabels the physical alphabet, so its index is \(\frac12(\log _2 r-\log _2\ell )\). Equality of the periodic operators identifies this index with \(\operatorname {ind}(\mathcal U)\).
Let \(U\) be a positive-dimensional MPU tensor. For every positive integer \(p\), physical blocking preserves its representative index, while physical adjunction reverses its sign:
Choose a reduced canonical-form-II representative \(U_{\mathrm{red}}\). Under the canonical identification of blocked configurations with concatenated configurations, the periodic operators satisfy
Hence blocking and adjunction preserve equality of the positive-length periodic operators. The respective canonical-form-II index identities give \(\operatorname {ind}((U_{\mathrm{red}})_p) =\operatorname {ind}(U_{\mathrm{red}})\) and \(\operatorname {ind}(U_{\mathrm{red}}^\sharp ) =-\operatorname {ind}(U_{\mathrm{red}})\). Representative independence then gives both displayed identities.
Let \(\mathcal U\) be a tensor in canonical form generating matrix product unitaries. The source index is independent of the chosen simple blocking. More precisely, if \(k\geq k_0\geq 1\) and \(\mathcal U_{k_0}\) is simple, then \(\mathcal U_k\) is simple and
This is [ 16 , Proposition IV.2 ] for a tensor in canonical form, the hypothesis under which the source defines the index.
Pass to the similar tensor in canonical form II, which has the same operators, the same simple blockings and the same ranks; for it the statement is the canonical-form-II version.
Let \(\mathcal U\) be an MPU in canonical form II. If \(k_0\) and \(k\) are positive blocking lengths for which \(\mathcal U_{k_0}\) and \(\mathcal U_k\) are simple, then both blocks give the same index. When \(k\geq k_0\), their ranks satisfy
The value is unchanged by positive physical blocking or by choosing a different canonical-form-II presentation of the same tensor. This is the canonical-form-II representative case of [ 16 , Proposition IV.2 ] .
Each simple block retains canonical form II. The source-gate criterion gives \(r_j\ell _j=d^{2j}\) at \(j=k_0,k\), and therefore both ranks are positive. The source-rank blocking bounds, together with these two products, force the displayed equalities when \(k\geq k_0\); the common factor \(d^{k-k_0}\) cancels from the logarithmic difference. The same calculation compares either block with the one used to define the index. A further physical block is the corresponding direct block after the canonical reindexing, so its index is unchanged. Two canonical-form-II presentations of the same tensor are compared at a common simple block.
Let \(\mathcal U\) be an MPU in canonical form II. Its physical adjoint is again in canonical form II, and
This is the canonical-form-II representative case of the index-sign statement in the time-reversal discussion of [ 16 ] . It does not assert that \(\mathcal U\) and \(\mathcal U^\sharp \) generate the same MPU.
Choose a positive simple block \(\mathcal U_k\). Physical adjunction exchanges its two source-cut ranks, so the rank-product criterion makes \((\mathcal U_k)^\sharp \) simple as well. At this block the right-rank formula for \(\mathcal U^\sharp \) is the negative of the left-rank formula for \(\mathcal U\):
Both values are independent of the positive simple block chosen.
For MPU tensors under the source’s standing canonical-form convention,
This is the unrestricted tensor-product statement in [ 16 , Theorem IV.6(ii) ] .
Let \(\mathcal U\) and \(\mathcal V\) be MPUs in canonical form II. Their independent tensor product is again in canonical form II, and
In particular, if \(n{\gt}0\) and \(\mathbb {1}_n\) is the bond-one tensor generating the identity on a physical space of dimension \(n\), then
The bridge to physical identity-ancilla attachment is Theorem 18.9.60. This is the canonical-form-II representative case of the tensoring claim in [ 16 , Theorem IV.6(ii) ] .
Choose a common positive simple blocking length \(k\) for \(\mathcal U\), \(\mathcal V\), and their tensor product. Blocking commutes with the independent tensor product up to a physical relabeling, so their source ranks satisfy
Taking the half-difference of the base-two logarithms gives additivity; independence of \(k\) identifies these values with the three indices. The bond-one identity has index zero by Theorem 18.9.3.23, giving the last assertion.
Let \(U\) and \(V\) be positive-dimensional MPU tensors, possibly with different physical and bond dimensions. Their independent tensor product satisfies
The bond-one identity tensor \(\mathbb {1}_n\) has index zero for every \(n{\gt}0\); hence \(\operatorname {ind}(U\boxtimes \mathbb {1}_n)=\operatorname {ind}(U)\). This is the reduced-representative form of the tensoring assertion in [ 16 , Theorem IV.6(ii) ] .
Choose reduced canonical-form-II representatives \(U_{\mathrm{red}}\) and \(V_{\mathrm{red}}\). By Theorem 18.4.35, for every \(N{\gt}0\),
Representative independence and canonical tensor-product additivity give
The identity tensor itself is a canonical representative of index zero, and the ancilla assertion follows from additivity.
Let \(U\) be a tensor and let \(U^{(n)}=U\otimes \mathbb {1}_n\) denote attachment of an identity ancilla of dimension \(n\) at each physical site, keeping the bond dimension fixed. For every chain length \(N\), its periodic operator equals that of the independent tensor product with the bond-one identity tensor:
Here the identification groups the original physical coordinates and the ancilla coordinates separately. If \(U\) is a positive-dimensional MPU and \(n{\gt}0\), then
Both constructions give the displayed Kronecker product in the same sitewise coordinates. Equality of the periodic operators identifies their representative indices, and the bond-one identity factor has index zero.
Let \(\mathcal U\) be a matrix product operator tensor of physical dimension \(d\) and bond dimension \(D\). For arbitrary matrices \(A\in \mathbb C^{E\times D}\) and \(B\in \mathbb C^{D\times E}\), put \(\mathcal V^{ij}=A\mathcal U^{ij}B\). Then
In particular, a rectangular reduction cannot increase either source rank. No equality of ranks is asserted, and no unitarity, simplicity, or canonical-form assumption is needed. If \(\mathcal V\) is a rectangular reduction of \(\mathcal U\), then for every common blocking length \(L\),
These identities follow directly from the source cuts of [ 16 , Section III, definition of \(r,\ell \) ] and permit upper bounds for composition to pass to a reduced representative.
Expand the matrix products entrywise in the two source cuts. The first cut places the right virtual coordinate on its row side, which accounts for the two transposes. The second cut keeps the ordinary order of the virtual coordinates. Multiplication on either side cannot increase matrix rank, proving both inequalities. For a rectangular reduction, its single-letter word identity gives \(\mathcal V^{ij}=A\mathcal U^{ij}B\). Its all-word identity gives the same relation for the blocked tensors, with the same matrices \(A,B\), so the inequalities apply at every length.
Let \(\mathcal U\) and \(\mathcal V\) be arbitrary matrix product operator tensors of common physical dimension \(d\). For their product tensor, four-site blocking satisfies
No unitarity or simplicity assumption is required.
Use the canonical physical reindexing to identify iterated two-site blocking with direct four-site blocking. For the right cut, write each two-site block in the \(v\)–\(Y_1\)–\(Y_2\) form. Group \(v\) with \(Y_2\) on one side of the cut and retain \(Y_1\) on the other. The cut therefore carries one physical leg and one right source leg from each tensor. Thus, for suitable rectangular matrices \(A_{1,4}\) and \(B_{1,4}\),
where the columns of \(A_{1,4}\) and the rows of \(B_{1,4}\) are indexed by
Consequently,
For the left cut, write each two-site block in the \(X_2\)–\(u\)–\(X_1\) form. Retain \(X_2\) on one side and group \(u\) with \(X_1\) on the other. The cut carries one physical leg and one left source leg from each tensor. For suitable rectangular matrices \(A_{2,4}\) and \(B_{2,4}\),
where the intermediate space is
Hence
Both source-cut ranks are unchanged by the canonical physical relabeling.
Let \(\mathcal W\) generate the composition of the MPUs generated by \(\mathcal U\) and \(\mathcal U'\). Under the source’s standing canonical-form convention,
This is the unrestricted composition statement in [ 16 , Theorem IV.6(ii) ] .
Let \(\mathcal U\) and \(\mathcal V\) have the same physical dimension and bond dimensions \(D\) and \(E\), respectively. Suppose \(\mathcal V\) is in canonical form II and their periodic operators agree at every positive length. Then there are matrices \(A\in \mathbb C^{E\times D}\) and \(B\in \mathbb C^{D\times E}\) such that, for every word \(w\) in the paired physical alphabet,
The empty word is included, so \(AB=I_E\).
The normalized flattening of \(\mathcal V\) is normal. Multiplication by the nonzero scalar \(\sqrt d\) preserves normality, so its unnormalized flattening is normal as well. Equality of the periodic operators gives equality of all positive-length word traces. The equality-case rectangular reduction theorem now supplies \(A\) and \(B\).
Let \(\mathcal U,\mathcal V,\mathcal R\) be canonical-form-II tensors of physical dimension \(d\). Suppose \(\mathcal U\) and \(\mathcal V\) are simple, \(\mathcal R_4\) is simple, and \(\mathcal R\) is a rectangular reduction of \(\mathcal U\mathbin {\cdot }\mathcal V\). Then
Rectangular reduction and the four-site composition bounds give the corresponding upper bounds. Simplicity gives
The product of the two upper bounds is therefore \(d^8\). Since both ranks of \(\mathcal R_4\) are positive, neither inequality can be strict.
Let \(\mathcal U\) and \(\mathcal V\) be MPUs with a common positive physical dimension and positive bond dimensions. For the index defined through a reduced canonical-form-II representative,
In particular, if \(\mathcal U,\mathcal V,\mathcal R\) are in canonical form II and the positive-length periodic operators of \(\mathcal R\) equal the products of those of \(\mathcal U\) and \(\mathcal V\), then their canonical indices satisfy the same identity. The argument is the rank-saturation proof of [ 16 , Theorem IV.6(ii) ] .
Choose reduced canonical representatives for the two factors and their composition. Their positive-length periodic operators still satisfy the composition identity. Theorem 18.9.64 gives a rectangular reduction from the product tensor to its representative \(\mathcal R\). Choose a common positive blocking length \(k\) at which the three representatives are simple, and put \(d_k=d^k\). The rectangular reduction persists under blocking. Rank saturation gives
Subtracting the logarithms cancels \(d_k^2\) and adds the two indices. Independence of positive blocking and of the chosen canonical representatives gives the asserted identity.
Let \(\mathcal U\) and \(\mathcal V\) be canonical-form MPU tensors with physical dimensions \(d_a\) and \(d_b\) and virtual bond dimensions \(D_a\) and \(D_b\). For a tensor \(\mathcal U\) of bond dimension \(D\) and \(D'\geq D\), write \(\mathcal U_{\uparrow D'}\) for the tensor of bond dimension \(D'\) whose letters are those of \(\mathcal U\) in the upper left \(D\times D\) corner and zero on the adjoined directions; adjoining unused bond directions changes no periodic operator of positive length. Given an equality \(h\colon d_a=d_b\), reindex \(\mathcal U\) from \(d_a\) to \(d_b\) along \(h^{-1}\). The tensors are strictly equivalent with respect to \(h\) if there are \(D'\geq \max (D_a,D_b)\) and a continuous path \(\mathcal W(p)\), \(p\in [0,1]\), of MPU tensors of bond dimension \(D'\) such that
Only the canonical-form requirement is relaxed along the path [ 16 , lines 708–714 ] . When \(D_a=D_b=D\), a path of MPU tensors of bond dimension \(D\) from \(\mathcal U\) to \(\mathcal V\) witnesses strict equivalence with \(D'=D\).
Let \(x{\gt}0\). After adjoining an identity ancilla of dimension \(x\), the normalized flattening is the physical reindexing of the original flattening with a normalized diagonal ancilla alphabet. Its transfer map is exactly the original transfer map. Consequently, chosen canonical-form-II data with full support determine canonical-form-II data with full support for \(\mathcal U^{(x)}=\mathcal U\otimes \mathbb {1}_x\).
The product-index equivalence has the orientation
This result preserves the normalized transfer data.
Only the \(x\) diagonal ancilla letters are nonzero, each with coefficient \(x^{-1/2}\). Hence their total transfer contribution is
Thus the transfer map and each diagonal positive fixed matrix are unchanged. The block dimensions, weights, and ambient coisometry are unchanged as well, so full support follows from the same block-dimension sum. The displayed physical reindexing gives the normalized flattening of the enlarged MPO.
Let \(\mathcal U\) and \(\mathcal V\) be MPU tensors with physical dimensions \(d_a\) and \(d_b\). They are equivalent if there are a positive blocking length \(k\) and coprime positive integers \(p_a,p_b\) with
such that \((\mathcal U^{(p_a)})_k\) and \((\mathcal V^{(p_b)})_k\) are strictly equivalent. Here the positive-dimensional identity ancillas are attached before the common blocking, and
As in [ 16 , lines 716–724 ] , canonical form of the blocked tensors with ancilla is a condition of the definition.
An admissible strict-equivalence datum for a path \([0,1]\ni p\mapsto \mathcal W(p)\) consists of a common positive blocking length \(m\) such that the actual blocked path tensor \(\mathcal W(p)_m\) is simple and carries a reduced full-support source datum for every \(p\). The blocked tensors and their source data vary continuously with \(p\), after fixed identifications of the finite-dimensional spaces involved. No equivalent or reduced representative may replace \(\mathcal W(p)_m\). In particular, the actual blocked endpoint tensors carry their own source data.
When the path is used under a specified symmetry \(\mathcal S\), the datum also includes continuously varying reduced full-support source data for the fixed family of comparison paths
Every tensor in this family is simple. This requirement is part of the datum independently of which comparisons a later proof uses; no preservation under conjugation, physical adjoint, transposition, or \(\mathcal S\) is assumed.
Two tensors are admissibly strictly equivalent if their strict equivalence is witnessed by such a path. They are admissibly equivalent if the blocked, ancilla-enlarged endpoints in Definition 18.9.69 are joined by an admissible strict-equivalence path. The source arguments motivating these additional path hypotheses are Proposition IV.5, Theorem IV.6, Corollary IV.7, and the lemma following the symmetry-equivalence definitions in [ 16 ] ; the datum itself is introduced here and has no source-labelled counterpart.
Let \(P\) and \(Q\) be orthogonal projections on a complex inner-product space. The compression of \(Q\) to \(\operatorname {ran}P\) is self-adjoint. If a unit vector \(x\in \operatorname {ran}P\) satisfies
then there is a unit vector \(w\perp x\) such that
Thus \(\operatorname {span}\{ x,w\} \) is the two-dimensional angle block associated with the eigenvalue \(\mu \in (0,1)\).
Set \(d=Qx-\mu x\). Symmetry and idempotence give
Since \(0{\lt}\mu {\lt}1\), the vector \(w=d/\sqrt{\mu (1-\mu )}\) is well defined and has the stated properties.
For orthogonal projections \(P\) and \(Q\) on a finite-dimensional complex inner-product space, let \((x_i)_i\) be an orthonormal eigenbasis of the compression of \(Q\) to \(\operatorname {ran}P\), with ordered real eigenvalues \((\mu _i)_i\).
Let \(P\) and \(Q\) be orthogonal projections on a finite-dimensional complex inner-product space, with compression spectral data \((x_i,\mu _i)\). Then, for every \(i\), \(\mu _i\in [0,1]\) and exactly one of the following alternatives holds:
\(\mu _i=0\) and \(Qx_i=0\);
\(\mu _i=1\) and \(Qx_i=x_i\);
\(0{\lt}\mu _i{\lt}1\), and \(x_i\) belongs to the two-dimensional angle block described in Theorem 18.9.71.
This theorem classifies the compression eigenvectors.
Apply the finite-dimensional spectral theorem to the self-adjoint compression of \(Q\) to \(\operatorname {ran}P\). For a unit compression eigenvector \(x\) with eigenvalue \(\mu \), the angle-defect identity gives
hence \(0\leq \mu \leq 1\). At \(\mu =0\) or \(1\) the defect vanishes, giving the two common one-dimensional blocks. For \(0{\lt}\mu {\lt}1\), apply Theorem 18.9.71.
For compression spectral data \((x_i,\mu _i)\), define
For all indices \(i,j\),
In particular, \(\langle d_i,d_j\rangle =0\) when \(i\ne j\), including when \(\mu _i=\mu _j\). The block \(B_i\) has dimension at most two, is invariant under both \(P\) and \(Q\), and satisfies \(B_i\perp B_j\) for distinct indices.
Since \(Px_i=x_i\), symmetry of \(P\) and the compression eigenvalue equation give
Conjugate symmetry gives \(\langle d_i,x_j\rangle =0\). For the exact defect pairing, symmetry of \(Q\) and the local action formula give
Orthogonality of the generated spans follows by linearity. The action formulas
show that both projections preserve \(B_i=\operatorname {span}\{ x_i,d_i\} \). Its dimension bound follows from its two generators.
For the compression defect blocks \((B_i)_i\), define
The index \(i\) ranges over every vector in the chosen compression eigenbasis, including repeated eigenvalues and the endpoint eigenvalues \(0\) and \(1\).
The blocks \((B_i)_i\) form an orthogonal internal direct sum in \(B\), and
Both \(B\) and \(K\) are invariant under \(P\) and \(Q\), with \(\operatorname {ran}P\subseteq B\), so for every \(z\in K\),
Consequently the restrictions \(P|_K\) and \(Q|_K\) are commuting orthogonal projections on \(K\).
Pairwise orthogonality of the blocks implies independence, while their supremum is \(B\) by definition. Hence they form an internal direct sum in \(B\). The standard orthogonal-complement decomposition gives \(E=B\mathbin {\perp \! \oplus }B^\perp \).
The local action formulas show that each \(B_i\) is invariant under both projections, hence so is \(B\). Symmetry of each projection then makes \(K=B^\perp \) invariant. The compression eigenvectors form a basis of \(\operatorname {ran}P\), and each lies in its block \(B_i\); therefore \(\operatorname {ran}P\subseteq B\). Thus \(P\) vanishes on \(K\). Since \(Qz\in K\) whenever \(z\in K\), both \(P(Qz)\) and \(Q(Pz)\) vanish. The two restricted projections therefore commute.
Let \(P\) and \(Q\) be orthogonal projections on a finite-dimensional complex inner-product space. Define \(\widetilde P\) as the orthogonal projection onto \(\operatorname {ran}(PQ)\).
The reduced projection satisfies
The first two identities describe the canonical construction, while the next three establish the properties in source lines 767–769. The final range equality is the derived input to the right-factor theorem, not item (iv) of the source.
Set \(A=QP\). The standard range identity for \(A^\dagger A\) gives
By definition, \(\operatorname {ran}(\widetilde P)=\operatorname {ran}(PQ)\), which also gives \(P\widetilde P=\widetilde P\). For all \(x\) and \(z\),
Hence \(Qx-PQx\in \operatorname {ran}(PQ)^\perp \), so orthogonal projection onto this range yields \(\widetilde P Q=PQ\). Taking adjoints gives \(Q\widetilde P=QP\). Finally,
For orthogonal projections \(P\) and \(Q\), the reduced range contains no nonzero vector annihilated by \(Q\):
If \(x=PQy\) and \(Qx=0\), then \(Px=x\) and symmetry of the two projections gives
Hence \(x=0\).
There is an invertible linear map \(Y\) such that
The equality
and the equal-ranges right-factor theorem give an invertible \(Y\) satisfying \(\widetilde P QY=\widetilde P\).
In standard Euclidean coordinates, let \(\widetilde P\) be the matrix of the reduced projection associated with two square matrices \(P\) and \(Q\).
If \(P\) and \(Q\) are orthogonal projections, then \(\widetilde P\) is an orthogonal projection and
There is also an invertible matrix \(Y\) satisfying \(\widetilde P QY=\widetilde P\).
Let \(U=(U^{ij})\) be an MPO tensor, and let \(\widehat U^{ij}=AU^{ij}B\). Then
Expand the transfer map and collect the factors \(A\), \(B\), \(B^\dagger \), and \(A^\dagger \) outside the finite sum.
Let \(W=(W^{ij})\) be an MPO tensor, let \(\widehat E_W\) denote the transfer map of its normalized flattening, and set \(\widehat W^{ij}=AW^{ij}B\). For every bond matrix \(X\),
In particular, suppose that \(\widehat E_W(X)=\operatorname{tr}(LX)R\) for every \(X\). For any bond matrices \(P,Q\), let \(T\) be their reduced projection and set \(\widetilde W^{ij}=TW^{ij}T\). Then
This is the normalized compression identity in the proof of [ 16 , Proposition IV.5 ] .
Scalar normalization commutes with left and right multiplication. Expanding the normalized transfer map therefore gives the first identity by collecting the constant factors outside the finite sum. For the reduced projection, \(T^\dagger =T\), and cyclicity of the trace gives \(\operatorname{tr}(LTXT)=\operatorname{tr}(TLTX)\).
Let \(\rho \succeq 0\). If
then
If the quadratic form of \(V^\dagger \rho V\) vanished at a nonzero vector \(x\), positive semidefiniteness would give \(\rho Vx=0\). The support projection would then annihilate \(Vx\), contrary to the hypothesis.
Let \(W=(W^{ij})\) be an MPO tensor. Let \(L,R\succeq 0\) satisfy
and let \(P\) and \(Q\) be their support projections. Assume, letter by letter,
Set \(T=\widetilde P\) and \(\widetilde W^{ij}=TW^{ij}T\). Then, for every \(N\geq 0\),
If \(V^\dagger V=I\) and \(VV^\dagger =T\), then
For every nonempty word \(w\), idempotence of \(T\) and (541) give
Cyclicity of the trace, together with \(QW_w=W_w=W_wP\), therefore gives \(\operatorname {tr}(TW_wT)=\operatorname {tr}(W_w)\). Length zero is immediate. Lemma 18.9.84, with \(A=B=T\) and \(T^\dagger =T\), gives
Since \(P\) and \(Q\) are the support projections of \(L\) and \(R\), respectively,
Combining these absorptions with (541), \(T^2=T\), and cyclicity of the trace gives
Let \(x\neq 0\) and set \(u=Vx\). Since \(V^\dagger V=I\), one has \(u\neq 0\); since \(VV^\dagger =T\), one has \(Tu=u\). Equation (541) gives \(Pu=u\), and (537) gives \(Qu\neq 0\). Thus
Applying Lemma 18.9.86 to \(L\) and \(R\) yields
Let \(W\) have bond dimension \(D\), and let \(A\in \mathbb C^{E\times D}\) and \(B\in \mathbb C^{D\times E}\) satisfy \(BA=I_D\). The tensor with letters \(AW^{ij}B\) is simple if and only if \(W\) is simple. In particular, if \(V^\dagger V=I_k\) and \(VV^\dagger =T\), simplicity of \((TW^{ij}T)\) implies simplicity of \((V^\dagger W^{ij}V)\).
Put \(\mathcal A=\overline A\otimes A\) and \(\mathcal B=\overline B\otimes B\), in the doubled bond coordinates. The double-layer letters \(F^{ij}\) of \(W\) transform to \(\mathcal A F^{ij}\mathcal B\), and \(\mathcal B\mathcal A=I\). If \((a|,|b)\) are simplicity witnesses for \(W\), then \((a|\mathcal B,\mathcal A|b)\) are witnesses for the included tensor. Conversely, witnesses \((a|,|b)\) for the included tensor give \((a|\mathcal A,\mathcal B|b)\) for \(W\). Substitution in (11) and (12) proves both claims. For the assertion about support coordinates, use \(V(V^\dagger W^{ij}V)V^\dagger =TW^{ij}T\).
Let \(W\) be simple with \(d{\gt}0\). Let \(P\) be an orthogonal projection and \(Q\) a square matrix on its bond space, with \(W^{ij}P=W^{ij}=QW^{ij}\). Suppose the normalized diagonal \(E\) of its double layer has a rank-one factorization \(E=|\rho )(\Phi |\). If \(T\) is the reduced projection associated with \(P,Q\), then \((TW^{ij}T)\) is simple.
Write \(F^{ij}\) for the double-layer letters and put \(\mathcal P=\overline P\otimes P\), \(\mathcal Q=\overline Q\otimes Q\), and \(H=\overline T\otimes T\). The letterwise support identities also hold for their normalized diagonal \(E\). Since \(TQ=PQ\), they give
whenever \(X,Y\) are double-layer letters or \(E\). The supplied-projector identity is \(F^{ij}F^{k\ell }=F^{ij}EF^{k\ell }\). Using (559) and \(H^2=H\) therefore yields
These are the double-layer letters of the compressed tensor, and \(HEH=|H\rho )(\Phi H|\) supplies its two simplicity witnesses. Support compression preserves the periodic operators, so the compressed tensor still generates an MPU. Its two-letter insertion identity then implies the first simplicity contraction with the same witnesses.
Let \(L,R\succeq 0\), let \(P\) and \(Q\) be their support projections, and let \(\widetilde P\) be the reduced projection of \(P\) and \(Q\). There are invertible support-inverse extensions of \(L\) and \(R\), together with an invertible matrix \(Y\), such that \(PQY=\widetilde P\).
Extend the inverses on the supports by the identity on their orthogonal complements, and choose an invertible right factor for the reduced projection.
Let \(W=(W^{ij})\) be an MPO tensor, let \(L\), \(R\), \(X\), \(Z\), \(Y\) be square matrices of the same size, let \(P\) be an orthogonal projection, let \(Q\) be a square matrix of the same size, and set \(\widetilde P\) equal to their reduced projection. Assume, letter by letter, \(W^{ij}P=W^{ij}=QW^{ij}\). Set \(\widehat W^{ij}=LW^{ij}R\) and \(\widetilde W^{ij}=\widetilde P W^{ij}\widetilde P\). If \(X,Z,Y\) satisfy \(XL=P\), \(RZ=Q\), and \(PQY=\widetilde P\), then
If in addition \(X\), \(Z\), and \(Y\) are invertible, then
If \(L,R\succeq 0\) and \(P=\operatorname {supp}(L)\), \(Q=\operatorname {supp}(R)\), such invertible matrices may be chosen as \(X=L^++(\mathbb {1}-P)\), \(Z=R^++(\mathbb {1}-Q)\), together with an invertible right factor \(Y\) of the reduced projection.
Expanding each virtual sandwich and using \(XL=P\) and \(RZ=Q\) gives (561). The absorptions \(QW^{ij}=W^{ij}=W^{ij}P\) give, letter by letter,
which is (562). Since \(\widetilde P Q=PQ\) and \(PQY=\widetilde P\),
This proves (563) and (564). Thus \(\widetilde W\) is obtained from \(\widehat W\) by left multiplication by \(X\) and right multiplication by \(ZY\). Invertibility of these factors and the source ranks of a virtual sandwich (Theorem 18.9.100) give
by invertibility of \(X\) and \(ZY\) together with the relation \(X\widehat W(ZY)=\widetilde W\) from (561)–(564), yielding (565) and (566). For positive semidefinite \(L\) and \(R\), their ambient support-inverse extensions supply \(X\) and \(Z\); the invertible right-factor identity for \(\widetilde P Q\) supplies \(Y\).
For finite index sets \(M,N\), matrix rank defines a lower-semicontinuous map
Consequently, if \(A\colon X\to \operatorname {Mat}_{M\times N}(\mathbb C)\) is continuous, then \(x\mapsto \operatorname {rank}A(x)\) is lower semicontinuous.
For every \(k\in \mathbb N\), the sublevel set is the closed determinantal set
These closed sublevel sets characterize lower semicontinuity. Composition with a continuous map preserves lower semicontinuity.
Let \(r,\ell \colon X\to \mathbb N\) be lower semicontinuous. Suppose that \(c{\gt}0\) and
for every \(x\in X\). Then both \(r\) and \(\ell \) are locally constant.
Fix \(x\in X\). Since \(c{\gt}0\), both \(r(x)\) and \(\ell (x)\) are positive. Lower semicontinuity gives a neighborhood \(U\) of \(x\) on which
For \(y\in U\), monotonicity of multiplication and the fixed-product identity give
Positivity permits cancellation, first of \(\ell (x)\) and then of \(r(x)\), so \(r(y)=r(x)\) and \(\ell (y)=\ell (x)\).
Under the hypotheses of Theorem 18.9.93, if \(S\subseteq X\) is preconnected, then for all \(x,y\in S\),
In particular, both functions are constant when \(X\) is preconnected and when \(X=[0,1]\).
A locally constant function has open fibers. A preconnected set cannot meet two disjoint nonempty open fibers, so each of \(r\) and \(\ell \) has one value on \(S\). The unit interval is connected, hence preconnected.
For an MPO tensor \(\mathcal U=(U^{ij})_{0\leq i,j{\lt}d}\) of bond dimension \(D\) and matrices \(A,B\in \mathbb C^{D\times D}\), define
If \(x\mapsto A(x)\), \(x\mapsto \mathcal U(x)\), and \(x\mapsto B(x)\) are continuous families, then
is continuous.
Every matrix entry is a finite sum of products of entries of \(A(x)\), \(\mathcal U(x)\), and \(B(x)\), hence is continuous.
Let \(q:\{ 0,\ldots ,D{-}1\} \times \{ 0,\ldots ,D{-}1\} \to \{ 0,\ldots ,D^2{-}1\} \) be the standard enumeration of a pair. For an MPO tensor \(\mathcal W\) and a doubled-virtual matrix \(E\in \mathbb C^{D^2\times D^2}\), define
If \(E(\mathcal W)\) denotes the normalized physical diagonal of the physical-adjoint double layer of \(\mathcal W\), let \(E'(\mathcal W)\) be the matrix obtained by exchanging the two entries of its column pair, \(E'(\mathcal W)_{p,q(c,a)}=E(\mathcal W)_{p,q(a,c)}\), and define
This is the contraction shown in Figure IV_index4.png of [ 16 , Proposition IV.5 ] .
Let \(L,R\in \mathbb C^{D\times D}\) and let \(\operatorname {vec}\) stack matrix columns, so
Then the rank-one doubled-virtual matrix satisfies
No adjoint or normalization factor occurs in the contraction result. The binary map \((\mathcal W,E)\mapsto C(\mathcal W,E)\), the map \(\mathcal W\mapsto E(\mathcal W)\), and consequently the map \(\mathcal W\mapsto \widehat{\mathcal W}_{\mathrm{ff}}\) are continuous. If \(d{\gt}0\) and the normalized transfer map satisfies \(\mathcal E_{\mathcal W}(X)=\operatorname{tr}(LX)R\) for every \(X\), then \(\widehat W_{\mathrm{ff}}^{ij}=LW^{ij}R\). Consequently, for a continuous family \(\mathcal W(x)\) with pointwise trace factors \(L(x),R(x)\), the tensors \(L(x)W^{ij}(x)R(x)\) are continuous, whether or not the factors themselves are chosen continuously. These assertions neither choose \(L\) and \(R\) continuously nor infer their positivity. They make no claim about reduced representatives or constancy of ranks.
Expanding the left-hand side of (581) and using column stacking gives
This proves (581). Each entry in (576) is a finite sum of products, so the binary contraction is continuous. The double-layer entries are finite sums of products of entries of \(\mathcal W\) and their complex conjugates, and the normalized physical diagonal is another finite sum. Hence \(\mathcal W\mapsto E(\mathcal W)\) is continuous. Substitution into (577) proves continuity of the factor-free sandwich. For the trace-factor identity, column vectorization gives \(E(\mathcal W)=\operatorname {vec}(R)\operatorname {vec}(L^{\mathsf T})^T\). Therefore \(E'(\mathcal W)=\operatorname {vec}(R)\operatorname {vec}(L)^T\), and (581) yields \(\widehat W_{\mathrm{ff}}^{ij}=LW^{ij}R\). Applied pointwise, this equality proves the asserted continuity without any regularity of the factors.
The two raw source cuts satisfy the literal formulas
The transposes in (584) result from the corrected orientation of \(M_1\); no complex conjugation occurs.
Expand an entry of each right-hand side. The identity factors collapse the two physical sums. For the first cut, the entries of \(B^{\mathsf T}\) and \(A^{\mathsf T}\) put \(B_{\delta \beta }\) on the left and \(A_{\alpha \gamma }\) on the right; commutativity of scalar multiplication gives
The second cut gives the same entry directly.
If \(A\) and \(B\) are invertible, then
This assertion concerns the raw source ranks only.
The determinant identities for Kronecker products show that \(A\otimes I_d\) and \(I_d\otimes B\) are invertible. Left and right multiplication by these matrices preserves rank. Apply this observation to each source-cut formula in Theorem 18.9.99.
Let \(A,B\) be square matrices on the bond space with \(BA=I\). The tensor with letters \(AU^{ij}B\) has the blockings \(A\, U_L\, B\), the same periodic operators as \(\mathcal U\), and is simple if and only if \(\mathcal U\) is; the ranks of its blockings equal those of \(\mathcal U\).
The letters of a blocking are products, and \(BA=I\) telescopes; the trace is cyclic; the double layer is conjugated by \(\bar A\otimes A\), which carries the boundary vectors along; the ranks by the source-ranks theorem.
Let \(\mathcal U\) and \(\mathcal V\) be simple tensors in canonical form II with \(V^{ij}=zU^{ij}z^\dagger \) for a unitary \(z\) on the virtual space. Their recorded positive matrices need not be related. Write \(X_a(\mathcal U),Y_a(\mathcal U)\) and \(X_a(\mathcal V),Y_a(\mathcal V)\) for their selected source factors, \(a=1,2\). After identifying the equal source ranks, there are unitaries \(W_1\) and \(W_2\) on the respective source-rank spaces such that
This is the forward factor comparison associated with the diagrams in [ 16 , lines 624–648 ] ; it does not assert a converse from the local relations to equality at every chain length. The scalar-free step is the isometric specialization of [ 197 , lines 1052–1066 ] .
The two cut identities of Theorem 18.9.99, applied to the selected factorizations of Theorem 18.4.53, give transported factorizations with the four exterior matrices displayed in the statement. The right exterior matrices are unitary, so the transported right factors retain the right inverses of Theorem 18.4.58. The left exterior matrix of the second cut is unitary, so its transported left factor remains an isometry. The contraction defining \(u\) is unchanged: its interior virtual product is \(z^\dagger z=I_D\). Rank preservation, Theorem 18.9.100, identifies the transported factors with the selected source-rank spaces. Simplicity and the source-gate equivalence of Theorem 18.9.12 give unitarity of both \(u\) contractions. The selected factors have left inverses from their weighted first-cut and ordinary second-cut normalizations in Theorem 18.4.55. The normalized source-decomposition comparison of Corollary 19.5.10.3 now gives the two unitary changes \(W_1,W_2\) and the four displayed equalities.
In the setting of Theorem 18.9.102, write \(u_{\mathcal U},u_{\mathcal V}\) for the source gates of Definition 18.4.59 built from the selected factors. Substituting the two \(Y_a(\mathcal V)\) identities into that contraction, the interior virtual product is \(\sum _\beta (z^\dagger )_{\beta '\beta } z_{\beta \beta ''}=(z^\dagger z)_{\beta '\beta ''}=\delta _{\beta '\beta ''}\), so
Thus the unitaries \(x=W_2^\dagger \) and \(y=W_1^\dagger \) realize the local relation \(u_{\mathcal V}=(x\otimes y)u_{\mathcal U}\) of Theorem 18.9.32. This identification of the gauges is a consequence of the displayed factor identities and is not asserted by Theorem 18.9.102. It is stated, together with the corresponding relation for \(v\), in Theorem 18.9.104.
Let \(\mathcal U\) and \(\mathcal V\) be simple tensors in canonical form II with \(V^{ij}=zU^{ij}z^\dagger \) for a unitary \(z\). Let \(e_r:r[\mathcal U]\simeq r[\mathcal V]\) and \(e_\ell :\ell [\mathcal U]\simeq \ell [\mathcal V]\) be the source-rank bijections. Reindex the source gates of \(\mathcal U\) by
There are unitaries \(x\) on \(\ell [\mathcal V]\) and \(y\) on \(r[\mathcal V]\) such that
Relation (591) is the forward \(u\) relation of [ 16 , Equation (SFuu) ] . The source’s [ 16 , Equation (SFvv) ] displays two relations between the open half-factors involving \(z\); contraction of those half-factors yields (592). No converse for the original periodic operators at odd length is asserted.
Use the four selected-factor identities of Theorem 18.9.102. Their source-rank changes are \(x=W_2^\dagger \) and \(y=W_1^\dagger \). The two source-gate contractions have entries
In the first contraction, the two virtual matrices cancel as \(z^\dagger z=I_D\), leaving \((x\otimes y)\widetilde u\). In the second, the first-cut transpose and second-cut left action likewise contract to \(z^\dagger z=I_D\), leaving \(\widetilde v(y^\dagger \otimes x^\dagger )\).
Let \(A\succeq 0\) have support projection \(P\), and let \(A^+\) denote its inverse on the support. Define
Define also
This construction gives the invertible matrices for Proposition IV.5 of [ 16 ] .
The matrices \(X_A\) and \(Z_A\) are mutually inverse, and
Consequently, \(X_A\) is a unit in the matrix algebra, with inverse \(Z_A\), and \(\det (X_A)\) is a unit in \(\mathbb C\).
In the notation of Proposition IV.5 of [ 16 ] , let \(L\) and \(R\) be the positive semidefinite outer factors with support projections \(P\) and \(Q\), respectively. The required witnesses are
Thus
or equivalently \(XL=P\) and \(RZ=Q\). Here the paper’s matrix \(Z\) is \(X_R\), not the inverse-extension matrix \(Z_R\) from Definition 18.9.105.
The support identities give
Their complementary forms are
and idempotence of \(P\) gives
Therefore
Likewise,
while multiplication by \(A\) gives \(X_AA=AX_A=P\).
Let \([0,1]\ni x\mapsto \mathcal W(x)\) be a continuous path of tensors generating MPUs, without requiring the path to be in canonical form. For each \(x\), take the canonical form and the two source-cut ranks \(r(x)\) and \(\ell (x)\) of its associated simple tensor. Then \(r(x)\) and \(\ell (x)\) are constant on \([0,1]\).
Let \([0,1]\ni x\mapsto \mathcal W(x)\) be a continuous path of tensors generating MPUs, without requiring the path to be in canonical form. Suppose that the path carries an admissible equivalence datum with blocking length \(m\). Then the ranks \(r(x)\) and \(\ell (x)\) of the actual blocked path tensors \(\mathcal W(x)_m\) are constant on \([0,1]\).
Let \([0,1]\ni x\mapsto \mathcal U(x)\) be a continuous path of tensors of fixed physical dimension \(d\) and bond dimension \(D\). Suppose that each \(\mathcal U(x)\) is in canonical form II. Then for all \(x,y\in [0,1]\),
This is the canonical-form-II path case of [ 16 , Proposition IV.5 ] . Its hypotheses are not comparable with those of Proposition 18.9.108: here each tensor of the path is in canonical form II, but no continuously varying source data are assumed; there the path may leave canonical form, but continuously varying source data at a common blocking length are assumed.
Blocking is continuous, and the two source cuts are coordinate rearrangements of the blocked tensor. Thus their ranks are lower semicontinuous functions of \(x\). The common block of length \(D^4\) is simple at every point. Its ranks obey
Lower semicontinuity and this fixed positive product make both ranks constant on the connected interval.
Under the hypotheses of Theorem 18.9.109, the index of \(\mathcal U(x)\) is independent of \(x\in [0,1]\).
Every \(D^4\)-site block is simple, so for every \(x\in [0,1]\),
Both ranks on the right-hand side are independent of \(x\) by Theorem 18.9.109.
For MPU tensors under the source’s standing canonical-form convention, take the index defined from any simple blocking. This index has the following properties.
It is invariant under blocking.
It is additive under tensor products and composition.
It is constant under continuous deformations through MPU tensors.
Two MPU tensors have the same index if and only if they are equivalent.
This is the unrestricted statement of [ 16 , Theorem IV.6 ] .
Assume the following operation-specific admissibility hypotheses. Every pair of simple blockings compared for blocking independence carries reduced full-support source data. Tensor products need no hypothesis, by Theorem 18.9.59. For a composition tensor \(\mathcal W\) of \(\mathcal U\) and \(\mathcal U'\), there is one positive length \(k\) such that
are simple and carry their own data. Continuous-deformation and equivalence claims use the path data of Definition 18.9.70. Under these hypotheses, the MPU index has the following properties.
It is invariant under blocking.
It is additive under tensor products and composition.
It is constant under continuous deformations through MPU tensors.
Admissibly equivalent MPU tensors have the same index. Conversely, tensors with the same index are admissibly equivalent whenever the standard-form interpolation is supplied with an admissible path datum.
These are the conclusions of [ 16 , Theorem IV.6 ] , restricted to the explicit admissibility hypotheses above.
For every continuous path \(p\mapsto \mathcal U(p)\) of MPU tensors, not necessarily in canonical form, there are an integer \(k_0\leq D^4\) and continuous paths of unitaries \(u(p)\) and \(v(p)\) such that \(U^{(2k_0N)}(p)\) has standard form given by \(u(p)\) and \(v(p)\).
Let \(k_0\) be the common blocking length in an admissible equivalence datum for a continuous path \(\mathcal U(p)\) of MPU tensors, and suppose that this supplied length satisfies \(k_0\leq D^4\). Then there are continuous paths of unitaries \(u(p)\) and \(v(p)\) such that the MPU \(U^{(2k_0N)}(p)\) has standard form given by \(u(p)\) and \(v(p)\) for every \(p\in [0,1]\). This is the reduced-source version of [ 16 , Corollary IV.7 ] .
18.9.1 Local characterization of symmetries
Let \(x\) and \(y\) be unitary matrices over \(\mathbb C\), indexed by nonempty finite sets, whose entrywise conjugates satisfy
Then there is a sign \(\sigma \in \{ 1,-1\} \) with
Equivalently, either \(x=x^T\) and \(y=y^T\), or \(x=-x^T\) and \(y=-y^T\). This is the algebraic conclusion in [ 16 , lines 1033–1038 ] .
A Kronecker product equal to the identity has reciprocal scalar factors, so \(\overline xx=e^{i\phi }\mathbb {1}\) and \(\overline yy=e^{-i\phi }\mathbb {1}\). Since \(x\) is unitary, \(x^T\overline x=\mathbb {1}\); multiplying \(\overline xx=e^{i\phi }\mathbb {1}\) on the left by \(x^T\) gives \(x=e^{i\phi }x^T\), and similarly \(y=e^{-i\phi }y^T\). Transposing \(x=e^{i\phi }x^T\) gives \(x^T=e^{i\phi }x\), hence \(x=e^{2i\phi }x\); since \(x\) is invertible, \(e^{2i\phi }=1\), so \(e^{i\phi }=\pm 1\) and \(e^{-i\phi }=e^{i\phi }\). The two matrices therefore carry one transpose sign.
An MPU in standard form is invariant under complex conjugation if and only if there are unitaries \(x\) and \(y\) such that either \(x=x^T\) and \(y=y^T\), or \(x=-x^T\) and \(y=-y^T\), and
This is the unrestricted conjugation characterization in [ 16 , Proposition V.1 ] .
Let a tensor and its conjugate comparison tensor both be equipped with reduced full-support source data and written in the standard forms determined by those data. The generated MPU is invariant under complex conjugation if and only if there are unitaries \(x\) and \(y\) such that either \(x=x^T\) and \(y=y^T\), or \(x=-x^T\) and \(y=-y^T\), and
This is the reduced-source version of the conjugation characterization in [ 16 , Proposition V.1 ] .
Let \(x\) be a symmetric unitary matrix. There is a symmetric unitary matrix \(S\) such that
This is the symmetric branch of [ 16 , Lemma lemma:conjclass-normalform-continuous ] .
Write the finite spectral decomposition of \(x\) as
and set
Each spectral value has modulus one, so its square root has modulus one, and hence \(S\) is unitary and \(S^2=x\). On the finite spectrum, interpolate the square-root function by a polynomial \(q\). Then \(S=q(x)\), and \(x^T=x\) implies \(S^T=q(x^T)=q(x)=S\). Therefore \(x=S^2=S^T S\).
Let \(I\) be a finite set and let \(H\in \operatorname {Mat}_I(\mathbb C)\) be Hermitian with \(H^2=\mathbb {1}\) and \(\operatorname {tr}H=0\). Then
Let \(\mu _1,\dots ,\mu _{|I|}\) be the real eigenvalues of \(H\). Applying \(H^2=\mathbb {1}\) to an eigenvector gives \(\mu _j^2=1\), so \(\mu _j=\pm 1\) and \(i\mu _j=e^{i\pi \mu _j/2}\). The trace condition gives \(\sum _j\mu _j=0\). Hence
Let \(K\) and \(I\) be finite sets, let \(E_k\in \mathbb R\) for \(k\in K\), and let \(P_k\) be Hermitian projectors on \(\mathbb C^I\). Suppose that the family \(\{ P_k,P_k^T\} _{k\in K}\) consists of mutually orthogonal projectors and sums to the identity. Define
Then the matrices
and
are unitary, \(S^T=S\), \(\overline{\widetilde\Lambda }=\widetilde\Lambda \), \(\widetilde\Lambda ^T=-\widetilde\Lambda \), \(\det \widetilde\Lambda =1\), and
This is the paired-projector construction in the skew branch of [ 16 , Lemma lemma:conjclass-normalform-continuous ] .
Write the two projectors in each pair as separate members of one complete orthogonal family. A weighted sum of this family is unitary whenever every weight has modulus one. This applies to \(S\), whose two weights at \(k\) both equal \(e^{-i\pi /4}e^{-iE_k/2}\), and to \(\widetilde\Lambda \), whose weights are \(i\) and \(-i\). Transposition exchanges the two members of each pair, proving the symmetry of \(S\) and the skew symmetry of \(\widetilde\Lambda \). Hermiticity gives \(\overline{P_k}=P_k^T\), hence \(\overline{\widetilde\Lambda }=\widetilde\Lambda \). Finally, orthogonality reduces the product to its weights, and
The transposed member has the negative weight, which gives \(x=S^T\widetilde\Lambda S\). For the determinant, the same reduction gives \(\widetilde\Lambda ^2=-\mathbb {1}\), so \(\widetilde\Lambda =iH\) with \(H=\sum _{k\in K}(P_k-P_k^T)\) a Hermitian involution. Since \(\operatorname {tr}P_k^T=\operatorname {tr}P_k\), the trace of \(H\) vanishes, and Lemma 18.9.1.5 gives \(\det \widetilde\Lambda =1\). These are the eigenvalue pairs \(\pm i\) of the source.
Let \(x\) be a normal complex matrix with finite spectrum \(\sigma (x)\), and for \(\mu \in \mathbb C\) let \(P_\mu \) be the spectral projector of \(x\) at \(\mu \), that is, the indicator function of the point \(\mu \) applied to \(x\). Then each \(P_\mu \) is Hermitian,
If moreover \(x^T=-x\), then
This is the pairing of \(P_E\) with \(P_E^T\) in the skew branch of [ 16 , Lemma lemma:conjclass-normalform-continuous ] .
The first three identities hold for the indicator functions on \(\sigma (x)\). For the last, interpolate the indicator of \(\mu \) on the finite set \(\sigma (x)\) by a polynomial \(q\), so that \(P_\mu =q(x)\). Then \(P_\mu ^T=q(x^T)=q(-x)\). Since \(\sigma (x)=\sigma (x^T)=-\sigma (x)\), the polynomial \(z\mapsto q(-z)\) agrees on \(\sigma (x)\) with the indicator of \(-\mu \), and hence \(q(-x)=P_{-\mu }\).
Let \(x\) be a unitary matrix with \(x^T=-x\). There are a finite set \(K\), Hermitian projectors \(P_k\) and numbers \(E_k\in [0,\pi )\), for \(k\in K\), such that the family \(\{ P_k,P_k^T\} _{k\in K}\) consists of mutually orthogonal projectors summing to the identity, and
This is the spectral decomposition in the skew branch of [ 16 , Lemma lemma:conjclass-normalform-continuous ] .
Every spectral value of \(x\) has modulus one, so it is nonzero and differs from its negative. By Lemma 18.9.1.7, \(\sigma (x)=-\sigma (x)\) and \(P_\lambda ^T=P_{-\lambda }\). A nonzero complex number has argument in \((-\pi ,0]\) exactly when its negative does not, so let \(K\) be the set of spectral values with argument in \((-\pi ,0]\); it contains exactly one member of each pair \(\{ \lambda ,-\lambda \} \). Set \(P_\lambda \) for the projector at \(\lambda \in K\) and \(E_\lambda =-\arg \lambda \in [0,\pi )\), so that \(e^{-iE_\lambda }=\lambda \). The members of the family \(\{ P_\lambda ,P_\lambda ^T\} _{\lambda \in K}\) are the spectral projectors at the distinct points \(\pm \lambda \), so they are mutually orthogonal and sum to the identity. Finally,
Let \(x\) be a unitary matrix with \(x^T=-x\). There are a symmetric unitary matrix \(S\) and a real skew-symmetric unitary matrix \(\widetilde\Lambda \) with \(\det \widetilde\Lambda =1\) such that
This is the skew branch of [ 16 , Lemma lemma:conjclass-normalform-continuous ] .
Let \(x\) be unitary and satisfy \(x=x^T\) or \(x=-x^T\). There are a symmetric unitary \(S\) and a matrix \(\widetilde\Lambda \) such that
In the symmetric case, \(\widetilde\Lambda \) is real and symmetric. In the skew-symmetric case, it is real and skew-symmetric. In both cases, \(\det (\widetilde\Lambda )=1\).
In the symmetric case, Lemma 18.9.1.4 gives \(x=S^TS\), so \(\widetilde\Lambda =\mathbb {1}\) works. The skew-symmetric case is Lemma 18.9.1.9. A matrix that is both symmetric and skew-symmetric vanishes, and a vanishing unitary exists only on the zero space, where both conditions on \(\widetilde\Lambda \) hold.
Let \(I\) be a finite set of odd cardinality and let \(A\in \operatorname {Mat}_I(\mathbb C)\) satisfy \(A^T=-A\). Then
Transpose invariance, skew symmetry, and the determinant of a negated matrix give
Since the complex numbers have characteristic zero, \(\det A=0\).
Let \(I\) be finite and let \(A\in \operatorname {Mat}_I(\mathbb C)\) satisfy \(A^T=-A\) and \(\det A\ne 0\). Then \(|I|\) is even.
If \(|I|\) were odd, Lemma 18.9.1.11 would give \(\det A=0\). Hence \(|I|\) is not odd and is therefore even.
Let \(U\in \operatorname {Mat}_d(\mathbb C)\) be unitary and satisfy \(U^T=-U\). Then \(d\) is even. This is the parity obstruction in [ 16 , Proposition V.2, Case II ] .
The determinant of a unitary matrix is a unit, so it is nonzero. Apply Lemma 18.9.1.12 to \(U\).
Let an MPU in standard form be invariant under complex conjugation. Its standard-form unitaries can be chosen in exactly one of the following two cases. In Case I,
and the choice is unique up to local orthogonal transformations. In Case II,
where
The choice is unique up to local symplectic transformations \(S_x\) satisfying \(S_x^T\Sigma _xS_x=\Sigma _x\). Case II can occur only when \(r\) and \(\ell \) are even.
Let an MPU in the standard form determined by its supplied source datum be invariant under complex conjugation, and suppose every standard-form tensor compared below carries reduced full-support source data. Its standard-form unitaries can be chosen in exactly one of the following two cases. In Case I,
and the choice is unique up to local orthogonal transformations. In Case II,
where
The choice is unique up to local transformations \(S_x\) satisfying \(S_x^T\Sigma _xS_x=\Sigma _x\). Case II can occur only when \(r\) and \(\ell \) are even.
Let \(Y=\begin{pmatrix} 0 & 1 \\ -1 & 0 \end{pmatrix}\) and \(R=\frac{1-i}{2}[\mathbb {1}_4+i(Y\otimes Y)]\), with the two tensor factors in that order. Then
Direct multiplication of the four entries of \(Y\) and the corresponding entries of \(Y\otimes Y\) gives both identities.
In Case II of Proposition 18.9.1.14, one can write
where \(\widetilde u\) and \(\widetilde v\) are orthogonal and
In the admissible Case II of Proposition 18.9.1.15, one can write
where \(\widetilde u\) and \(\widetilde v\) are orthogonal and
Let an MPU be in standard form, with one-site physical space \(\mathbb C^{d_0}\otimes \mathbb C^{d_0}\). Time-reversal symmetry forces \(\operatorname {ind}(\mathcal U)=0\). The MPU satisfies \(U^{(N)}=U^{(N)\dagger }\) for every even \(N\) if and only if there is a unitary \(x\) such that
Under time reversal, the two-site block \(\mathcal U_2\) and its physical-adjoint comparison tensor \(\mathcal U_2^\sharp \) generate the same MPU. The fundamental theorem identifies their source spaces, so their corresponding source-cut ranks agree. Physical adjunction exchanges the two cuts by Theorem 18.4.25. Hence
Definition 18.9.46 therefore gives \(\operatorname {ind}(\mathcal U_2)=0\), and blocking independence gives \(\operatorname {ind}(\mathcal U)=0\).
Apply the two gauge equations of the fundamental theorem to the standard forms of \(\mathcal U_2\) and \(\mathcal U_2^\sharp \). Substituting the second equation into the first gives
Therefore \(y=\pm x^\dagger \), which yields the displayed local relation. Conversely, contract that relation and its adjoint alternately around an even periodic chain.
Let an MPU be in the standard form determined by its supplied source datum. Suppose its one-site tensor \(\mathcal U\), its actual two-site block \(\mathcal U_2\), and the physical-adjoint comparison tensor \(\mathcal U_2^\sharp \) are simple and each carries its own reduced full-support source datum. Write the one-site physical space as \(\mathbb C^{d_0}\otimes \mathbb C^{d_0}\). Time-reversal symmetry then forces \(\operatorname {ind}(\mathcal U)=0\). Under these hypotheses, \(U^{(N)}=U^{(N)\dagger }\) for every even \(N\) if and only if there is a unitary \(x\) such that
Under time reversal, \(\mathcal U_2\) and \(\mathcal U_2^\sharp \) generate the same MPU. Apply the same-tensor converse to each supplied pair; the resulting presentations record the original fixed matrices. Theorem 18.9.32 then identifies their source spaces, so their corresponding source-cut ranks agree. Physical adjunction exchanges the two cuts. Hence
Definition 18.9.47 therefore gives \(\operatorname {ind}(\mathcal U_2)=0\), and blocking independence gives \(\operatorname {ind}(\mathcal U)=0\). Apply Theorem 18.9.32 to the standard forms of \(\mathcal U_2\) and \(\mathcal U_2^\sharp \) and follow the source proof. The converse follows by contracting the displayed local relation around every even periodic chain.
Let an MPU be in standard form, with one-site physical space \(\mathbb C^{d_0}\otimes \mathbb C^{d_0}\). Transposition symmetry forces \(\operatorname {ind}(\mathcal U)=0\). The MPU satisfies \(U^{(N)}=U^{(N)T}\) for every even \(N\) if and only if there are a unitary \(x\) and a phase \(e^{i\phi }\) such that
Under transposition, the two-site block \(\mathcal U_2\) and its transposed comparison tensor \(\mathcal U_2^{\mathsf T}\) generate the same MPU. The fundamental theorem identifies their source spaces, so their corresponding source-cut ranks agree. Swapping the physical input and output indices transposes the first source matrix into the second and therefore exchanges the two ranks. Hence
Thus \(\operatorname {ind}(\mathcal U_2)=0\) by Definition 18.9.46, and blocking independence gives \(\operatorname {ind}(\mathcal U)=0\).
Apply the two gauge equations of the fundamental theorem to the standard forms of \(\mathcal U_2\) and \(\mathcal U_2^{\mathsf T}\). Their compatibility gives \(y=e^{i\phi }x^T\) for some phase \(e^{i\phi }\), which yields the displayed local relation. Conversely, contract that relation around an even periodic chain; the phases cancel pairwise.
Let an MPU be in the standard form determined by its supplied source datum. Suppose its one-site tensor \(\mathcal U\), its actual two-site block \(\mathcal U_2\), and the transposed comparison tensor \(\mathcal U_2^{\mathsf T}\) are simple and each carries its own reduced full-support source datum. Write the one-site physical space as \(\mathbb C^{d_0}\otimes \mathbb C^{d_0}\). Transposition symmetry then forces \(\operatorname {ind}(\mathcal U)=0\). Under these hypotheses, \(U^{(N)}=U^{(N)T}\) for every even \(N\) if and only if there are a unitary \(x\) and a phase \(e^{i\phi }\) such that
Under transposition, \(\mathcal U_2\) and \(\mathcal U_2^{\mathsf T}\) generate the same MPU. Apply the same-tensor converse to each supplied pair; the resulting presentations record the original fixed matrices. Theorem 18.9.32 then identifies their source spaces, so their corresponding source-cut ranks agree. Transposition exchanges the two cuts. Hence
Thus \(\operatorname {ind}(\mathcal U_2)=0\) by Definition 18.9.47, and blocking independence gives \(\operatorname {ind}(\mathcal U)=0\). Apply Theorem 18.9.32 to the standard forms of \(\mathcal U_2\) and \(\mathcal U_2^{\mathsf T}\) and repeat the time-reversal argument, retaining the unrestricted phase \(e^{i\phi }\). The converse follows by contracting the local relation around every even periodic chain.
18.9.2 Equivalence under symmetries
At physical dimension \(d\), a finite-chain operator symmetry \(\mathcal S\) specifies a set \(A\) of applicable chain lengths and, for every length \(N\), a map
An MPO tensor \(\mathcal W\) is invariant under \(\mathcal S\) if
for every \(N\in A\).
A coherent symmetry family supplies an action \(\mathcal S_{d,N}\) for every physical dimension \(d\), with one common set \(A\) of applicable lengths. For an ancilla dimension \(x\), let
where \(R_{d,x,N}\) is the canonical sitewise identification of the \(d\)-dimensional and \(x\)-dimensional configurations. Coherence means
Thus the action on the full enlarged operator algebra is supplied data; it is not obtained by extending its values on operators \(X\otimes I\).
If \(\mathcal U\) is invariant under the \(d\)-dimensional component of a coherent symmetry family, then \(\mathcal U^{(x)}\) is invariant under its \(dx\)-dimensional component.
The finite-chain operator of \(\mathcal U^{(x)}\) is \(\iota _x(U^{(N)})\). Semiconjugacy and invariance of \(U^{(N)}\) give
For a blocking length \(k\), the blocked symmetry has applicable lengths
Its action is obtained by conjugating \(\mathcal S_{d,Nk}\) along the canonical identification \((\mathbb C^{d^k})^{\otimes N}\cong (\mathbb C^d)^{\otimes Nk}\).
If \(\mathcal U\) is invariant under \(\mathcal S\), then its \(k\)-site blocking is invariant under the blocked symmetry.
Let \(R_{d,N,k}\) be the canonical identification from blocked length-\(N\) configurations to unblocked length-\(Nk\) configurations. For \(N\in A_k\), one has \(Nk\in A\) and
The second and final equalities are the inverse reindexing identities, and the third is invariance of \(U^{(Nk)}\) because \(Nk\in A\).
Two canonical-form tensors \(\mathcal U\) and \(\mathcal V\) are strictly equivalent under a symmetry \(\mathcal S\) if they have the same physical dimension and, for some common bond dimension \(D'\) as in Definition 18.9.67, there is a continuous path \(\mathcal W(p)\) of MPU tensors of bond dimension \(D'\) from \(\mathcal U_{\uparrow D'}\) to \(\mathcal V_{\uparrow D'}\), not necessarily in canonical form, such that
for every \(p\in [0,1]\) and every applicable chain length \(N\). When \(\mathcal U\) and \(\mathcal V\) have one bond dimension \(D\), such a path of bond dimension \(D\) from \(\mathcal U\) to \(\mathcal V\) witnesses the relation with \(D'=D\).
Strict equivalence under a symmetry implies strict equivalence.
The same path lies in the larger locus obtained by forgetting invariance under \(\mathcal S\).
Two tensors \(\mathcal U\) and \(\mathcal V\) are strictly equivalent under a symmetry \(\mathcal S\) if they have the same physical dimension and there is a continuous path \(\mathcal W(p)\) of MPU tensors from \(\mathcal U\) to \(\mathcal V\) such that
for every \(p\in [0,1]\) and every chain length \(N\) under consideration. The path need not be in canonical form. The equivalence is admissible if its witnessing path carries an admissible equivalence datum for the actual blocked path tensor and the fixed conjugate, physical-adjoint, transposed, and \(\mathcal S\)-image comparison paths, and if the common blocking length \(m\) of that datum satisfies \(m\leq D^4\).
Let \(\mathcal U\) and \(\mathcal V\) have physical dimensions \(d_a\) and \(d_b\). They are equivalent under a symmetry \(\mathcal S\) if there are a positive blocking length \(k\) and coprime positive ancilla dimensions \(p_a,p_b\) with \(p_ad_a=p_bd_b\) such that \((\mathcal U^{(p_a)})_k\) and \((\mathcal V^{(p_b)})_k\) are strictly equivalent under \(\mathcal S\).
Let \(\mathcal U\) and \(\mathcal V\) have physical dimensions \(d_a\) and \(d_b\). They are coherently equivalent under a dimension-indexed symmetry family \(\mathcal S\) if they are MPUs and there are a positive blocking length \(k\) and coprime positive ancilla dimensions \(p_a,p_b\) with \(p_ad_a=p_bd_b\) such that \((\mathcal U^{(p_a)})_k\) and \((\mathcal V^{(p_b)})_k\) are strictly equivalent under the \(k\)-site blocking of the supplied enlarged-dimension symmetry. The family obeys the identity-ancilla semiconjugacy law, and its applicable blocked lengths are precisely the lengths \(N\) for which \(Nk\in A\). The ancillas are attached before the common blocking.
Equivalence under a coherent symmetry family implies ordinary equivalence after the same ancillas and blocking.
Retain the MPU hypotheses, positive coprime ancilla dimensions, common positive blocking length, and physical-dimension equality from the symmetry-preserving witness. Forgetting invariance from its final strict path gives the required ordinary stabilized equivalence.
Let \(\mathcal U\) and \(\mathcal V\) have physical dimensions \(d_a\) and \(d_b\). They are equivalent under a symmetry \(\mathcal S\) if there are a positive blocking length \(k\) and coprime positive ancilla dimensions \(p_a,p_b\) with \(p_ad_a=p_bd_b\) such that \((\mathcal U^{(p_a)})_k\) and \((\mathcal V^{(p_b)})_k\) are strictly equivalent under \(\mathcal S\). Thus the ancillas are attached before the common blocking. The equivalence is admissible if this strict-equivalence witness carries an admissible equivalence datum for the actual blocked path and the fixed conjugate, physical-adjoint, transposed, and \(\mathcal S\)-image comparison paths, with common blocking length at most \(D^4\).
Two MPUs described by simple tensors are strictly equivalent under \(\mathcal S\) if and only if their standard-form unitaries are joined by continuous families \(\widetilde u(p)\) and \(\widetilde v(p)\) whose generated MPU is invariant under \(\mathcal S\) for every \(p\in [0,1]\).
Fix a positive integer \(m\leq D^4\). The actual \(m\)-site blocked endpoint MPUs \(U_1^{(mN)}\) and \(U_2^{(mN)}\) are admissibly strictly equivalent under \(\mathcal S\) if and only if there are continuous families of unitaries \(\widetilde u(p)\) and \(\widetilde v(p)\) whose endpoints generate \(U_1^{(mN)}\) and \(U_2^{(mN)}\), whose generated MPU is invariant under \(\mathcal S\) for every \(p\in [0,1]\), and whose tensor path and fixed conjugate, physical-adjoint, transposed, and \(\mathcal S\)-image comparison paths carry continuously varying reduced full-support source data. These families arise from the actual blocked path \(\mathcal W(p)_m\) in an admissible equivalence datum of common length \(m\); the blocked path itself is the length-one admissible witness for the displayed endpoint families, corresponding to [ 16 , Lemma following the symmetry-equivalence definitions ] .
Suppose that either \(r\) or \(\ell \) is odd. Two conjugation-invariant MPUs \(\mathcal U_1\) and \(\mathcal U_2\) are strictly equivalent under conjugation if and only if
For \(i=1,2\), suppose the original one-site endpoint tensor \(\mathcal U_i\) and its conjugate comparison tensor are simple and each carries reduced full-support source data. Suppose that either \(r\) or \(\ell \) is odd and that the standard-form interpolation determined below carries an admissible path datum of blocking length one. Then \(\mathcal U_1\) and \(\mathcal U_2\) are admissibly strictly equivalent under conjugation symmetry if and only if
If either \(r\) or \(\ell \) is odd, all conjugation-invariant MPUs with these source ranks are equivalent under conjugation symmetry.
For \(i=1,2\), suppose the endpoint tensor \(\mathcal U_i\), its conjugate comparison \(\overline{\mathcal U_i}\), the actual two-site block \(\mathcal U_{i,2}\), and its conjugate comparison \(\overline{\mathcal U_{i,2}}\) are simple and each carries reduced full-support source data. Suppose that either \(r\) or \(\ell \) is odd and that the resulting standard-form interpolation carries an admissible path datum of blocking length one. Then \(\mathcal U_1\) and \(\mathcal U_2\) are admissibly equivalent under conjugation symmetry.
Let \(O\) and \(O'\) be orthogonal matrices over a commutative ring, indexed by finite sets of cardinalities \(m\) and \(n\). For every even integer \(k\geq 0\), \(\det (O)^k=1\). Over an integral domain one also has \(\det (O)\in \{ 1,-1\} \). If \(m\) and \(n\) are even, then
These identities give the orthogonal determinant calculation in [ 16 ] .
Taking determinants in \(OO^T=\mathbb {1}\) gives \(\det (O)^2=1\), and the same holds for \(O'\). The determinant of a Kronecker product is \(\det (O)^n\det (O')^m\); both powers are one when \(m\) and \(n\) are even.
Let \(S\) and \(S'\) preserve the standard symplectic forms on spaces of dimensions \(2p\) and \(2q\) over a commutative ring. Then
No positivity assumption on either dimension is needed. This theorem uses the standard symplectic form; the interleaved form in [ 16 ] requires a separate change of coordinates before this calculation applies to its matrices.
Each symplectic determinant equals one. Apply the Kronecker determinant formula.
Suppose \(r\) and \(\ell \) are even. Two conjugation-invariant MPUs in the standard forms of Proposition 18.9.1.14 are strictly equivalent under conjugation if and only if they belong to the same case and
Suppose that \(r\) and \(\ell \) are both even and that the standard-form interpolation determined below carries an admissible path datum of blocking length one. Choose standard forms from the supplied source data of two conjugation-invariant MPUs as in Proposition 18.9.1.15. They are admissibly strictly equivalent under conjugation symmetry if and only if they belong to the same case of Proposition 18.9.1.15 and
Two conjugation-invariant MPUs are equivalent under conjugation symmetry if and only if they belong to the same case of Proposition 18.9.1.14.
For \(i=1,2\), suppose the original one-site endpoint tensor \(\mathcal U_i\), its conjugate comparison \(\overline{\mathcal U_i}\), the actual two-site block \(\mathcal U_{i,2}\), and its conjugate comparison \(\overline{\mathcal U_{i,2}}\) are simple and each carries reduced full-support source data. Suppose also that the resulting standard-form interpolation carries an admissible path datum of blocking length one. Then \(\mathcal U_1\) and \(\mathcal U_2\) are admissibly equivalent under conjugation symmetry if and only if they belong to the same case of Proposition 18.9.1.15.
Suppose first that either \(r\) or \(\ell \) is odd. Then both original endpoints lie in Case I. After one blocking, write \(r^{(2)}\) and \(\ell ^{(2)}\) for the blocked source ranks. Admissible blocking independence, applied to the supplied one-site and two-site endpoint data, gives
and
For each endpoint,
Blocking preserves Case I. If either \(r^{(2)}\) or \(\ell ^{(2)}\) is odd, the odd-rank theorem applied to the blocked endpoints gives admissible strict equivalence. If both blocked ranks are even, then \(d\) is even because one original source rank is odd. Hence \(r\ell =d^2\) is even. Consequently,
and
The even-rank theorem now applies to the preserved Case I endpoints. Thus the odd-source-rank branch has a single admissible equivalence class without imposing a parity condition on the blocked ranks.
If \(r\) and \(\ell \) are both even, admissible blocking independence shows that the blocked ranks remain even. Since \(r\ell \) is even, the same calculations give
and
Blocking preserves Case I and Case II. The even-rank theorem therefore shows that the blocked endpoints are admissibly strictly equivalent exactly when they belong to the same case. This is precisely admissible equivalence of the original endpoints.
For matrices \(A,B\in \mathbb C^{n\times n}\) and the exchange matrix \(\mathbb S\) on \(\mathbb C^n\otimes \mathbb C^n\),
In particular, if \(U\) is unitary, then
In product coordinates, the exchange matrix has entries \(\mathbb S_{(i,j),(k,l)}=\delta _{i,l}\delta _{j,k}\). Therefore
Taking \(A=U\) and \(B=U^\dagger \) gives \(\operatorname{tr}(UU^\dagger )=\operatorname{tr}(\mathbb {1})=n\).
For matrices \(A,B\in \mathbb C^{n\times n}\) and the exchange matrix \(\mathbb S\) on \(\mathbb C^n\otimes \mathbb C^n\),
The equivalent two-sided exchange identity is stated in [ 16 , lines 1316–1319 ] ; the gauge-invariance argument at [ 16 , lines 1624–1630 ] uses it without a printed derivation.
In product coordinates the exchange matrix has entries \(\mathbb S_{(i,j),(k,l)}=\delta _{i,l}\delta _{j,k}\), so both sides of (685) have entry
Swapping factors \(A\) and \(B\) gives (686).
Let \(x\in \mathbb C^{n\times n}\) be unitary, let \(\sigma \in \mathbb C\), and let \(M=\sigma \, x\otimes x^\dagger \). Then
This is the exchange-trace evaluation in [ 16 , lines 1608–1610 ] ; there \(n=d^2\).
The trace is linear, so \(\operatorname{tr}[\mathbb SM]=\sigma \operatorname{tr}[\mathbb S(x\otimes x^\dagger )]\), and Lemma 18.9.2.25 evaluates the remaining contraction as \(n\).
For a time-reversal-invariant MPU in standard form, the sign \(\sigma \) of Proposition 18.9.1.19 is
where \(\mathbb S_{12,34}\) exchanges the pairs of sites \(12\) and \(34\).
For a time-reversal-invariant MPU in the standard form determined by its supplied source datum, suppose its one-site tensor \(\mathcal U\), its actual two-site block \(\mathcal U_2\), and the physical-adjoint comparison tensor \(\mathcal U_2^\sharp \) are simple and each carries its own reduced full-support source datum. Then the sign \(\sigma \) in Proposition 18.9.1.20 is
where \(\mathbb S_{12,34}\) exchanges the pairs of sites \(12\) and \(34\).
Let \(u,v\in \operatorname {End}(\mathbb {C}^d\otimes \mathbb {C}^d)\) and let \(x,y\in U(d)\). Set
The four-site trace is unchanged:
In particular, the trace expression in (18.9.2.28) is invariant under the standard-form gauge.
Write \(x_i\) and \(y_i\) for the unitaries acting on site \(i\). Then \(u'_{12}=x_1y_2u_{12}\), \(u'_{34}=x_3y_4u_{34}\), and \(v'_{23}=v_{23}y_2^\dagger x_3^\dagger \). Cancellation of \(y_2^\dagger y_2\) and \(x_3^\dagger x_3\) gives \(v'_{23}u'_{12}u'_{34}v'_{23} =x_1y_4v_{23}u_{12}u_{34}v_{23}y_2^\dagger x_3^\dagger \), since the outer-leg operators commute with \(v_{23}\). The identity \(\mathbb S_{12,34}x_1y_4=x_3y_2\mathbb S_{12,34}\) then gives
The last equality follows from cyclicity of the trace and unitarity of \(x\) and \(y\).
Under the hypotheses of Lemma 18.9.2.29, let \(x\) and \(y\) be unitaries and change the standard-form gauge by
Then the trace formula has the same value for \((u',v')\) as for \((u,v)\). Consequently the sign \(\sigma \) is independent of the standard-form gauge.
Write \(x_i\) and \(y_i\) for the unitaries acting on site \(i\). Then \(u'_{12}=x_1y_2u_{12}\), \(u'_{34}=x_3y_4u_{34}\), and \(v'_{23}=v_{23}y_2^\dagger x_3^\dagger \). Substitution into Lemma 18.9.2.29, cancellation on the middle legs, and \(\mathbb S_{12,34}x_1y_4=x_3y_2\mathbb S_{12,34}\) give
The last equality follows from cyclicity of the trace and unitarity of \(x\) and \(y\).
For a time-reversal-invariant MPU in standard form, the sign \(\sigma =\pm 1\) is independent of the gauge and is constant under continuous deformations that preserve time-reversal symmetry.
Suppose a time-reversal-preserving path carries an admissible equivalence datum of blocking length one. At every path point, require the one-site tensor, its actual two-site block, and the physical-adjoint comparison of that two-site block to be simple and to carry continuously varying reduced full-support source data. Then the sign \(\sigma =\pm 1\) is independent of the admissible standard-form gauge and is constant along the path.
Let \(\sigma ^{(1)},\sigma ^{(2)}\in \{ 1,-1\} \) and put \(\zeta =\sigma ^{(1)}\sigma ^{(2)}\). For every \(k\geq 1\),
This is the scalar conclusion of [ 16 , lines 1687 and 1730–1732 ] .
Both signs square to one, hence \(\zeta ^2=1\). For odd \(k\) the exponent \(k-1\) is even, so \(\zeta ^{k-1}=1\) and the product is \(\sigma ^{(1)}\). For even \(k\geq 2\) the exponent \(k-1\) is odd, so \(\zeta ^{k-1}=\zeta \) and the product is \((\sigma ^{(1)})^2\sigma ^{(2)}=\sigma ^{(2)}\).
Let \(\mathcal U\) be a time-reversal-invariant MPU in standard form, and let \(\sigma ^{(k)}\) be the sign obtained from a standard form of its \(k\)-site block. Then
Gauge invariance permits the standard blocked representatives used in the source proof. Choose
and put \(\zeta =\sigma ^{(2)}/\sigma ^{(1)}\). The one- and two-site local time-reversal relations give the unwinding identity
Applying this identity successively through a block of length \(k\) gives
Since each sign is \(\pm 1\), this equals \(\sigma ^{(1)}\) for odd \(k\) and \(\sigma ^{(2)}\) for even \(k\).
For every blocking length \(k\) under consideration, suppose the endpoint tensor \(\mathcal U_k\), its actual two-site block \(\mathcal U_{2k}\), and the physical-adjoint comparison tensor \(\mathcal U_{2k}^\sharp \) are simple and each carries its own reduced full-support source datum. Let \(\sigma ^{(k)}\) be the sign of the resulting standard form. Then
Gauge invariance permits the standard blocked representatives used in the source proof. Choose
and put \(\zeta =\sigma ^{(2)}/\sigma ^{(1)}\). The one- and two-site local time-reversal relations give the unwinding identity
Applying this identity successively through a block of length \(k\) gives
Since each sign is \(\pm 1\), this equals \(\sigma ^{(1)}\) for odd \(k\) and \(\sigma ^{(2)}\) for even \(k\).
Strictly equivalent time-reversal-invariant MPUs have the same \(\sigma ^{(1)}\) and \(\sigma ^{(2)}\). Equivalent time-reversal-invariant MPUs have the same \(\sigma ^{(2)}\).
Let two time-reversal-invariant MPUs be compared by an admissible symmetry path \(p\mapsto \mathcal W(p)\) whose path datum has blocking length one. Suppose that the five path families \(\mathcal W(p)\), \(\mathcal W(p)_2\), \(\mathcal W(p)_4\), \(\mathcal W(p)_2^\sharp \), and \(\mathcal W(p)_4^\sharp \) are simple and carry continuously varying reduced full-support source data. Then admissible strict equivalence requires equality of both \(\sigma ^{(1)}\) and \(\sigma ^{(2)}\).
For admissible equivalence after adjoining ancillas and applying the source blocking, let \(p\mapsto \mathcal W_{\mathrm{anc}}(p)\) be the actual ancilla-enlarged blocked witness path, not a reduced or equivalent representative, and regard it as a length-one admissible path. Require continuous reduced full-support source data along \(\mathcal W_{\mathrm{anc}}(p)\), its actual two- and four-site blocks, and the physical-adjoint comparisons of those two blocks. The conclusion is only
No equality between \(\sigma ^{(2)}\) of the original two MPUs is asserted. Such a conclusion requires preservation under adjoining identity ancillas, which is not established here.
For a conjugation-invariant MPU, the MPS sign \(G\overline G=\pm \mathbb {1}\) agrees with Case I and Case II, respectively, of Proposition 18.9.1.14.
Let \(\mathcal U\) be conjugation invariant. Suppose \(\mathcal U\) and its conjugate comparison tensor are simple and carry their own reduced full-support source data. Let \(p\mapsto \mathcal W(p)\) be the actual standard-form interpolation from \(\mathcal U\) to its Case I or Case II representative. Suppose this interpolation carries an admissible conjugation-symmetry path datum of blocking length one: the path \(\mathcal W(p)\) and its fixed conjugate, physical-adjoint, transposed, and conjugation-image comparison paths are simple and carry continuously varying source data. Then the sign \(G\overline G=\pm \mathbb {1}\) in the MPS classification agrees with Case I and Case II, respectively, of Proposition 18.9.1.15.
For a time-reversal-invariant MPU in standard form, the MPS sign \(G\overline G=\pm \mathbb {1}\) equals the sign \(\sigma ^{(2)}\) obtained after blocking two sites.
Let an MPU in the standard form determined by its supplied source datum be invariant under time reversal. Suppose \(\mathcal U\), \(\mathcal U_2\), and \(\mathcal U_4\), together with the physical-adjoint comparison tensors \(\mathcal U_2^\sharp \) and \(\mathcal U_4^\sharp \), are simple and each carries its own reduced full-support source datum. Then the MPS sign \(G\overline G=\pm \mathbb {1}\) equals the sign \(\sigma ^{(2)}\).
18.9.3 Symmetry examples
Let \(u_+=v_+=\mathbb {1}_{r\ell }\) and \(u_-=v_-=\operatorname {diag}(-1,1,\ldots ,1)\). If at least one of \(r\) and \(\ell \) is odd, \((u_+,v_+)\) and \((u_+,v_-)\) realize the two classes of Theorem 18.9.2.15. If both are even, the four pairs \((u_\pm ,v_\pm )\) realize the four Case I classes. Multiplying by the matrix \(R\) of Corollary 18.9.1.17 realizes the four Case II classes.
Assume the standard-form tensors displayed below carry reduced full-support source data and that the comparison paths used to classify them carry admissible path data of blocking length one. Let
If at least one of \(r\) and \(\ell \) is odd, the pairs \((u_+,v_+)\) and \((u_+,v_-)\) represent the two classes of Theorem 18.9.2.16. If \(r\) and \(\ell \) are both even, the four pairs \((u_\pm ,v_\pm )\) represent the four Case I classes of Theorem 18.9.2.22. With
the four pairs \((u'_\pm ,v'_\pm )\) represent the four Case II classes.
Let \(u,d,\ell ,r\in \{ 0,1\} \) and set \(P^{ud}_{\ell r}=\delta _{u,1-d}\delta _{u,\ell }2^{-1/2}(-1)^{\ell r}\), the tensor printed in the CZX example of [ 16 ] . In the ordinary periodic trace contraction, the two-site operator generated by \(P\) has all-zero output row
In particular, \(P\) does not generate a matrix product unitary. The normalization discrepancy and comparison with the Z-decorated tensor are detailed in [ 180 ] .
The copy deltas fix both virtual indices to zero. The physical bit flips then force the input to be \(11\), and the two Hadamard entries contribute \(1/2\). If the operator were unitary, its all-zero diagonal entry after multiplication by its adjoint would give
a contradiction.
The normalized Hadamard in the following printed CZX formulas has the obstruction above. In contrast, the blue tensors in the CZX tensor diagram of [ 197 ] are \(\sqrt{2}H\), and this diagram also has a \(Z\) gate on each output qubit. Let \(A=\sqrt2 P\), let \(A_2\) denote its two-site block, and let \(B\) denote that displayed Z-decorated tensor. The output-leg relation is
The literal normalized tensor printed below is not an MPU, by Theorem 18.9.3.3. The following is the source classification claim, not an assertion of unitarity for that literal tensor; its normalization and comparison with the Z-decorated tensor are discussed in [ 180 ] . The CZX MPU of Chen, Liu and Wen [ 11 ] (see also [ 16 , lines 1906–1943 ] ) is defined by
where \(CZ=\operatorname {diag}(1,1,1,-1)\). Let
be the Hadamard matrix. The corresponding tensor is
It has \(\sigma ^{(1)}=\sigma ^{(2)}=-1\).
The literal normalized tensor printed below is not an MPU, by Theorem 18.9.3.3. The classification below evaluates the supplied tensor data under [ 180 ] . Suppose the CZX tensors \(\mathcal U\), \(\mathcal U_2\), and \(\mathcal U_4\), together with the physical-adjoint comparison tensors \(\mathcal U_2^\sharp \) and \(\mathcal U_4^\sharp \), are simple and each carries its own reduced full-support source datum. The CZX MPU of Chen, Liu and Wen [ 11 ] (see also [ 16 , lines 1906–1943 ] ) is defined by
Its tensor is
It has \(\sigma ^{(1)}=\sigma ^{(2)}=-1\).
The standard forms
realize, respectively,
For each displayed example, suppose the tensors \(\mathcal U\), \(\mathcal U_2\), and \(\mathcal U_4\), together with the physical-adjoint comparison tensors \(\mathcal U_2^\sharp \) and \(\mathcal U_4^\sharp \), are simple and each carries its own reduced full-support source datum. The standard forms
realize, respectively,
The right shift on \((\mathbb C^d)^{\otimes N}\) is
It has bond dimension \(d\) and local matrices \(A^{ij}=\lvert i\rangle \langle j\rvert \). The physical adjoint of \(A\) defines the left-shift tensor.
For every \(N{\gt}0\), the tensors in Definition 18.9.3.9 generate \(T^{(N)}\) and \(T^{(N)\dagger }\), respectively. Both tensors are matrix product unitaries.
Closing the virtual indices of \(A^{ij}=\lvert i\rangle \langle j\rvert \) leaves one nonzero virtual configuration. If \(\tau _n=\sigma _{n+1}\) for every \(n\) modulo \(N\), then
Otherwise the same matrix entry is zero. Hence the output configuration is \((\tau _{N-1},\tau _0,\ldots ,\tau _{N-2})\), which fixes the permutation-matrix convention and gives the right shift. Its permutation matrix is unitary. Physical adjunction gives the conjugate transpose, hence the left shift and its unitarity.
Let \(A\) be the right-shift tensor and let \(z_{(\alpha ,i)}=\delta _{\alpha i}\) be the vectorized identity. Its raw source cuts are
For the left-shift tensor \(A^\sharp \) they are
In every physical dimension, including \(d=0\),
If \(d{\gt}0\), the remaining two ranks are
These are the raw source-cut quantities from [ 16 , Section III ] ; no choice of source factors is involved.
The entry formula \(A^{ij}_{\alpha \beta } =\delta _{i\alpha }\delta _{j\beta }\) gives \(M_1(A)=\mathbb {1}\) and \(M_2(A)=zz^{\mathsf T}\). Hence the first rank is \(d^2\). For \(d{\gt}0\), the vector \(z\) has a nonzero diagonal coordinate, so its outer product has rank one. Physical adjunction exchanges the two cuts and their ranks, which gives all four left-shift formulas without a second rank calculation.
Let \(d\in \mathbb {N}\). On \(\mathbb {C}^d\otimes \mathbb {C}^d\), let \(\mathbb S\) be the swap operator used in [ 16 , Section VII ] , defined on the standard basis by \(\mathbb S(e_k\otimes e_\ell )=e_\ell \otimes e_k\). With columns indexed by source coordinates \((k,\ell )\) and rows indexed by target coordinates \((i,j)\), its entries are
Then \(\mathbb S\) is unitary between the two product-coordinate orders:
The swap operator is self-adjoint and involutive, so \(\mathbb S^\dagger =\mathbb S\) and \(\mathbb S^2=\mathbb {1}\). Substitution gives both identities.
On two \(d\)-dimensional spins per site, define
For \(d\geq 1\) the tensors \(U_2=T^\dagger \otimes T\) and \(U_3=T\otimes T^\dagger \) are in canonical form and strictly equivalent, with no bond directions adjoined. Conjugating the physical legs of a tensor by a unitary, or its bond space by a unitary, preserves the matrix product unitary property.
The letter of \(U_3\) at the exchanged physical indices is the letter of \(U_2\) conjugated on the bond by the factor exchange \(\mathbb S\). Let \(\mathbb S(x)\), \(x\in [0,1]\), be the continuous unitary path from the identity to \(\mathbb S\). The path \(x\mapsto \mathbb S(x)\) acting on the physical legs of \(U_2\) ends at \(U_2\) with its two spins exchanged; the path \(x\mapsto \mathbb S(x)(\cdot )\mathbb S(x)^\dagger \) on the bond space then ends at \(U_3\). Every point generates matrix product unitaries, since \(\mathbb S(x)^{\otimes N}U^{(N)}\mathbb S(x)^{\dagger \otimes N}\) is unitary and bond conjugation changes no operator. Canonical form of the endpoints: the shift is in canonical form II, so are its physical adjoint and the tensor products, hence they are in canonical form.
Canonical form II requires the positive right fixed point \(\rho \) to have trace one. If the virtual weight on the bond space of a single shift is chosen to be a scalar identity, this normalization forces
whenever \(d{\gt}0\). The same formula is defined at \(d=0\), although it then has trace zero. The tensors \(U_2\) and \(U_3\) have bond dimension \(d^2\), so the corresponding scalar trace-one matrix is
These are the scalar identity choices compatible with the source weight in [ 16 , equation labelled Y1Y1X1X1 ] . No transfer-map fixed-point equation is asserted here.
The supplied source-factor witnesses below instead use \(\rho _{\mathrm{aux}}=\mathbb {1}_d\) for each constituent shift and \(\rho _{\mathrm{aux}}=\mathbb {1}_{d^2}\) after tensoring. The paper gates computed from them carry reciprocal factors \(d\) and \(d^{-1}\) because these identity weights differ from \(\rho _d\) and \(\rho _{d^2}\) when \(d{\gt}1\).
For every \(d\in \mathbb N\), the matrix \(\rho _d\) is positive semidefinite. If \(d{\gt}0\), then \(\rho _d\) is positive definite and
Under the same hypothesis, \(\rho _{d^2}\) is positive definite with trace one; it is positive semidefinite for every \(d\).
The scalar \(d^{-1}\) is nonnegative, and it is strictly positive when \(d{\gt}0\). Hence the claims follow from positivity of the identity matrix. For positive \(d\),
Replacing \(d\) by \(d^2\) proves the product-space statements.
Assume \(d{\gt}0\), and let \(T\) be the right-shift tensor. Starting from the displayed source factors for \(T\) with identity weight, rescale the first cut by
and leave \(X_2,Y_2,Z_2\) unchanged. Then these are supplied source factors for the trace-normalized scalar weight \(\rho _d=d^{-1}\mathbb {1}_d\) prescribed by CFII. In particular,
This gives the source-factor metric normalization of [ 16 , equations Erightleft, X1X2b, and YZ=1 ] for the right shift.
Assume \(d{\gt}0\). Identify the unique left source coordinate with \(0\) and the right source coordinate with \((a,b)\). For the trace-normalized source factors of the right shift,
Hence
This fixes the order and normalization of the two triangles in [ 16 , equations uu and uUnitary ] for this basic MPU. It is the explicit normalization and orientation regression for Theorem 18.9.4 and Lemma 18.9.11.
For the identity-weight factors, direct substitution in \(u=Y_2\mathbin {-}Y_1\) gives
The trace-normalized first cut replaces \(Y_1\) by \(d^{-1/2}Y_1\) and leaves \(Y_2\) unchanged. Therefore
Summing the product of two such entries over \((a,b)\) gives \(\delta _{p,q}\), which is the entrywise identity \(u^\dagger u=\mathbb {1}\).
Write \([U_a]^{(i_1,i_2),(j_1,j_2)}\) for the virtual matrix of the one-site tensor \(U_a\) with physical output coordinate \((i_1,i_2)\) and input coordinate \((j_1,j_2)\). Let \(\mathbb S\) be the SWAP matrix on the two virtual factors, defined by
Then
Thus exchanging the two physical species exchanges the local tensors \(U_2\) and \(U_3\), with the same exchange on their virtual factors.
In virtual coordinates \((\alpha _1,\alpha _2)\) and \((\beta _1,\beta _2)\), multiplication by \(\mathbb S\) on both sides selects the entry with row \((\alpha _2,\alpha _1)\) and column \((\beta _2,\beta _1)\). Consequently,
This is exactly the entrywise form of conjugation by \(\mathbb S\).
The three tensors generate the operators displayed in Definition 18.9.3.13 on every nonempty chain, and each tensor is a matrix product unitary.
The bond-one identity tensor generates the identity at every length. The finite-chain operator of an independent tensor product is the Kronecker product of the two finite-chain operators, after the sitewise identification \((\mathbb C^d\otimes \mathbb C^d)^{\otimes N} \cong (\mathbb C^d)^{\otimes N}\otimes (\mathbb C^d)^{\otimes N}\). Applying this identity to the right and left shifts gives the three displayed formulas. The identity tensor is unitary, and tensor products preserve unitarity, so all three tensors are matrix product unitaries.
Assume \(d{\gt}0\). For the displayed right- and left-shift tensors \(T\) and \(T^\sharp \), the specified-tensor values are
Likewise,
The bond-one identity tensor and the three tensors \(U_1,U_2,U_3\) satisfy
Here \(\operatorname {ind}_{\mathrm{src}}\) is the specified-tensor quantity from Definition 18.9.42, evaluated on the displayed unblocked tensors. It is not the public MPU index \(\operatorname {ind}\) of Definition 18.9.46, whose definition uses a simple blocking and requires independence of that choice. The public index values follow in Theorem 18.9.3.22.
The right shift has source ranks \((d^2,1)\), while the left shift has \((1,d^2)\). Substitution into the source-index expression gives the first two formulas. The identity tensor has equal source ranks \((d,d)\). Source ranks multiply under the independent tensor product, so each of \(U_1,U_2,U_3\) has equal right and left rank \(d^2\). Their logarithmic differences therefore vanish.
Let \(d{\gt}0\). The right shift is in canonical form II in its original bond coordinates, with ambient right fixed matrix \(\rho =I/d\). The right and left shifts and the three two-spin families satisfy
These are the blocking-independent indices of the families in Definition 18.9.3.13, as asserted in [ 16 ] .
The normalized transfer map of the right shift sends \(X\) to \(\operatorname {tr}(X)I/d\). Its positive diagonal fixed matrix \(I/d\) gives a canonical-form-II presentation. The source-rank computation therefore yields the public index \(\log _2 d\). Physical adjunction negates this index, giving the left-shift value. The identity has index zero, and additivity under the tensor product gives all three remaining values.
Let \(d{\gt}0\). The bond-one tensor generating the identity operator has a canonical-form-II presentation with fixed matrix \(\rho =1\). For every canonical-form-II presentation of this tensor,
This follows from the index definition of [ 16 , Definition IV.1 ] ; it is distinct from the source’s later examples of three two-spin tensors with vanishing index.
In bond dimension one the normalized transfer matrix is the identity; the positive fixed matrix \(\rho =1\) therefore gives a canonical-form-II presentation. Both source ranks of the identity tensor equal \(d\), so the source-gate criterion makes it simple. Blocking once only relabels the physical alphabet. The defining logarithmic difference for any canonical-form-II presentation is consequently \(\frac12(\log _2d-\log _2d)=0\).
Assume \(d{\gt}0\) and let \(k\ge 0\). The right-shift tensor \(T\) and the left-shift tensor \(T^\sharp \) are simple, and so are their blockings \(T_{k+1}\) and \(T^\sharp _{k+1}\) over \(k+1\) sites. The blocked letters are
and the source ranks are
Both source ranks of the blockings of \(U_2\) and \(U_3\) equal \(d^{2k+2}\). Consequently
and the blockings of \(U_2\) and \(U_3\) have value zero. If \(d{\gt}1\), then \(r(T_{k+1})\ne \ell (T_{k+1})\) and \(\operatorname {ind}_{\mathrm{src}}(T_{k+1})\ne 0\).
The tensors \(U_1\), \(U_2\), and \(U_3\) are simple, and so are the blockings of \(U_2\) and \(U_3\) over \(k+1\) sites, because independent tensor products of simple tensors are simple. Thus all four values are taken at simple blockings, which is the simplicity requirement of Definition 18.9.46. The canonical-form construction and representative invariance in Theorem 18.9.3.22 identify these values with the public indices and transport them to any positive-dimensional MPU generating the same periodic operators. Unequal ranks do not by themselves exclude a circuit: after blocking, every matrix product unitary, the shift included, is a depth-two circuit of nearest-neighbour unitaries in its standard form. The statement that the shift is not a finite-depth circuit of local gates needs parts (ii)–(iv) of Theorem 18.9.111 together with index zero for one layer of nearest-neighbour gates, and is not asserted here.
With \(\Phi =\sum _j|jj)\), the double-layer letters of \(T\) are \(|\Phi )(ik|\), so the boundary vectors \(|00)\) and \(\Phi \) satisfy both simplicity identities; for \(T^\sharp \) the letters are \(|ik)(\Phi |\) and the boundary vectors are exchanged. The identity tensor has bond dimension one and double-layer letters \(\delta _{ij}\), so \(a=b=1\) are boundary vectors. Simplicity survives independent tensor products and blocking, which gives simplicity of \(U_1\), \(U_2\), \(U_3\) and of the blockings of \(U_2\) and \(U_3\). A product of matrix units \(|\sigma _m)(\tau _m|\) is \(|\sigma _0)(\tau _k|\) when adjacent indices match and zero otherwise, which gives the blocked letters. The first source cut of \(T_{k+1}\) sends the row \((\sigma ,\beta )\) to the single column \((\sigma _0,\ \sigma _1\cdots \sigma _k\beta )\); this is a bijection, so the cut is a permutation matrix of rank \(d^{k+2}\). The second source cut factors through the \(d^k\) middle words \(\sigma _1\cdots \sigma _k\), and its rows \((0,0y)\) and columns \((y0,0)\) form an identity minor of size \(d^k\). Physical adjunction exchanges the two ranks, and ranks multiply under tensor products and are unchanged by physical reindexing. Substituting into the source-index expression gives \(\frac12\bigl((k+2)-k\bigr)\log _2 d=\log _2 d\) and the remaining values. For \(d{\gt}1\) the powers \(d^{k+2}\) and \(d^k\) differ.
Assume \(d{\gt}0\). Equip \(U_1\) with the tensor product of the two bond-one identity source factorizations. Equip \(U_2\) with the tensor product of the left-shift and right-shift source factorizations, in that order, and equip \(U_3\) with the tensor product in the reverse order. In all three cases the virtual weight is the identity. These are explicit supplied source-factor witnesses; no identification with an arbitrary compact singular-value decomposition is asserted.
Let \(\mathbb S\) exchange two \(d\)-dimensional spins. The two swap factors appearing in the blocked forms of \(U_2\) and \(U_3\), and both ordered products, are unitary:
The swap is unitary by Theorem 18.9.3.12. Kronecker products preserve isometries, and a square isometry is unitary. Thus both factors are unitary. Closure of the unitary matrices under multiplication gives the two ordered products.
In the four-spin coordinates of the supplied source factorization,
The tensor-product formulas for \(u=Y_2\mathbin {-}Y_1\) and \(v=X_1\mathbin {-}X_2\) reduce each entry to the product of two primitive identity entries.
Assume \(d{\gt}0\). In the four-spin coordinates of the paper, the supplied source gates satisfy
The blocked tensor factors through \(X_2,u_2^{(2)},X_1\) and, equivalently, through \(v_2^{(2)},Y_1,Y_2\). The scalar factors record the normalization of the supplied source-factor witnesses.
The tensor-product formulas for the paper gates reduce their entries to products of the left- and right-shift source gates. The Kronecker deltas give the two displayed swap matrices, with the factors \(d\) and \(d^{-1}\) fixed by the identity-weight normalization. Substitute these evaluations into the two exact open source-gate factorizations.
Assume \(d{\gt}0\). In the four-spin coordinates of the paper, the supplied source gates satisfy
The blocked tensor factors through \(X_2,u_3^{(2)},X_1\) and, equivalently, through \(v_3^{(2)},Y_1,Y_2\). The scalar factors record the normalization of the supplied source-factor witnesses.
Reverse the two primitive shift factors in the tensor-product formulas for \(u\) and \(v\). Their Kronecker deltas give the displayed ordered swap products, with the factors \(d\) and \(d^{-1}\) fixed by the identity-weight normalization. Substitute these evaluations into the two exact open source-gate factorizations.
For \(d{\gt}0\), the two counterpropagating shift tensors have source factors with trace-one weight \(\rho =d^{-2}\mathbb {1}_{d^2}\). In the four-spin coordinates used above, their source gates are
Starting with the identity-weight source factors, replace \(X_1,Y_1,Z_1\) by \(dX_1,d^{-1}Y_1,dZ_1\), respectively, and leave the second cut unchanged. The cut factorizations and right inverses are preserved, while the first weighted isometry now uses \(d^{-2}\mathbb {1}_{d^2}\). Writing \(\hat u_k,\hat v_k\) for the identity-weight gates of Theorem 18.9.3.28 and Theorem 18.9.3.29, the source gates rescale as
which cancels the scalar factors in those formulas.
Assume \(d{\gt}0\). The three shift families have two-site decompositions with supplied gates whose unitary gates satisfy
The two-site blockings in the last two lines use the physical order \(((1,2),(3,4))\). These are unitary gates with normalized half factors satisfying the open standard-form equation. For the two blocked families, the half factors and gates are those of the source factors of Theorem 18.9.3.30. For \(U_1\) and the unblocked \(U_3\), the one-site tensor is read as a pair of spins and decomposed directly; these decompositions are not identified with the standard form of Definition 18.9.13 [ 114 ] .
For the identity family, take \(X_1(i,\gamma ;r)=\delta _{i,r}\) and \(X_2(\alpha ,i;\ell )=\delta _{i,\ell }\). For the unblocked third family, take
Its gates are the swap, which is unitary by Theorem 18.9.3.12. The reciprocal scalars cancel in both contractions. Summing the Gram entries proves \(X_1^*(\mathbb {1}\otimes \rho )X_1=\mathbb {1}\) and \(X_2^*X_2=\mathbb {1}\), with \(\rho =d^{-2}\mathbb {1}_{d^2}\) for the third family and \(\rho =1\) for the identity. For the two blocked families, use the trace-normalized source factors of Theorem 18.9.3.30, relabeling the intermediate coordinates by pairs of spin indices. Write \(e_L:\{ 0,\ldots ,d^2-1\} \to L\) and \(e_R:\{ 0,\ldots ,d^2-1\} \to R\) for these bijections, obtained by \(\ell \leftrightarrow (a,b)\) and \(r\leftrightarrow (c,e)\) and the source-factor rank identifications. The open contraction becomes
Thus the source-factor contraction theorem gives the open equation in the displayed coordinates. The four-spin permutation matrices are unitary. The relabeled half factors are \(\widehat X_1(i,\gamma ;r)=X_1(i,\gamma ;e_R(r))\) and \(\widehat X_2(\alpha ,i;\ell )=X_2(\alpha ,i;e_L(\ell ))\). Since \(e_R\) and \(e_L\) are injective, the source normalization identities give
Let \(\mathbb S\) exchange the two \(d\)-dimensional spins at one site, with matrix entries
With the row index as the output physical index and the column index as the input physical index, define
Thus the swap acts on the output leg, and the corresponding closed operator is left-multiplied by \(\mathbb S^{\otimes N}\).
On every nonempty chain,
Each transformed tensor is a matrix product unitary.
Acting by a one-site matrix \(P\) on every output physical index gives
Substituting \(P=\mathbb S\) and the three shift formulas gives the stated identities. The swap is a permutation matrix and hence unitary. If \(\mathcal M\) is an MPU, then
Thus the sitewise left action preserves the MPU property.
On every nonempty chain,
This is the conjugacy identity in [ 16 , lines 2059–2062 ] .
Split each physical configuration into its two spin configurations. The three operators are permutation matrices. In these coordinates, \(\mathbb S^{\otimes N}\) exchanges the two configurations, \(U_2^{(N)}\) acts by \((T^{(N)\dagger },T^{(N)})\), and \(U_3^{(N)}\) acts by \((T^{(N)},T^{(N)\dagger })\). Exchanging the two factors on both sides of the second action gives the third, which proves the identity.
For \(d{\gt}0\), the first two transformed families have two-site decompositions with supplied gates and normalized half factors, with gates
The one-site tensors are read as pairs of spins and decomposed directly; these decompositions are not identified with the standard form of Definition 18.9.13 [ 114 ] .
The physical swap exchanges the two output indices of each tensor. For the first family, retain the identity family’s half factors and replace its unshifted gate by the swap. For the second family, choose \(X_1(i,(a,b);r)=\sqrt d\, \delta _{a,i}\delta _{b,r}\) and \(X_2((a,b),i;\ell )=d^{-1/2}\delta _{a,\ell }\delta _{b,i}\). Contracting over the bond index \(\beta =(a,b)\) gives the shifted swap gate,
Inserting the unshifted identity gate \(\mathbb {1}\otimes \mathbb {1}\) between the half factors gives, for \(\alpha =(a,b)\) and \(\gamma =(a',b')\),
which is the entry of \(\widetilde{\mathcal U}_2\) with output \((i_1,i_2)\), input \((j_1,j_2)\), and bond indices \(\alpha ,\gamma \). The swap is unitary by Theorem 18.9.3.12, so both gates are unitary. With \(\rho =d^{-2}\mathbb {1}_{d^2}\), the Gram sums are
since \(d\) pairs \((i,a)\) satisfy \(a=i\) and \(d\) pairs \((b,i)\) satisfy \(b=i\).
On every positive-length chain, the adjunction, transposition, and conjugation actions are \(U\mapsto U^\dagger \), \(U\mapsto U^{\mathsf T}\), and \(U\mapsto \overline U\), respectively. For a site consisting of two \(d\)-dimensional spins, let \(S_N=\mathbb S^{\otimes N}\) be their sitewise exchange. The swap-combined actions are \(U\mapsto S_NU^\dagger S_N\) and \(U\mapsto S_NU^{\mathsf T}S_N\). These are the symmetries of [ 16 , Sections IV.A–IV.C ] .
Let \(\mathcal S,\mathcal T\) have the same applicable chain lengths, and let \(\mathcal U,\mathcal V\) have the same physical and virtual dimensions. Suppose that, for every \(N\geq 0\), \(\mathcal S[U^{(N)}]=U^{(N)}\) if and only if \(\mathcal T[V^{(N)}]=V^{(N)}\). Then \(\mathcal U\) is \(\mathcal S\)-invariant if and only if \(\mathcal V\) is \(\mathcal T\)-invariant.
Restrict the pointwise equivalences to the common set of applicable chain lengths and quantify over that set.
Let \(Q,X\) be complex matrices indexed by the same finite set, and let \(F\) be a map on that matrix space. If \(Q^2=I\) and \(F(QX)=F(X)Q\), then
Replace \(F(QX)\) by \(F(X)Q\) and multiply by \(Q\) on the left. Involutivity gives both implications in (804).
Let \(\mathcal U\) be a local tensor with two \(d\)-dimensional physical spins, and let \(\widetilde{\mathcal U}=\mathbb S\mathcal U\) denote the action on its output physical leg. The swap satisfies \(\mathbb S^2=I\). For every \(N{\gt}0\), \(\widetilde U^{(N)}=S_NU^{(N)}\). Then \(\mathcal U\) is invariant under swap-combined adjunction if and only if \(\widetilde{\mathcal U}\) is invariant under adjunction, \(\mathcal U\) is invariant under swap-combined transposition if and only if \(\widetilde{\mathcal U}\) is invariant under transposition, and \(\mathcal U\) is invariant under conjugation if and only if \(\widetilde{\mathcal U}\) is. The one-sided transformation is the one prescribed by the transformed examples in [ 16 , Section VI.B.1 ] ; the printed proof’s two-sided expression has the local correction recorded in [ 81 ] .
The swap satisfies \(S_N^2=I\), \(S_N^\dagger =S_N^{\mathsf T}=S_N\), and \(\overline{S_N}=S_N\). We show that, for every \(N{\gt}0\),
Substituting \(\widetilde U^{(N)}=S_NU^{(N)}\) and multiplying by \(S_N\) proves (805) and (806). Reality of \(S_N\) proves (807). Since all three symmetries apply at the same chain lengths, the pointwise equivalences give the three equivalences of invariance.
Fix physical and virtual dimensions \(d,D\), and a matrix \(Q\in M_{d}(\mathbb {C})\). The map \(\mathcal U\mapsto Q\mathcal U\), acting on the output physical leg, is continuous on the space of local tensors. If \(Q^2=I\), this map is an involution.
Each tensor entry is a finite linear combination of the original entries. Applying two physical left actions gives \(P(Q\mathcal U)=(PQ)\mathcal U\); hence \(Q^2=I\) gives the involution.
Let \(\mathcal U\) be a canonical-form MPO tensor, and let \(Q\in M_{d}(\mathbb {C})\) be unitary. Then \(Q\mathcal U\), with \(Q\) acting on the physical output, is again in canonical form. Its canonical blocks have the same dimensions and weights, and the same ambient coisometry.
On the doubled physical alphabet, the action is the unitary rotation \(Q\otimes I\). Apply this rotation to every canonical block. It preserves irreducibility and the transfer map, hence its spectral normalization, and distributes over the canonical block decomposition.
Fix \(d\), two finite-chain operator symmetries \(\mathcal S,\mathcal T\), and a unitary \(Q\in M_{d}(\mathbb {C})\) with \(Q^2=I\). Suppose that, for every local tensor \(\mathcal W\) with physical dimension \(d\) and any virtual dimension, \(\mathcal W\) is \(\mathcal S\)-invariant if and only if \(Q\mathcal W\) is \(\mathcal T\)-invariant. Then, for tensors \(\mathcal U,\mathcal V\) of a common virtual dimension, a continuous MPU path of that virtual dimension from \(\mathcal U\) to \(\mathcal V\) with \(\mathcal S\)-invariance exists if and only if such a path from \(Q\mathcal U\) to \(Q\mathcal V\) with \(\mathcal T\)-invariance exists. For tensors \(\mathcal U,\mathcal V\) of possibly different virtual dimensions, strict equivalence under \(\mathcal S\) is equivalent to strict equivalence of \(Q\mathcal U,Q\mathcal V\) under \(\mathcal T\); both relations compare the tensors after unused virtual directions are adjoined up to a common dimension [ 57 ] . Identity-ancilla stabilization is outside the statement [ 65 ] .
If \(p\mapsto \mathcal W(p)\) is the first path, then \(p\mapsto Q\mathcal W(p)\) is continuous and has the required endpoints and symmetry. Its periodic operators are \(Q^{\otimes N}W^{(N)}(p)\) and are unitary. Applying the same involution proves the converse. For strict equivalence, apply this to the paths between the enlarged tensors; the action of \(Q\) commutes with adjoining unused virtual directions. Canonical form is preserved at both endpoints by Theorem 18.9.3.41.
Let \(\mathcal U,\mathcal V\) have two \(d\)-dimensional physical spins, and write \(\widetilde{\mathcal U}=\mathbb S\mathcal U\) and \(\widetilde{\mathcal V}=\mathbb S\mathcal V\). Strict equivalence of \(\mathcal U,\mathcal V\) under swap-combined adjunction is equivalent to strict equivalence of \(\widetilde{\mathcal U},\widetilde{\mathcal V}\) under adjunction. The analogous equivalence holds for swap-combined transposition and transposition. Strict equivalence under conjugation is preserved. Identity-ancilla stabilization is outside this statement [ 65 ] .
For every local MPO tensor \(\mathcal U\), one-site matrix \(Q\), and \(k\geq 0\), output-leg multiplication commutes with blocking:
The identity includes the empty block, with \(Q^{\otimes 0}=1\).
Expand each output-leg action in the ordered product of \(k\) local tensors. The coefficient of an intermediate physical configuration \((r_0,\ldots ,r_{k-1})\) is \(\prod _{n=0}^{k-1} Q_{i_n,r_n}\), which is the corresponding entry of \(Q^{\otimes k}\). Summing over these configurations gives (808).
Fix \(d\), finite-chain operator symmetries \(\mathcal S,\mathcal T\), and a unitary involution \(Q\in M_{d}(\mathbb {C})\). For every \(k{\gt}0\), suppose that every local tensor \(\mathcal W\) of physical dimension \(d^k\) and any virtual dimension is invariant under the blocked symmetry \(\mathcal S^{[k]}\) if and only if \(Q^{\otimes k}\mathcal W\) is invariant under \(\mathcal T^{[k]}\). Then the existence of a common positive blocking length making \(\mathcal U^{[k]},\mathcal V^{[k]}\) strictly equivalent under \(\mathcal S^{[k]}\) is equivalent to the existence of such a length making \((Q\mathcal U)^{[k]},(Q\mathcal V)^{[k]}\) strictly equivalent under \(\mathcal T^{[k]}\). No identity ancillas are included in this comparison [ 65 ] .
Let \(\mathcal U,\mathcal V\) be tensors with two \(d\)-dimensional physical spins. Put \(\widetilde{\mathcal U}=\mathbb S\mathcal U\) and \(\widetilde{\mathcal V}=\mathbb S\mathcal V\). The existence of a positive common blocking length for strict equivalence of \(\mathcal U^{[k]},\mathcal V^{[k]}\) under blocked swap-combined adjunction is equivalent to the existence of such a length for \(\widetilde{\mathcal U}^{[k]},\widetilde{\mathcal V}^{[k]}\) under blocked adjunction. The analogous statements hold for transposition and conjugation. No ancilla enlargement is asserted [ 65 ] .
Blocking identifies the sitewise swap with \(B_N=(\mathbb S^{\otimes k})^{\otimes N}\). Reindexing the original \(Nk\) physical sites preserves adjunction, transposition, and entrywise conjugation, and \(B_N^2=I\), \(B_N^\dagger =B_N^{\mathsf T}=B_N\), and \(\overline{B_N}=B_N\). Hence on every blocked tensor the same one-sided involution gives the three symmetry-invariance correspondences. Apply Theorem 18.9.3.45 with \(Q=\mathbb S\).
Two MPUs \(U_i^{(N)}\) and \(U_j^{(N)}\) are in the same phase under time reversal combined with the local swap, transposition combined with the local swap, or conjugation if and only if the corresponding \(\widetilde U_i^{(N)}\) and \(\widetilde U_j^{(N)}\) are in the same phase under time reversal, transposition, or conjugation, respectively.
Fix one of the three symmetry comparisons and let \(p\mapsto \mathcal W(p)\) be the actual source-constructed interpolation used in that comparison. Suppose it carries an admissible symmetry-path datum of blocking length one. Thus the path \(\mathcal W(p)\) and the four fixed comparison paths \(\overline{\mathcal W(p)}\), \(\mathcal W(p)^\sharp \), \(\mathcal W(p)^{\mathsf T}\), and \(\mathcal S[\mathcal W(p)]\) are simple and carry continuously varying reduced full-support source data. Suppose also that every one- and two-site endpoint tensor used in the local comparison carries its own datum. Then \(U_i^{(N)}\) and \(U_j^{(N)}\) are in the same admissible phase under time reversal combined with the local swap, transposition combined with the local swap, or conjugation if and only if the corresponding \(\widetilde U_i^{(N)}\) and \(\widetilde U_j^{(N)}\) are in the same admissible phase under time reversal, transposition, or conjugation, respectively.
After blocking two sites, \(U_2^{(N)}\) and \(U_3^{(N)}\) are both in the trivial phase under conjugation.
Suppose the two-site blocked tensors carry reduced full-support source data and the standard-form comparison paths carry admissible path data of blocking length one. Then the actual two-site blocked tensors of \(U_2\) and \(U_3\) are both in the trivial admissible strict phase under conjugation. Consequently \(U_2\) and \(U_3\) lie in the same admissible equivalence class.
Let \(\mathbb S\) denote the swap operator on \(\mathbb C^d\otimes \mathbb C^d\). There is a continuous map \(S\colon \mathbb R\to \mathrm{U}(d^2)\) such that
One concrete choice is
where
and
The swap is a self-adjoint involution:
and
Hence the two projections satisfy
and
Since \(\lvert e^{\mathrm{i}\pi x}\rvert =1\), these identities imply
Continuity follows from continuity of the exponential, while \(e^0=1\) and \(e^{\mathrm{i}\pi }=-1\) give the endpoint identities.
The MPUs \(\widetilde U_2^{(N)}\) and \(\widetilde U_3^{(N)}\) are in the same phase under both time reversal and transposition.
For each of time reversal and transposition, let \(p\mapsto \mathcal W_{\mathcal S}(p)\) be the actual source-constructed interpolation from \(\widetilde U_2\) to \(\widetilde U_3\). Suppose it carries an admissible symmetry-path datum of blocking length one. Thus the path \(\mathcal W_{\mathcal S}(p)\) and its fixed conjugate, physical-adjoint, transposed, and \(\mathcal S\)-image comparison paths are simple and carry continuously varying reduced full-support source data. Suppose also that the one- and two-site endpoint tensors used in the local comparison carry their own data. Then \(\widetilde U_2^{(N)}\) and \(\widetilde U_3^{(N)}\) are in the same admissible phase under both time reversal and transposition.
The MPUs \(U_1^{(N)}\) and \(U_2^{(N)}\) lie in different strict conjugation phases exactly when \(d=4k+2\) for a nonnegative integer \(k\). Otherwise they lie in the same strict phase. All these phases are in Case I, so the two MPUs are equivalent after blocking and adjoining ancillas.
For each endpoint tensor \(\mathcal A\) among \(U_1\), \(U_2\), \(\widetilde U_1\), and \(\widetilde U_2\), suppose that \(\mathcal A\), its conjugate comparison \(\overline{\mathcal A}\), its actual two-site block \(\mathcal A_2\), and the conjugate comparison \(\overline{\mathcal A_2}\) are simple and carry their own reduced full-support source data. For every strict comparison used below, let \(p\mapsto \mathcal W(p)\) be the actual source-constructed interpolation between the corresponding endpoint tensors. Suppose it carries an admissible conjugation-symmetry path datum of blocking length one: the path and its fixed conjugate, physical-adjoint, transposed, and conjugation-image comparison paths are simple and carry continuously varying source data. Require a length-one admissible path datum also for the actual blocked interpolation used in the final equivalence claim. Under these hypotheses, \(U_1^{(N)}\) and \(U_2^{(N)}\) are in different admissible strict phases under conjugation exactly when \(k\) is a nonnegative integer and
Otherwise they are in the same admissible strict phase. All these standard forms lie in Case I, so \(U_1^{(N)}\) and \(U_2^{(N)}\) are admissibly equivalent after blocking and adding ancillas.
For a periodic chain of length \(N\), the configuration space consists of triples \(((\sigma _1,\sigma _2),a)\) of two physical configurations and one \(d\)-dimensional ancilla configuration.
The sitewise physical swap is
The sitewise swap of the second species with the ancilla is
Let \(R\) cyclically rotate configurations on the chain. The crossed swap is
Let \(C\) be the permutation obtained by applying \(S^{1,a}_{+}\) first, then \(S^{1,2}\), and finally \(S^{2,a}\).
Define
The literal three-swap circuit satisfies
Writing \(P_f\) for the permutation matrix of \(f\), one also has
At the coordinate level, \(K\) is the configuration map of \(\widetilde U_3\), whereas \(\widetilde U_2\) has configuration map \(((\sigma _1,\sigma _2),a)\mapsto ((R^{-1}\sigma _2,R\sigma _1),a)\). The literal source labels produce a discrepancy at the \(\widetilde U_2\) boundary on a nondegenerate periodic chain; see [ 16 , Figure 16 ] .
Evaluating the three swaps gives
Extensionality gives the permutation equality. The permutation-matrix identity follows by functoriality.
After adding one ancilla of dimension \(d\) per site, \(\widetilde U_1^{(N)}\) and \(\widetilde U_2^{(N)}\) are strictly equivalent under both time reversal and transposition.
After adding one ancilla of dimension \(d\) per site and performing the source blocking, denote the actual enlarged blocked endpoints by \(\widehat{\mathcal U}_1\) and \(\widehat{\mathcal U}_2\). For either time reversal or transposition, let \(p\mapsto \mathcal W_{\mathcal S}(p)\) be the source-constructed interpolation from \(\widehat{\mathcal U}_1\) to \(\widehat{\mathcal U}_2\). Suppose this interpolation carries an admissible symmetry-path datum of blocking length one. Thus the path \(\mathcal W_{\mathcal S}(p)\) and its fixed conjugate, physical-adjoint, transposed, and \(\mathcal S\)-image comparison paths are simple and carry continuously varying reduced full-support source data. Suppose also that the one- and two-site enlarged endpoint tensors used in the local comparison carry their own data. Then \(\widehat{\mathcal U}_1\) and \(\widehat{\mathcal U}_2\) are admissibly strictly equivalent under both time reversal and transposition. No equivalence of the original ancilla-free tensors is asserted, because the equal ancilla dimensions used here need not satisfy the coprimality condition in Definition 18.9.2.12.
18.10 Finite-region observable algebras
Fix a nonnegative integer \(d\). For a finite region \(\Lambda \subset \mathbb Z\), the configuration space and local observable algebra are
The algebra \(\mathcal A_\Lambda \) carries its operator norm. This is the finite-region construction used in the QCA appendix of [ 16 ] ; no completion is taken here.
If \(\Lambda \subseteq \Gamma \) are finite regions, define
Here product configurations are identified with configurations on \(\Gamma \). This is a unital star-algebra homomorphism.
For \(d{\gt}0\), the map \(\iota _{\Lambda ,\Gamma }\) is injective.
Since \(d{\gt}0\), choose a configuration \(c\) on \(\Gamma \setminus \Lambda \). For configurations \(x,y\) on \(\Lambda \),
Hence \(\iota _{\Lambda ,\Gamma }(A)=\iota _{\Lambda ,\Gamma }(B)\) implies \(A=B\).
If \(d{\gt}0\), then for every \(A\in \mathcal A_\Lambda \),
An injective star-algebra homomorphism between complex \(C^*\)-algebras is isometric.
For \(d{\gt}0\), the map \(\iota _{\Lambda ,\Gamma }\) is an operator-norm isometry.
Use injectivity and the general theorem that an injective star-algebra homomorphism between complex \(C^*\)-algebras is an isometry.
For every finite region \(\Lambda \), \(\iota _{\Lambda ,\Lambda }\) is the identity on \(\mathcal A_\Lambda \).
When the two regions agree, their complement is empty. Hence
If \(\Lambda \subseteq \Gamma \subseteq \Delta \), then
The complement decomposes as the disjoint union
Therefore
If \(\Lambda \cap \Gamma =\varnothing \), \(A\in \mathcal A_\Lambda \), and \(B\in \mathcal A_\Gamma \), then their images in the algebra of the union satisfy
This identity provides the local commutativity of disjoint regions in the quasi-local algebra [ 16 , lines 2292–2300 ] .
For configurations \(x,y\) on \(\Lambda \cup \Gamma \), split each intermediate configuration \(z\) into \((z|_\Lambda ,z|_\Gamma )\). The matrix entry of the left-hand side is
Reversing the two factors gives the same scalar product.
Let \(\Lambda \subseteq \Gamma \) be finite regions and \(A\in \mathcal A_\Gamma \). Then \(A\) acts trivially outside \(\Lambda \) if and only if it commutes with the full observable algebra on the complement:
This is a finite-dimensional tensor-factor identity. It is not a statement of Schumacher–Werner or the QCA appendix of [ 16 ] .
Splitting configurations gives \(\mathcal A_\Gamma \cong \mathcal A_\Lambda \otimes \mathcal A_{\Gamma \setminus \Lambda }\). Under this identification, the two inclusions are \(C\mapsto C\otimes \mathbf1\) and \(B\mapsto \mathbf1\otimes B\). Write an arbitrary matrix in blocks indexed by configurations on \(\Lambda \). If it commutes with every \(\mathbf1\otimes B\), each block commutes with the full matrix algebra on \(\Gamma \setminus \Lambda \) and is therefore scalar. Thus the matrix is \(C\otimes \mathbf1\) for some \(C\in \mathcal A_\Lambda \). The converse follows from
18.10.1 Bipartite support algebras
Let \(I\) and \(J\) be finite sets. For \(X\in M_{I\times J}(\mathbb C)\), the existing left coefficient slice and right operator block are the matrices
For a star-subalgebra \(\mathcal D\subseteq M_K(\mathbb C)\), write \(\mathcal D'=\{ Y\in M_K(\mathbb C)\mid [Y,Z]=0\text{ for every }Z\in \mathcal D\} \) for its commutant. The construction below is the full complex matrix-algebra specialization of the coefficient construction in [ 237 , Section 4.3 ] and of the leastness and commutant statements in [ 203 , Lemma 7 ] .
The commutant characterization of [ 203 , Lemma 7 ] requires star-closure [ 237 , lines 1161–1171 ] , as documented in [ 113 ] . For the MPU spin chain, full matrix factors \(\mathcal B_1=M_I(\mathbb C)\) and \(\mathcal B_2=M_J(\mathbb C)\) suffice [ 16 , lines 2320–2334 ] ; see [ 59 ] .
For every \(X\in M_{I\times J}(\mathbb C)\) and \(i,j\in I\),
Compare the \((r,s)\) entries. Both sides equal \(\overline{X((j,s),(i,r))}\).
Let \(\mathcal A\subseteq M_{I\times J}(\mathbb C)\) be a star-subalgebra. Its set of left coefficients is
Let \(\mathcal A\subseteq M_{I\times J}(\mathbb C)\) be a star-subalgebra. Its set of right coefficients is
The left support algebra of \(\mathcal A\) is the star-subalgebra
generated by all left coefficients.
The right support algebra of \(\mathcal A\) is the star-subalgebra
generated by all right coefficients.
If \(X\in \mathcal A\) and \(r,s\in J\), then
The matrix \(X^{\mathrm L}_{rs}\) is one of the generators of the defining star-algebra closure.
If \(X\in \mathcal A\) and \(i,j\in I\), then
The matrix \(X^{\mathrm R}_{ij}\) is one of the generators of the defining star-algebra closure.
For every \(X\in M_{I\times J}(\mathbb C)\),
At the entry \(((i,r),(j,s))\), only the matrix unit \(E_{rs}\) contributes, and its coefficient is \(X^{\mathrm L}_{rs}(i,j)=X((i,r),(j,s))\).
For every \(X\in M_{I\times J}(\mathbb C)\),
At the entry \(((i,r),(j,s))\), only the matrix unit \(E_{ij}\) contributes, and its coefficient is \(X^{\mathrm R}_{ij}(r,s)=X((i,r),(j,s))\).
For every star-subalgebra \(\mathcal B\subseteq M_I(\mathbb C)\),
Use the universal property of the star-subalgebra generated by \(\operatorname {Coeff}_{\mathrm L}(\mathcal A)\).
For every star-subalgebra \(\mathcal C\subseteq M_J(\mathbb C)\),
Use the universal property of the star-subalgebra generated by \(\operatorname {Coeff}_{\mathrm R}(\mathcal A)\).
For submodules \(S\subseteq M_I(\mathbb C)\) and \(T\subseteq M_J(\mathbb C)\), define
This is the tensor-product subspace used below, rather than a conjunction of two one-sided containment conditions.
For \(X\in M_{I\times J}(\mathbb C)\),
For \(A\in S\) and \(B\in T\), direct evaluation gives
Thus the forward implication extends by linearity. Conversely, expand the right blocks in a basis of \(T\). Applying the dual coordinate functionals to those blocks produces matrices in \(S\) from the left-slice hypothesis, and the resulting finite sum reconstructs \(X\) as a sum of Kronecker products from \(S\) and \(T\).
For every star-subalgebra \(\mathcal B\subseteq M_I(\mathbb C)\),
By Theorem 18.10.1.13 with the right submodule the full matrix space, membership in the Kronecker span is exactly membership of every left coefficient in \(\mathcal B\). Apply Theorem 18.10.1.10.
For every star-subalgebra \(\mathcal C\subseteq M_J(\mathbb C)\),
The coefficient criterion reduces the right-hand containment to membership of every right block in \(\mathcal C\). This is equivalent to the left-hand inclusion by Theorem 18.10.1.11.
Every bipartite star-subalgebra satisfies the literal two-sided containment
This is the full complex matrix-algebra specialization of the support-algebra containment in Schumacher–Werner Section 4.3 and of Gross–Nesme–Vogts–Werner equation (22). The latter follows after applying Lemma 7 to both tensor factors. The displayed assertion is an inclusion in an actual tensor-product span, not merely the conjunction of the two one-sided inclusions. The MPU appendix applies this construction to \(\mathcal R_{2x}\) in [ 16 , lines 2320–2334 ] .
If \(X\in \mathcal A\), every left coefficient of \(X\) lies in the left support algebra and every right coefficient lies in the right support algebra. Theorem 18.10.1.13 places \(X\) in their Kronecker-product submodule.
For \(B\in M_I(\mathbb C)\) and \(X\in M_{I\times J}(\mathbb C)\),
For \(i,j\in I\) and \(r,s\in J\), the two product entries are
Equality of the two products is therefore equivalent to \([B,X^{\mathrm L}_{rs}]=0\) for every \(r,s\in J\).
For \(C\in M_J(\mathbb C)\) and \(X\in M_{I\times J}(\mathbb C)\),
For \(i,j\in I\) and \(r,s\in J\), the two product entries are
Equality of the two products is therefore equivalent to \([C,X^{\mathrm R}_{ij}]=0\) for every \(i,j\in I\).
For \(B\in M_I(\mathbb C)\),
Equivalently,
By Theorem 18.10.1.17, commutation of \(B\otimes \mathbf1_J\) with every \(X\in \mathcal A\) is equivalent to commutation of \(B\) with every left coefficient. The coefficient set is closed under adjoints because \(\mathcal A\) is a star-subalgebra. The universal property of the generated star-subalgebra then extends this commutation relation to all of \(\operatorname {Spp}_{\mathrm L}(\mathcal A)\); the converse follows from generator membership.
For \(C\in M_J(\mathbb C)\),
Equivalently,
By Theorem 18.10.1.18, commutation of \(\mathbf1_I\otimes C\) with every \(X\in \mathcal A\) is equivalent to commutation of \(C\) with every right coefficient. Theorem 18.10.1.1 shows that the right coefficient set is closed under adjoints. The universal property of the generated star-subalgebra extends commutation to all of \(\operatorname {Spp}_{\mathrm R}(\mathcal A)\); the converse follows from generator membership.
Let \(I\), \(J\), and \(K\) be finite sets, and let
be star-subalgebras. Suppose that, for every \(X\in \mathcal A_1\) and \(Y\in \mathcal A_2\),
Then the two support algebras on the common factor commute:
This is the full complex matrix-algebra specialization of Schumacher–Werner Lemma sppcomm [ 237 , lines 1174–1194 ] and GNVW Lemma sppcomm [ 203 , Section 7.1, lines 1221–1246 ] .
The input star-subalgebra must be closed under involution, and the basis element belongs to the third factor; see the notes [ 113 ] and [ 82 ] . The statement treats full complex matrix algebras, which suffices for the MPU application [ 16 , lines 2300–2306, 2313–2334 ] ; see [ 59 ] .
For \(X\in \mathcal A_1\), \(Y\in \mathcal A_2\), \(i,i'\in I\), and \(k,k'\in K\), applying Theorem [ 216 , “Middle-factor coefficients of commuting overlapping operators” ] to (875) gives
Applying the same identity to \(Y^\dagger \in \mathcal A_2\), with \(k\) and \(k'\) exchanged, also gives commutation with \((Y^{\mathrm L}_{kk'})^\dagger \). Hence every generator of \(\operatorname {Spp}_{\mathrm R}(\mathcal A_1)\) lies in the star-subalgebra commuting with all left coefficients of \(\mathcal A_2\). Passing to the generated star-subalgebra yields
for every \(R\in \operatorname {Spp}_{\mathrm R}(\mathcal A_1)\) and every left coefficient \(L\) of \(\mathcal A_2\).
Since \(\operatorname {Spp}_{\mathrm R}(\mathcal A_1)\) is closed under adjoints, applying (878) to \(R^\dagger \) shows that each left coefficient commutes with both \(R\) and \(R^\dagger \). Passing to the star-subalgebra generated by the left coefficients gives (876).
18.10.2 Products of commuting matrix factors
Let \(\mathcal C\) be a nonzero complex star-algebra and let \(\mathcal A,\mathcal B\subseteq \mathcal C\) be unital star-subalgebras such that \(ab=ba\) for every \(a\in \mathcal A\) and \(b\in \mathcal B\).
Multiplication defines a unital star-algebra homomorphism
The image of \(\mu _{\mathcal A,\mathcal B}\) is the algebraic join \(\mathcal A\vee \mathcal B\). Its underlying complex vector space is
Thus every element of the join is a finite complex-linear sum of products \(ab\).
The involution reverses products. Since \(a^*\in \mathcal A\) and \(b^*\in \mathcal B\) commute,
The image contains both factors because \(a=a\mathbf1\) and \(b=\mathbf1b\). Conversely, every pure tensor maps to an element of the join, and linearity gives the reverse inclusion. The description of the underlying vector space is the range formula for the linear multiplication map.
Suppose that \(\mathcal C=M_I(\mathbb C)\) for a finite nonempty set \(I\), that \(p,q{\gt}0\), and that
as star-algebras. Then \(\mu _{\mathcal A,\mathcal B}\) is injective and
This is the unital single-block specialization of Schumacher–Werner Proposition Cscom [ 237 , lines 2119–2138 ] , used for the adjacent support algebras in Gross et al. [ 203 , lines 1270–1308 ] ; see [ 110 ] .
The source of the multiplication homomorphism is
This is a simple ring. The kernel of a unital homomorphism from a simple ring to a nonzero ring is not the whole ring, and is therefore zero. Hence multiplication is injective. Its image is the join by Theorem 18.10.2.2; the matrix presentation and dimension formula in Equation (883) follow.
Let \(I,J\) be finite sets, and let \(\mathcal S\subseteq M_I(\mathbb C)\) and \(\mathcal T\subseteq M_J(\mathbb C)\) be unital star-subalgebras. In the canonical bipartite coordinates, the underlying complex vector space of the join of \(\mathcal S\otimes \mathbf1_J\) and \(\mathbf1_I\otimes \mathcal T\) is exactly
If \(I\) or \(J\) is empty, the ambient matrix space is zero, so both subspaces in the claimed equality are zero. Assume that both sets are nonempty. The two canonical factors commute, and their products satisfy
For a finite region \(\Lambda \subset \mathbb Z\) and \(a\in \mathbb Z\), define
Thus
If \(\Lambda \subseteq \Gamma \), then \(\Lambda +a\subseteq \Gamma +a\).
For finite regions \(\Lambda ,\mathcal N\subset \mathbb Z\), define their sumset by
Hence \(j\in \Lambda +\mathcal N\) exactly when \(j=i+a\) for some \(i\in \Lambda \) and \(a\in \mathcal N\). The sumset is monotone in both arguments, and the singleton \(\{ 0\} \) is an identity. A singleton displacement recovers translation,
Sumsets are associative:
These identities support composition of propagation bounds. This is the finite region \(\Lambda +\mathcal N\) in the propagation condition of the QCA appendix of [ 16 ] .
Translation gives bijections
Their inverses translate sites and configurations by \(-a\).
Relabelling configurations defines a star-algebra equivalence
This is the finite-region translation associated with the lattice translation \(i\mapsto i+a\).
Let \(d\) be a nonnegative integer, let \(\Lambda \subset \mathbb Z\) be finite, and let \(a\in \mathbb Z\). For every \(A\in \mathcal A_\Lambda \),
Consequently, \(\tau _{a,\Lambda }\) is an isometry from \(\mathcal A_\Lambda \) onto \(\mathcal A_{\Lambda +a}\).
Translation bijectively relabels the configuration basis. The resulting star-algebra equivalence between the two finite matrix algebras preserves the operator norm. Applying this identity to \(A-B\) and using linearity gives
so distances are preserved.
Translation by zero acts trivially on sites, configurations, and finite-region observables. Successive translations by \(a\) and \(b\) agree with translation by \(a+b\). Pointwise, for \(i\in \Lambda \), \(x,y\in \operatorname {Config}_d(\Lambda )\), and \(A\in \mathcal A_\Lambda \),
These identities express the additive action without identifying the distinct configuration spaces before applying their canonical translation bijections.
The site identities follow from
Relabelling a configuration is precomposition by the inverse site translation, so evaluation at the corresponding translated site gives
Applying this identity successively proves the configuration action laws. Finally, the local observable translation relabels both matrix indices by \(T_{a,\Lambda }^{-1}\); evaluating on translated configurations therefore gives \(A(x,y)\), and applying this entrywise identity successively proves the local observable action laws.
If \(\Lambda \subseteq \Gamma \), then for every \(A\in \mathcal A_\Lambda \),
The lattice translation identifies \(\Gamma \setminus \Lambda \) with \((\Gamma +a)\setminus (\Lambda +a)\). Hence relabelling configurations carries the identity on the first complement to the identity on the second complement, and
The finite-region local algebras form a directed system under the maps \(\iota _{\Lambda ,\Gamma }\). Its algebraic direct limit is the algebraic local algebra
For every finite region \(\Lambda \), write \(\iota _\Lambda \colon \mathcal A_\Lambda \to \mathcal A_{\mathrm{loc}}\) for the canonical inclusion. Whenever \(\Lambda \subseteq \Gamma \), these inclusions satisfy
This is the union \(\bigcup _{\Lambda \Subset \mathbb Z}\mathcal A_\Lambda \) in the Appendix of [ 16 ] . No norm completion is taken.
For \(a\in \mathbb Z\) and \(N\in \mathbb N\), let \(I_{a,N}=[a,a+N)\cap \mathbb Z\). The increasing bijection \(\{ 0,\ldots ,N-1\} \simeq I_{a,N}\) identifies the periodic configuration basis with \(\operatorname {Config}_d(I_{a,N})\). In this basis, write \(U_{a}^{(N)}\) for the matrix obtained by simultaneously reindexing the rows and columns of \(U^{(N)}\).
Fix a positive block length \(L\) and an integer anchor \(a\). The number of sites from \(a\) to the next globally aligned block boundary is \(q(a,L)=(-a)\bmod L\). If an interval of length \(N\) has the decomposition \(N=p+mL+s\), its configuration may be specified by a prefix word of length \(p\), a word of \(m\) blocked letters, and a suffix word of length \(s\). Their ordered concatenation defines a configuration on \(I_{a,N}\), including when \(m=0\). This concatenation is a bijection from triples of such words to configurations on the interval.
For every \(a\in \mathbb Z\), \(N\in \mathbb N\), and \(L{\gt}0\), there are \(p,m,s\in \mathbb N\) such that
If \(m{\gt}0\), then \(a+p\) is divisible by \(L\); the site at residue \(r\) of the \(t\)th complete middle block has integer coordinate \(a+p+tL+r\). If \(N{\lt}q(a,L)\), then \(p=N\) and \(m=s=0\). The anchored configuration reads the prefix, middle blocks, and suffix in exactly this increasing site order.
Set \(p=\min (N,q(a,L))\) and divide \(N-p\) by \(L\), taking its quotient as \(m\) and its remainder as \(s\). Euclidean division gives \(s{\lt}L\) and the length identity. If \(m{\gt}0\), then \(p=q(a,L)\) and \(a+p\) is aligned. The order-preserving site identification sends position \(k\) to \(a+k\); applying it at \(k=p+tL+r\) gives the middle-block coordinate. When \(N{\lt}q(a,L)\), one has \(p=N\) and both other lengths vanish.
Let \(U\) be any MPO tensor and let \(N=p+mL+s\). For two anchored configurations with residual prefix words \(i^-,j^-\), blocked middle words \(\sigma ,\tau \), and residual suffix words \(i^+,j^+\), the entry of the finite-chain matrix is
This holds at every integer anchor and for arbitrary \(L,p,m,s\), including an empty middle word. Neither unitarity nor divisibility of \(N\) by \(L\) is assumed.
Undo the increasing reindexing of the finite-chain MPO matrix. The resulting periodic MPO entry is the trace of the prefix, blocked middle, and suffix products by residual-site blocking.
If \(\mathcal U\) is an MPU and \(N{\gt}1\), then \(U_a^{(N)}\) is unitary and defines the star-algebra automorphism
The factor order is the one in [ 16 , lines 2300–2306 ] .
Simultaneous reindexing preserves both unitarity equations for \(U^{(N)}\). Conjugation by the resulting unitary preserves multiplication, the unit, complex scalars, and the adjoint.
Let \(U\) be an MPU, \(N=p+mL+s{\gt}1\), and \(A\in \mathcal A_\Lambda \) for \(\Lambda \subseteq I_{a,N}\). Write \(\widehat x\) for the anchored configuration represented by a triple \(x=(x^-,x^0,x^+)\) of residual prefix, complete-block, and residual suffix words, and put
For all such triples \(x,y\), the matrix coefficient of finite-chain conjugation is
Both MPO factors retain their residual prefix and suffix products. This finite-chain identity does not assert independence of the interval or support of the conjugated observable.
Expand conjugation as a double sum over intermediate configurations. The local inclusion contributes the matrix entry of \(A\) on \(\Lambda \) and the equality condition on its complement. Reindex both sums by the residual-word bijection and apply the finite-chain residual-trace identity to each MPO coefficient.
Fix \(k,p,s\geq 0\) and an integer anchor \(a\). On the interval of length \(N=p+3(2k)+s\), distinguish three consecutive complete blocks of length \(2k\) between an arbitrary prefix and suffix. Let \(H=d^k\). On the output side, the four neighboring half-blocks form a factor \(X\) of dimension \(H^4\); the prefix, suffix, and two exposed outer half-blocks form the exterior factor \(E_{\mathrm{out}}\). On the input side, the central complete block forms a factor \(J\) of dimension \(H^2\); the prefix, suffix, and the two outer complete blocks form \(E_{\mathrm{in}}\). Ordered concatenation gives bijections from \(E_{\mathrm{out}}\times X\) and \(E_{\mathrm{in}}\times J\) to the respective configuration bases of the same finite interval. Write \(M_{a;p,k,s}\) for the finite-chain MPO matrix in these two bases.
Suppose the two-site blocking of \(U\) at length \(k\) is supplied with standard-form factors \(u,v\). For every observable \(A\) on the central input block, let \(B(A)\) be the corresponding observable on the two neighboring output links. Then
This identity holds for arbitrary original-site prefix and suffix words; \(U\) need not be an MPU. If \(U\) is an MPU and \(N{\gt}1\), then
Thus the conjugated operator is the identity on every exterior output coordinate. This statement assumes the displayed supplied standard form and does not yet identify the right-hand side with a site-indexed local inclusion or prove independence of the enclosing interval.
Fixing all exterior input and output coordinates makes a slice of \(M_{a;p,k,s}\) equal to the original-site three-block window. The open-word identity intertwines each slice with the same \(B(A)\). Summing over exterior coordinates yields (917). When \(U\) is an MPU, \(M_{a;p,k,s}\) is unitary; postmultiplying (917) by \(M_{a;p,k,s}^\dagger \) yields (918).
Let \(\Lambda \subseteq I_{a,N}\) and \(A\in \mathcal A_\Lambda \). Set \(A_L=\iota _{\Lambda ,I_{a,N}}(A)\). For \(N{\gt}1\), the finite-chain term in [ 16 , lines 2300–2306 ] is the star-algebra map
No stabilization in \(N\) is asserted.
Assume \(d{\gt}0\). If a local observable \(A\in \mathcal A_{\mathrm{loc}}\) is represented by \(A_\Lambda \in \mathcal A_\Lambda \) on a finite region \(\Lambda \), define its operator norm by
This definition is independent of the finite region and chosen representative, giving the norm completed in the Appendix of [ 16 ] to obtain the quasi-local algebra.
If \(A_\Lambda \) and \(A_\Gamma \) represent the same local observable, then the defining relation for the inductive limit gives a finite region \(\Delta \supseteq \Lambda \cup \Gamma \) such that
Both inclusions preserve the operator norm, so \(\lVert A_\Lambda \rVert =\lVert A_\Gamma \rVert \).
For \(d{\gt}0\), the local algebra with the operator norm is a normed complex star algebra. No completeness assertion is made.
Choose finite-region representatives of the local observables and enlarge their regions to a common finite region. The norm axioms, the product inequality, and compatibility with complex scalar multiplication then follow from the corresponding properties of the finite-region matrix algebra.
For \(d{\gt}0\) and every local observable \(A\),
Choose a finite region \(\Lambda \) and a representative \(A_\Lambda \in \mathcal A_\Lambda \). Then
The normed star algebra of local observables satisfies the \(C^*\)-norm identity.
The C-star identity gives the required norm inequality in the reverse direction; submultiplicativity gives the other direction.
For \(d{\gt}0\) and every finite region \(\Lambda \), the canonical map
is an operator-norm isometry.
The norm of \(\iota _\Lambda (A)\) is defined to be the operator norm of its representative \(A\in \mathcal A_\Lambda \). Hence \(\lVert \iota _\Lambda (A)\rVert =\lVert A\rVert \); applying this equality to differences proves preservation of distance.
Let \(B\) be a complex star algebra. Suppose that for every finite region \(\Lambda \) there is a star-algebra homomorphism \(g_\Lambda \colon \mathcal A_\Lambda \to B\). Whenever \(\Lambda \subseteq \Gamma \), suppose that
Then there is a unique star-algebra homomorphism \(g\colon \mathcal A_{\mathrm{loc}}\to B\) satisfying \(g\circ \iota _\Lambda =g_\Lambda \) for every finite region \(\Lambda \).
Define \(g\) on a local observable represented by \(A\in \mathcal A_\Lambda \) as \(g_\Lambda (A)\). Compatibility makes this independent of the representing region. Since each \(g_\Lambda \) preserves addition, multiplication, the unit, scalar multiplication, and the star operation, so does \(g\). Every element of the direct limit has a finite-region representative, which also proves uniqueness.
A local observable \(A\in \mathcal A_{\mathrm{loc}}\) is supported in the finite region \(\Lambda \) if it lies in the image of \(\iota _\Lambda \colon \mathcal A_\Lambda \to \mathcal A_{\mathrm{loc}}\).
Every local observable is supported in some finite region. If \(A\) is supported in \(\Lambda \) and \(\Lambda \subseteq \Gamma \), then \(A\) is supported in \(\Gamma \). If \(A\) and \(B\) are supported in \(\Lambda \) and \(\Gamma \), respectively, then \(A+B\) and \(AB\) are supported in \(\Lambda \cup \Gamma \). The adjoint \(A^*\) is supported in \(\Lambda \), and both \(0\) and \(1\) are supported in every finite region. For positive on-site dimension, each map \(\iota _\Lambda \) is injective.
Enlarge representatives by tensoring with the identity on the added sites. Two representatives can therefore be moved to the finite union of their regions, where sums and products are formed. The canonical inclusions are unital star-algebra homomorphisms, so they preserve the adjoint, zero, and the unit. For \(d{\gt}0\), every transition map between finite-region algebras is injective; the canonical map from each member of such a directed system to its direct limit is therefore injective. Finally, every element of an algebraic direct limit has a representative in one member of the directed system.
If \(X,Y\in \mathcal A_{\mathrm{loc}}\) are supported in finite regions \(\Lambda \) and \(\Gamma \) with \(\Lambda \cap \Gamma =\varnothing \), then
In particular, for \(A\in \mathcal A_\Lambda \) and \(B\in \mathcal A_\Gamma \),
This is the algebraic-local form of the tensor-factor identity underlying the construction in [ 16 , lines 2292–2300 ] , not a named theorem of the appendix.
Choose representatives \(X=\iota _\Lambda (A)\) and \(Y=\iota _\Gamma (B)\). Embed both into \(\mathcal A_{\Lambda \cup \Gamma }\). Theorem 18.10.8 gives
Assume \(d{\gt}0\). A local observable \(X\in \mathcal A_{\mathrm{loc}}\) is supported in a finite region \(\Lambda \) if and only if it commutes with every local observable having a finite support disjoint from \(\Lambda \):
This characterizes locally supported observables on the inductive limit algebra.
The forward implication is commutation of disjointly supported observables. Conversely, choose a finite support \(\Delta \) of \(X\) and represent \(X\) by \(A\in \mathcal A_{\Lambda \cup \Delta }\). The hypothesis says that \(A\) commutes with every observable on \((\Lambda \cup \Delta )\setminus \Lambda \). Since \(d{\gt}0\), the canonical map from \(\mathcal A_{\Lambda \cup \Delta }\) into \(\mathcal A_{\mathrm{loc}}\) is injective, so this commutation already holds in the finite-region algebra. The finite relative-commutant theorem gives \(A=\iota _{\Lambda ,\Lambda \cup \Delta }(A_\Lambda )\) for some \(A_\Lambda \in \mathcal A_\Lambda \). Hence \(X=\iota _\Lambda (A_\Lambda )\).
For \(a\in \mathbb Z\), finite-region translations induce a star-algebra homomorphism
determined on every finite-region representative by
Naturality gives, for \(\Lambda \subseteq \Gamma \),
Hence the finite-region maps form a compatible family and induce the stated homomorphism on the algebraic direct limit.
The homomorphisms satisfy
On a representative \(A\in \mathcal A_\Lambda \), the two sides of the composition law are represented on the equal finite regions \((\Lambda +a)+b\) and \(\Lambda +(a+b)\). The finite-region action identity therefore gives
The zero law is proved in the same way. Equality on all finite-region representatives determines equality on the algebraic direct limit.
For every \(a\in \mathbb Z\), the homomorphism \(\tau _a\) is a star-algebra automorphism of \(\mathcal A_{\mathrm{loc}}\), and on finite-region representatives
The homomorphism action laws give
Thus \(\tau _a\) is bijective with inverse \(\tau _{-a}\). The formula on finite-region representatives is the defining formula for the homomorphism.
The automorphisms form an additive action of \(\mathbb Z\):
The first two identities are the homomorphism action laws expressed as identities of star-algebra automorphisms. Taking \(b=-a\) in the composition law gives
which is the inverse identity.
A local observable \(A\) is supported in a finite region \(\Lambda \) if and only if \(\tau _a(A)\) is supported in \(\Lambda +a\).
If \(A=\iota _\Lambda (A_\Lambda )\), then
which proves the forward implication. Apply the same argument to \(\tau _a(A)\) with displacement \(-a\), and use \(\tau _{-a}\tau _a=\operatorname {id}\) and \((\Lambda +a)-a=\Lambda \), for the reverse implication.
If \(d{\gt}0\), then every translation preserves the operator norm and distance:
Choose \(A_\Lambda \in \mathcal A_\Lambda \) with \(A=\iota _\Lambda (A_\Lambda )\). Finite-region translation is a star-algebra equivalence of matrix algebras, hence preserves the operator norm. Therefore
Applying this equality to \(A-B\) gives distance preservation.
The norm completion of a complex normed star algebra satisfying the C-star identity carries the continuously extended involution and a C-star algebra structure. The canonical map into the completion is a star-algebra homomorphism.
Extend the isometric involution continuously. The algebraic identities and the C-star identity hold on the dense canonical image and hence on the completion.
For \(d{\gt}0\), the quasi-local observable algebra is the operator-norm completion
The involution on \(\mathcal A\) is the unique continuous extension of the involution on \(\mathcal A_{\mathrm{loc}}\). It makes \(\mathcal A\) a complex C-star algebra, and the canonical star-algebra homomorphism
is the completion map.
The involution is isometric on \(\mathcal A_{\mathrm{loc}}\), hence extends continuously to the completion. The identities \((A+B)^*=A^*+B^*\), \((AB)^*=B^*A^*\), and \((A^*)^*=A\) hold on the dense subalgebra \(j(\mathcal A_{\mathrm{loc}})\) and therefore on \(\mathcal A\). The conjugate-linear identity \((cA)^*=\overline cA^*\) extends by the same argument. Density also extends
so the completed algebra satisfies the C-star identity.
For every finite region \(\Lambda \), define
For every finite region \(\Lambda \), the map \(j_\Lambda \) is an injective isometry. If \(\Lambda \subseteq \Gamma \), then
The algebraic inclusion \(\iota _\Lambda \) and the completion map \(j\) both preserve the norm. Their composite is therefore an isometry and hence injective. Compatibility follows from \(\iota _\Gamma \circ \iota _{\Lambda ,\Gamma }=\iota _\Lambda \).
The canonical star-algebra homomorphism from a normed star algebra into its completion has dense range.
This is the defining density property of the completion.
Algebraic local observables are dense in the quasi-local algebra. Equivalently,
Density of \(j(\mathcal A_{\mathrm{loc}})\) is the defining density property of the completion. Every algebraic local observable has a representative in some finite region, so
and taking closures yields
Lattice translation acts covariantly on the quasi-local algebra in the setting of [ 16 , lines 2292–2306 ] .
Let \(A\) and \(B\) be complex normed star algebras, and let \(f\colon A\to B\) be a star-algebra equivalence. If \(f\) and \(f^{-1}\) are continuous, then \(f\) extends to a star-algebra equivalence
between their norm completions. Its underlying map is the continuous extension of \(f\). Writing \(j_A\) and \(j_B\) for the canonical maps into the completions, the extension satisfies
Apply the completion functor to \(f\) and \(f^{-1}\). On the dense canonical images their composites satisfy
Continuity gives the two inverse identities on the completions. Multiplication, addition, scalar multiplication, and the star operation commute with the extension because the corresponding identities hold on the canonical images and both sides are continuous.
For \(d{\gt}0\) and every \(a\in \mathbb Z\), algebraic-local translation extends to a star-algebra automorphism
of the quasi-local algebra. On the dense algebraic-local subalgebra and on finite-region observables it satisfies
For \(d{\gt}0\), the quasi-local automorphisms form an additive action of \(\mathbb Z\):
On the canonical image of the algebraic-local algebra,
Continuity extends these identities to the completion. Taking \((a,b)=(a,-a)\) and \((-a,a)\) identifies the inverse of \(\tau _a\) with \(\tau _{-a}\).
For \(d{\gt}0\), a star-algebra automorphism \(\omega \) of the quasi-local algebra \(\mathcal A\) is translation covariant if
for every \(a\in \mathbb Z\). This is the covariance condition in the definition of a one-dimensional QCA [ 16 , line 2298 ] .
For \(d{\gt}0\), a star-algebra automorphism \(\omega \) of \(\mathcal A\) is translation covariant if and only if
for every \(a\in \mathbb Z\) and every \(A\in \mathcal A\).
Two automorphisms are equal if and only if they agree on every observable. Apply this observation to the two composites in the definition.
For \(d{\gt}0\), a star-algebra automorphism \(\omega \) of \(\mathcal A\) commutes with every integer translation if and only if it commutes with unit translation:
The forward implication follows by taking the translation step to be \(1\). Conversely, use two-sided integer induction. The zero case follows from \(\tau _0=\operatorname {id}\). For the successor step, the additive action law gives \(\tau _{i+1}=\tau _1\circ \tau _i\), and
For the predecessor step, \(\tau _{-1}=\tau _1^{-1}\) transfers commutation to \(\tau _{-1}\), while \(\tau _{i-1}=\tau _{-1}\circ \tau _i\), so
For \(d{\gt}0\), the identity automorphism of \(\mathcal A\) is translation covariant. If \(\omega \) and \(\eta \) are translation covariant, then so is the composite
which first applies \(\omega \) and then \(\eta \).
The identity commutes pointwise with every translation. For the composite, translation covariance gives
For \(d{\gt}0\), every quasi-local translation preserves the operator norm and distance:
A star-algebra equivalence between complex C-star algebras preserves the C-star norm. Since \(\tau _a\) is linear,
For \(d{\gt}0\), a quasi-local observable \(x\in \mathcal A\) is supported in a finite region \(\Lambda \subset \mathbb Z\) if it belongs to the image of the canonical embedding \(j_\Lambda \colon \mathcal A_\Lambda \to \mathcal A\). Equivalently,
In particular, \(j_\Lambda (A)\) is supported in \(\Lambda \) for every \(A\in \mathcal A_\Lambda \).
These assertions follow directly from membership in the range of \(j_\Lambda \).
Let \(d{\gt}0\). If \(x\in \mathcal A\) is supported in \(\Lambda \) and \(\Lambda \subseteq \Gamma \), then \(x\) is supported in \(\Gamma \).
Write \(x=j_\Lambda (A)\). Enlarge \(A\) to \(\mathcal A_\Gamma \) by tensoring with the identity on \(\Gamma \setminus \Lambda \). Compatibility of the canonical embeddings identifies the image of this enlargement with \(x\).
Let \(d{\gt}0\). If \(x,y\in \mathcal A\) are supported in finite regions \(\Lambda \) and \(\Gamma \) with \(\Lambda \cap \Gamma =\varnothing \), then
Equivalently, for \(A\in \mathcal A_\Lambda \) and \(B\in \mathcal A_\Gamma \),
This is finite-support infrastructure for the quasi-local algebra in [ 16 , lines 2292–2300 ] ; it is not stated there as a separate theorem.
The completion map is a star-algebra homomorphism. Applying it to the algebraic-local identity gives
and finite-region support provides representatives \(x=j_\Lambda (A)\) and \(y=j_\Gamma (B)\).
Commutation with observables on the complementary tensor factor characterizes exact local support via the Weyl twirl.
Let \(S\) and \(C\) be finite sets, let \(n=|C|{\gt}0\), and choose an equivalence \(e\colon C\simeq \mathbb Z/n\mathbb Z\) and a primitive \(n\)-th root of unity \(\zeta \). If \(W_{a,b}\) is the corresponding reindexed Weyl operator on \(\mathbb C^C\), define
For every \(M\in \operatorname {Mat}_{S\times C}(\mathbb C)\),
Split \(M\) into \(C\times C\) blocks indexed by \(S\). The Weyl average sends each block \(B\) to \((\operatorname {tr}B/n)\mathbf1_C\), so its block trace is the corresponding entry of \(\operatorname {tr}_C(M)\).
Let \(S\) be a nonempty finite set. The average is contractive in the operator norm; if every complementary Weyl conjugation fixes \(X\), then
Unitary conjugation preserves the operator norm, and the coefficients of the finite average sum to one. Apply this contraction to \(M-X\).
Let \(d{\gt}0\), let \(\Lambda \subset \mathbb Z\) be finite, and let \(x\in \mathcal A\). Then
This characterizes local support through commutants on complementary regions in the UHF algebra [ 16 , 237 ] .
The forward implication follows from commutation of disjoint tensor factors. Conversely, approximate \(x\) by \(A\in \mathcal A_\Delta \), where \(\Lambda \subseteq \Delta \). Split \(\Delta =\Lambda \sqcup (\Delta \setminus \Lambda )\) and average \(A\) over Weyl unitaries on the second factor. Every such conjugation fixes \(x\) by the commutation hypothesis, so unitary invariance and convexity give
The Weyl identity writes the average as \(B\otimes \mathbf1\) for some \(B\in \mathcal A_\Lambda \). Thus elements of \(\mathcal A_\Lambda \) approximate \(x\) arbitrarily well. The embedding of \(\mathcal A_\Lambda \) is isometric, hence has closed range, and therefore \(x\in \mathcal A_\Lambda \).
The homogeneous quasi-local UHF algebra has a trivial center consisting of scalar multiples of the identity [ 16 , 203 , 237 ] .
Let \(d{\gt}0\) and let \(z\in \mathcal A\). If
then there is a unique \(c\in \mathbb C\) such that
Consequently,
Apply Theorem 18.10.2.58 with \(\Lambda =\varnothing \). The commutation hypothesis gives \(z\in j_\varnothing (\mathcal A_\varnothing )\), so there is an \(A\in \mathcal A_\varnothing \) with \(z=j_\varnothing (A)\). Let \(e\colon \mathbb C\xrightarrow {\ \sim \ }\mathcal A_\varnothing \) be the canonical isomorphism and write \(A=e(c)\). If also \(z=j_\varnothing (e(c'))\), then injectivity of \(j_\varnothing \) and of \(e\) give
Thus \(c\) is the unique scalar for which \(z=c\mathbf1\).
Write \(Z(\mathcal A)\) for the center. Since every \(j_\Gamma (B)\) belongs to \(\mathcal A\), the two inclusions are
Hence \(Z(\mathcal A)=\mathbb C\mathbf1\).
The appendix requires that “there exists a finite subset \(\mathcal N\subset \mathbb Z\)” such that, for every finite \(\Lambda \subset \mathbb Z\),
This is the forward propagation condition of [ 16 , line 2298 ] .
Let \(d{\gt}0\), let \(\omega \colon \mathcal A\to \mathcal A\) be a star-algebra automorphism, and let \(\mathcal N\subset \mathbb Z\) be finite. The automorphism \(\omega \) propagates within \(\mathcal N\) if, for every finite region \(\Lambda \) and every \(x\in \mathcal A\),
Let \(d{\gt}0\) and let \(\omega \colon \mathcal A\to \mathcal A\) be a star-algebra automorphism. The automorphism \(\omega \) has finite forward propagation if there exists a finite set \(\mathcal N\subset \mathbb Z\) such that \(\omega \) propagates within \(\mathcal N\).
Let \(d{\gt}0\), let \(\omega \colon \mathcal A\to \mathcal A\) be a star-algebra automorphism, and let \(\mathcal N\subset \mathbb Z\) be finite. The following conditions are equivalent:
Thus condition (c) is precisely the range-inclusion formula from line 2298 of [ 16 ] , expressed inside the quasi-local algebra, and condition (d) is its finite-region witness form.
Every observable supported in \(\Lambda \) has the form \(j_\Lambda (A)\), so (a) and (b) are equivalent. Replacing support by membership in the range of the canonical embedding gives (c). Finally, membership in \(j_{\Lambda +\mathcal N}(\mathcal A_{\Lambda +\mathcal N})\) is equivalent to the existence of a representative \(B\) in that finite-region algebra, which gives (d).
Let \(d{\gt}0\) and let \(\omega \colon \mathcal A\to \mathcal A\) be a star-algebra automorphism. If \(\mathcal N\subseteq \mathcal M\) and \(\omega \) propagates within \(\mathcal N\), then \(\omega \) propagates within \(\mathcal M\). More explicitly, for every finite region \(\Lambda \),
Consequently, if \(\omega \) has finite forward propagation, then for every prescribed finite set \(\mathcal N\subset \mathbb Z\) there is a finite set \(\mathcal M\subset \mathbb Z\) such that
This is the neighborhood-enlargement consequence of the propagation condition in Appendix line 2298 of [ 16 ] .
Monotonicity of the sumset in its second argument gives \(\Lambda +\mathcal N\subseteq \Lambda +\mathcal M\). Monotonicity of quasi-local support then enlarges the support of \(\omega (x)\) from \(\Lambda +\mathcal N\) to \(\Lambda +\mathcal M\). For the final assertion, choose a finite propagation neighborhood \(\mathcal K\) and take \(\mathcal M=\mathcal K\cup \mathcal N\).
Let \(d{\gt}0\), let \(\omega ,\eta \colon \mathcal A\to \mathcal A\) be star-algebra automorphisms, and let \(\mathcal N,\mathcal M\subset \mathbb Z\) be finite. Suppose that \(\omega \) propagates within \(\mathcal N\) and \(\eta \) propagates within \(\mathcal M\). The composite \(\eta \circ \omega \) first applies \(\omega \) and then \(\eta \), so
Hence \(\eta \circ \omega \) propagates within \(\mathcal N+\mathcal M\). In particular, if \(\omega \) and \(\eta \) have finite forward propagation, then \(\eta \circ \omega \) has finite forward propagation. This is the composition closure of the finite-neighborhood condition in Appendix line 2298 of [ 16 ] .
Apply the two propagation bounds successively and use associativity of finite region sumsets. For the existential assertion, choose one finite propagation neighborhood for each automorphism and use their sumset.
Every finite set \(\mathcal N\subset \mathbb Z\) is contained in \([-R,R]\cap \mathbb Z\) for some \(R\in \mathbb N\). This includes \(\mathcal N=\varnothing \), for which one may take \(R=0\). If \(\omega \) propagates within a fixed set \(\mathcal N\), then \(R\) may be chosen so that
Consequently, finite forward propagation admits a symmetric-interval witness:
Let \(R\) be the maximum of \(|n|\) over \(n\in \mathcal N\), with value \(0\) when \(\mathcal N\) is empty. Then \(-R\leq n\leq R\) for every \(n\in \mathcal N\), which gives \(\mathcal N\subseteq [-R,R]\cap \mathbb Z\). Enlargement of propagation neighborhoods gives the fixed-neighborhood assertion. Finally, choose a finite propagation neighborhood and apply this enlargement to its symmetric interval.
Let \(\Gamma ,\Lambda ,\mathcal N\subset \mathbb Z\) be finite. Then
If \(g+n=\lambda \) for \(g\in \Gamma \), \(n\in \mathcal N\), and \(\lambda \in \Lambda \), then \(g=\lambda +(-n)\in \Lambda +(-\mathcal N)\), proving the forward implication. Conversely, if \(g\in \Gamma \) and \(g=\lambda +(-n)\) with \(\lambda \in \Lambda \) and \(n\in \mathcal N\), then \(\lambda =g+n\in \Gamma +\mathcal N\).
Let \(d{\gt}0\), let \(\omega \) be a star-algebra automorphism of \(\mathcal A\), and let \(\mathcal N\subset \mathbb Z\) be finite. If \(\omega \) propagates within \(\mathcal N\), then \(\omega ^{-1}\) propagates within \(-\mathcal N\). Therefore finite forward propagation of \(\omega \) implies finite forward propagation of \(\omega ^{-1}\). If \(\omega \) is translation covariant, then \(\omega ^{-1}\) is also translation covariant.
Schumacher and Werner [ 237 , Theorem 6, Corollary 7 ] derive inverse locality through generalized Margolus partitioning; the proof here establishes it via commutants on complementary regions.
Let \(x\in \mathcal A_\Lambda \) and let \(y\in \mathcal A_\Gamma \), where \(\Gamma \cap (\Lambda +(-\mathcal N))=\varnothing \). Forward locality gives \(\omega (y)\in \mathcal A_{\Gamma +\mathcal N}\). The regions \(\Gamma +\mathcal N\) and \(\Lambda \) are disjoint, so \(x\) commutes with \(\omega (y)\). Applying \(\omega ^{-1}\) shows that \(\omega ^{-1}(x)\) commutes with \(y\). The exact outside-commutant characterization now gives
Choosing the reflected finite neighborhood proves the existential statement. For each lattice translation \(\tau _a\), multiplying the covariance identity on the left and right by \(\omega ^{-1}\) gives
Let \(d{\gt}0\) and let \(\omega \colon \mathcal A\to \mathcal A\) be a star-algebra automorphism. The automorphism \(\omega \) is a one-dimensional quantum cellular automaton if it is translation covariant and has finite forward propagation. Thus there exists a finite set \(\mathcal N\subset \mathbb Z\) such that, for every finite \(\Lambda \subset \mathbb Z\),
This is the definition at line 2298 of [ 16 ] . It imposes only the displayed forward propagation condition and makes no locality claim for \(\omega ^{-1}\).
For \(d{\gt}0\), a star-algebra automorphism \(\omega \) of \(\mathcal A\) is a quantum cellular automaton if and only if it is translation covariant and has finite forward propagation. These two properties therefore construct an automaton, and every quantum cellular automaton satisfies each of them.
This is the conjunction defining a quantum cellular automaton, together with its introduction and elimination rules.
For \(d{\gt}0\), the identity automorphism of \(\mathcal A\) is a quantum cellular automaton.
The identity is translation covariant. For finite forward propagation, choose the neighborhood \(\{ 0\} \). An observable supported in \(\Lambda \) remains unchanged, and \(\Lambda +\{ 0\} =\Lambda \).
Let \(d{\gt}0\). If \(\omega \) and \(\eta \) are quantum cellular automata on \(\mathcal A\), then \(\eta \circ \omega \) is a quantum cellular automaton. This composite first applies \(\omega \) and then \(\eta \). No propagation condition for either inverse is required.
Both defining properties are closed under composition in the stated order. Translation covariance of \(\omega \) and \(\eta \) gives translation covariance of \(\eta \circ \omega \). If \(\mathcal N\) and \(\mathcal M\) are forward propagation neighborhoods for \(\omega \) and \(\eta \), respectively, then \(\mathcal N+\mathcal M\) is a forward propagation neighborhood for \(\eta \circ \omega \). Hence the composite is a quantum cellular automaton.
Let \(d{\gt}0\). If \(\omega \) is a quantum cellular automaton on \(\mathcal A\), then \(\omega ^{-1}\) is also a quantum cellular automaton.
Translation covariance and finite forward propagation are both preserved by inversion. These are the two defining properties of a quantum cellular automaton.
Let \(L{\gt}0\) be a block length and let \(\Lambda \subset \mathbb Z\) be finite. The expansion of \(\Lambda \) is
Every \(z\in \widehat\Lambda _L\) has unique block coordinates \((x,r)\) with \(x\in \Lambda \) and \(0\leq r{\lt}L\). Increasing \(r\) gives the consecutive-site order within the block, matching the finite-region site grouping in [ 16 , lines 2308 and 2313–2320 ] .
An integer \(z\) belongs to \(\widehat\Lambda _L\) exactly when its quotient by \(L\) belongs to \(\Lambda \). The inverse block-coordinate map sends \((x,r)\) to \(Lx+r\), and \(\Lambda \subseteq \Gamma \) implies \(\widehat\Lambda _L\subseteq \widehat\Gamma _L\).
Apply Euclidean division by the positive integer \(L\). Its quotient and residue are unique, the residue lies in \(\{ 0,\ldots ,L-1\} \), and taking the inverse coordinates gives \(Lx+r\). Monotonicity follows by retaining the same quotient and residue.
For on-site dimension \(d\), configurations of \(d^L\)-level blocked spins on \(\Lambda \) are equivalent to configurations of \(d\)-level spins on \(\widehat\Lambda _L\). The blocked label at \(x\) is decoded into its ordered length-\(L\) word, and its \(r\)th letter is placed at \(Lx+r\).
Evaluation at \(Lx+r\) reads the \(r\)th letter of the blocked spin at \(x\). Conversely, encoding collects these letters in increasing residue order. At the configuration level, decoding commutes with restriction from \(\Gamma \) to \(\Lambda \subseteq \Gamma \).
The two evaluation formulas are the inverse laws for the ordered word encoding. Restriction preserves the quotient block coordinate and residue, so both sides have the same value at every expanded site.
Reindexing matrix rows and columns by the configuration blocking equivalence gives a star-algebra equivalence
This is the finite-region equivalence underlying the algebraic-local blocking construction below. No quasi-local completion, compatibility with translations, propagation statement, circuit representation, or transport of quantum cellular automata is asserted here.
Matrix entries are transported by applying the inverse configuration equivalence to both indices. The blocking equivalence preserves the operator norm and is an isometry.
The entry formula is matrix reindexing. A star-algebra equivalence between finite matrix algebras preserves the C-star norm and hence distances.
For \(L{\gt}0\) and a finite original region \(\Delta \subset \mathbb Z\), define its block hull by
This is the finite set of length-\(L\) blocks that meet \(\Delta \).
Let \(L{\gt}0\). Every finite original region is contained in the expansion of its block hull,
If \(\Delta \subseteq \Theta \), then \(\operatorname {Hull}_L(\Delta )\subseteq \operatorname {Hull}_L(\Theta )\). Expansion and block hull are exact in the blocked direction:
The quotient coordinate of each \(z\in \Delta \) belongs to the image defining the hull, which proves containment after expansion. Monotonicity follows by retaining the same witness \(z\) in the larger region. Finally, every expanded site has quotient in \(\Lambda \), while for each \(x\in \Lambda \) the site \(Lx\) belongs to \(\widehat\Lambda _L\) and has quotient \(x\). Hence \(\operatorname {Hull}_L(\widehat\Lambda _L)=\Lambda \).
Let \(L{\gt}0\). For finite blocked regions \(\Lambda \subseteq \Gamma \), the square formed by finite blocking and the two canonical local inclusions commutes:
For configurations \(x,y\) on \(\widehat\Gamma _L\), let \(\widetilde x\) and \(\widetilde y\) be their block encodings on \(\Gamma \). The two matrix entries in the commuting square are
Restriction commutes with block encoding, and decoding identifies \(\Gamma \setminus \Lambda \) with the original sites in \(\widehat\Gamma _L\setminus \widehat\Lambda _L\). Hence the two indicator conditions are equivalent and the entries agree.
Let \(L{\gt}0\). The compatible finite blocking maps induce a star-algebra homomorphism
In the reverse direction there is a star-algebra homomorphism
A representative on an arbitrary original region \(\Delta \) is included into \(\widehat{\operatorname {Hull}_L(\Delta )}_L\) before inverting the finite blocking.
For \(\Lambda \subseteq \Gamma \), the finite commuting square gives
so the forward finite-region maps form a compatible family. For the reverse family, block-hull monotonicity sends \(\Delta \subseteq \Theta \) to \(\operatorname {Hull}_L(\Delta )\subseteq \operatorname {Hull}_L(\Theta )\). Transitivity of the canonical inclusions and the inverse commuting square then give
The universal property of the algebraic direct limit therefore induces both star-algebra homomorphisms.
Let \(L{\gt}0\). The forward map applies finite blocking to a representative on \(\Lambda \) and regards the result as supported on \(\widehat\Lambda _L\). The reverse map enlarges a representative on \(\Delta \) to the expansion of its block hull, applies the inverse finite blocking equivalence, and regards the result as supported on \(\operatorname {Hull}_L(\Delta )\). The forward composite is the identity,
This holds for every on-site dimension \(d\).
These are the evaluation formulas for the two compatible-family lifts. Forward compatibility is the commuting square. Reverse compatibility follows by monotonicity of block hulls, composition of local inclusions, and the same square applied in the inverse direction. Forward blocking after the reverse map reduces to the canonical inclusion of \(\Delta \) into its expanded block hull.
For \(d{\gt}0\) and \(L{\gt}0\), forward blocking gives a star-algebra equivalence
This corresponds to the algebraic-local change of site grouping in [ 16 , lines 2308 and 2313–2320 ] .
The identity \(\mathcal B_L\mathcal U_L=\operatorname {id}\) makes \(\mathcal B_L\) surjective. For injectivity, represent two blocked observables on finite regions \(\Lambda \) and \(\Gamma \), enlarge both to \(\Omega =\Lambda \cup \Gamma \), and suppose their images under \(\mathcal B_L\) agree. Injectivity of the canonical map from the finite algebra on \(\widehat\Omega _L\), followed by injectivity of \(\mathcal B_{L,\Omega }\) and the finite commuting square, gives equality of the two representatives in the algebra on \(\Omega \). Thus \(\mathcal B_L\) is bijective, with inverse \(\mathcal U_L\), and defines the stated star-algebra equivalence.
Let \(d{\gt}0\) and \(L{\gt}0\). The equivalence agrees with the forward lift, and its inverse agrees with the block-hull unblocking map. For \(A\in \mathcal A^{(d^L)}_\Lambda \) and \(C\in \mathcal A^{(d)}_\Delta \),
In particular, if \(C\in \mathcal A^{(d)}_{\widehat\Lambda _L}\), then
The forward and inverse maps are operator-norm isometries. In particular, each preserves the norm.
The first two formulas are the evaluation identities for the forward and reverse maps. For an expanded region, the block-hull identity removes the enlargement and leaves the inverse finite blocking equivalence. On a finite representative, forward norm preservation reduces to norm preservation by finite blocking and by the canonical local inclusion; distance preservation follows by applying the norm identity to differences. The inverse isometry follows from the forward isometry and the right-inverse identity, rather than repeating the norm calculation.
For \(d{\gt}0\) and \(L{\gt}0\), site blocking extends uniquely by continuity to a star-algebra equivalence
This completes the change of site grouping used in [ 16 , lines 2308 and 2313–2320 ] .
The algebraic blocking equivalence and its inverse are isometries, hence continuous. Extending both maps to the operator-norm completions gives mutually inverse star-algebra homomorphisms.
Let \(d{\gt}0\) and \(L{\gt}0\). Write \(j^{(d)}\) for the canonical map from the algebraic-local algebra into its completion. The underlying map of \(\overline{\mathcal B}_L\) is the continuous extension of \(\mathcal B_L\), and on the two dense algebraic-local subalgebras,
For \(A\in \mathcal A^{(d^L)}_\Lambda \) and \(C\in \mathcal A^{(d)}_\Delta \), these identities become
If \(C\in \mathcal A^{(d)}_{\widehat\Lambda _L}\), the inverse formula reduces exactly to
Finally, for all quasi-local observables \(X\) and \(Y\) on the blocked chain,
Equalities (1037) and (1038) are the defining continuous extensions of the algebraic equivalence and its inverse. Composing them with the finite-region canonical maps gives (1039) and (1040). The exact formula (1041) uses \(\operatorname {Hull}_L(\widehat\Lambda _L)=\Lambda \). Because a star-algebra equivalence of C-star algebras preserves the norm, (1042) holds, and applying it to \(X-Y\) gives (1043).
Let \(d{\gt}0\) and \(L{\gt}0\). If a blocked-chain observable \(X\) is supported in \(\Lambda \), then \(\overline{\mathcal B}_L(X)\) is supported in \(\widehat\Lambda _L\). If an original-chain observable \(Y\) is supported in \(\Delta \), then \(\overline{\mathcal B}_L^{-1}(Y)\) is supported in \(\operatorname {Hull}_L(\Delta )\). In particular, support transport is exact on expanded regions:
Choose a finite-region representative and apply the corresponding forward or inverse finite evaluation formula. For the reverse implication in the exact statement, apply inverse blocking and simplify the inverse composite and the block hull of the expanded region.
Let \(L{\gt}0\), let \(a\in \mathbb Z\), and let \(\Lambda \subset \mathbb Z\) be a finite blocked region. Then
This is the translation rule for the site grouping used in [ 16 , lines 2308 and 2313–2320 ] .
Write each original site uniquely as \(xL+r\), with \(0\leq r{\lt}L\). Translation of the blocked coordinate by \(a\) sends this site to \((x+a)L+r=xL+r+aL\). The argument is unchanged when \(x\) or \(a\) is negative.
Let \(L{\gt}0\) and let \(\mathcal N\subset \mathbb Z\) be a finite original-lattice neighborhood. Write \(\widehat{\{ 0\} }_L=\{ 0,\ldots ,L-1\} \) for the sites in the reference block. Define the induced blocked-lattice neighborhood by
The full reference block is included because the block reached after a displacement can depend on the starting residue. This is the finite-region geometry implicit in the grouping of sites in [ 16 , lines 2308 and 2313–2320 ] .
Let \(L{\gt}0\), let \(\mathcal N\subset \mathbb Z\) be finite, and let \(b\in \mathbb Z\). Then
The quotient is the Euclidean quotient by the positive integer \(L\). Consequently these formulas include negative displacements and both positive and negative block carries. In general, \(\operatorname {Hull}_L(\mathcal N)\) alone omits some carries caused by the starting residue. This makes explicit the boundary geometry implicit in [ 16 , lines 2313–2320 ] .
An element of \(\widehat{\{ 0\} }_L+\mathcal N\) has the form \(r+n\) with \(0\leq r{\lt}L\) and \(n\in \mathcal N\). Taking its block coordinate gives the first equivalence. Euclidean division writes \(r+n=bL+s\) with the unique remainder \(0\leq s{\lt}L\), which gives the second equivalence without any sign restriction on \(n\).
Let \(L{\gt}0\). For every finite blocked region \(\Lambda \) and every finite original-lattice neighborhood \(\mathcal N\),
This is the exact finite-region carry identity associated with the site grouping in [ 16 , lines 2313–2320 ] .
Write an expanded site as \(xL+r\), where \(x\in \Lambda \) and \(0\leq r{\lt}L\). For \(n\in \mathcal N\), Euclidean division gives
The second summand ranges over exactly \(\mathcal C_L(\mathcal N)\) by Lemma 18.10.2.91. This proves both inclusions, including for negative \(x\) and \(n\).
Let \(L{\gt}0\). For every finite blocked region \(\Lambda \) and every finite original-lattice neighborhood \(\mathcal N\),
Every finite original region is contained in the expansion of its block hull. Apply this containment to \(\widehat\Lambda _L+\mathcal N\) and use Lemma 18.10.2.92 to identify that hull.
Let \(d,L{\gt}0\). If \(\mathcal B_L\) denotes the algebraic-local blocking equivalence, then for every \(a\in \mathbb Z\),
This is the translation rule induced by the blocking of sites used in [ 16 , lines 2308 and 2313–2320 ] .
On a representative supported in a finite blocked region \(\Lambda \), both sides apply the same matrix reindexing. Their supports agree because
Equality on all finite-region representatives proves the identity on the algebraic direct limit.
Let \(d,L{\gt}0\). If \(\overline{\mathcal B}_L\) denotes the quasi-local blocking equivalence, then for every \(a\in \mathbb Z\),
This is the completion of the translation rule induced by the site grouping in [ 16 , lines 2308 and 2313–2320 ] .
The two sides are continuous maps on the quasi-local algebra. On the dense algebraic-local subalgebra their values agree by Lemma 18.10.2.94. They therefore agree on the completion.
Under finite blocking, every one-dimensional quantum cellular automaton remains a QCA, providing the blocked grouping used in the representation theorem of [ 16 , line 2308 ] .
Let \(d,L{\gt}0\), let \(\overline{\mathcal B}_L\colon \mathcal A^{(d^L)}\simeq \mathcal A^{(d)}\) be the quasi-local blocking equivalence, and let \(\omega \) be a star-algebra automorphism of \(\mathcal A^{(d)}\). The induced automorphism of the blocked chain is
For every \(X\in \mathcal A^{(d^L)}\),
This is the evaluation formula for the defining conjugation.
The inverse of the blocked automorphism is the blocked inverse:
Evaluate both sides on a blocked-chain observable. The blocking equivalence and its inverse cancel on the two sides of \(\omega ^{-1}\).
Let \(\mathcal N\subset \mathbb Z\) be finite. If \(\omega \) propagates within \(\mathcal N\), then \(\omega ^{[L]}\) propagates within the carry-aware blocked neighborhood \(\mathcal C_L(\mathcal N)\). Explicitly, for every finite blocked region \(\Lambda \) and every \(X\in \mathcal A^{(d^L)}\) supported in \(\Lambda \), the observable \(\omega ^{[L]}(X)\) is supported in \(\Lambda +\mathcal C_L(\mathcal N)\).
Forward blocking sends support in \(\Lambda \) to support in \(\widehat\Lambda _L\). Apply the propagation bound for \(\omega \), then apply inverse blocking. The resulting support is
by the exact carry-aware block-hull identity.
If \(\omega \) has finite forward propagation, then \(\omega ^{[L]}\) has finite forward propagation.
Choose a finite propagation neighborhood \(\mathcal N\) for \(\omega \). Lemma 18.10.2.99 gives the finite neighborhood \(\mathcal C_L(\mathcal N)\) for \(\omega ^{[L]}\).
The blocked automorphism is translation covariant if and only if the original automorphism commutes with translation by one whole block:
Thus blocked unit-translation covariance records commutation of \(\omega \) with translation by \(L\), not necessarily commutation with original unit translation. For \(L\neq 1\), the latter condition can be strictly stronger.
By Theorem 18.10.2.49, translation covariance on the blocked chain is equivalent to commutation with blocked unit translation. Under \(\overline{\mathcal B}_L\), blocked unit translation corresponds to original translation by \(L\). Conjugating the commutation identity by the blocking equivalence proves both implications.
If \(\omega \) is translation covariant, then \(\omega ^{[L]}\) is translation covariant.
Translation covariance of \(\omega \) gives commutation with \(\overline\tau ^{(d)}_L\). Apply Theorem 18.10.2.101.
Let \(d,L{\gt}0\). If \(\omega \) is a one-dimensional QCA on \(\mathcal A^{(d)}\), then
is a one-dimensional QCA on \(\mathcal A^{(d^L)}\).
The two defining properties of a one-dimensional QCA are finite forward propagation and translation covariance. They are preserved by Lemma 18.10.2.100 and Lemma 18.10.2.102, respectively.
Regrouping sites normalizes the finite propagation neighborhood of a QCA to \([-1,1]\cap \mathbb Z\), setting up the depth-two circuit representation in [ 16 , line 2308 ] and [ 237 ] .
Let \(L{\gt}0\) and let \(\mathcal N\subset \mathbb Z\) be finite. If \(|n|{\lt}L\) for every \(n\in \mathcal N\), then
If \(\mathcal N=\varnothing \), membership in \(\mathcal C_L(\mathcal N)\) is impossible. In general, a point \(b\in \mathcal C_L(\mathcal N)\) supplies residues \(0\leq r,s{\lt}L\) and \(n\in \mathcal N\) such that
Since \(-L{\lt}n{\lt}L\), the equality is incompatible with \(b\leq -2\) and with \(b\geq 2\). Thus \(-1\leq b\leq 1\), including for negative displacements.
Let \(L{\gt}0\) and let \(\mathcal N\subset \mathbb Z\) be finite. If
then
Every \(|n|\) is bounded above by the finite supremum, so the strict supremum bound supplies the pointwise hypothesis. When \(\mathcal N=\varnothing \), the supremum is \(0\) and the conclusion is vacuous.
For every finite \(\mathcal N\subset \mathbb Z\), define
Then \(L_{\mathcal N}{\gt}0\) and
With the finite-supremum convention, \(L_{\varnothing }=1\).
The finite supremum is strictly smaller than its successor, which is positive even when \(\mathcal N\) is empty.
Let \(d,L{\gt}0\). Suppose that \(\omega \) propagates within the finite neighborhood \(\mathcal N\) and that \(|n|{\lt}L\) for every \(n\in \mathcal N\). For every finite blocked region \(\Lambda \) and every observable \(X\in \mathcal A^{(d^L)}\) supported in \(\Lambda \), the observable \(\omega ^{[L]}(X)\) is supported in
Blocking first gives propagation within \(\mathcal C_L(\mathcal N)\). The carry bound places this neighborhood inside \([-1,1]\cap \mathbb Z\), and enlargement of propagation neighborhoods gives the claim.
Let \(d{\gt}0\). If \(\omega \) has finite forward propagation, then there exists a positive integer \(L\) such that, for every finite blocked region \(\Lambda \) and every observable \(X\in \mathcal A^{(d^L)}\) supported in \(\Lambda \), the observable \(\omega ^{[L]}(X)\) is supported in
Choose a finite propagation neighborhood \(\mathcal N\) and take \(L=1+\sup _{n\in \mathcal N}|n|\). This \(L\) is positive, including when \(\mathcal N\) is empty. Blocking gives propagation within \(\mathcal C_L(\mathcal N)\); the canonical carry inclusion and propagation monotonicity then give the nearest-neighbor bound.
Let \(d{\gt}0\) and let \(\omega \) be a one-dimensional QCA on \(\mathcal A^{(d)}\). There exists a positive integer \(L\) such that \(\omega ^{[L]}\) is a QCA on \(\mathcal A^{(d^L)}\) and, for every finite blocked region \(\Lambda \) and every observable \(X\in \mathcal A^{(d^L)}\) supported in \(\Lambda \), the observable \(\omega ^{[L]}(X)\) is supported in
Apply Theorem 18.10.2.108 to the finite propagation of \(\omega \), using the canonical positive block length. At the same length, site blocking preserves both finite propagation and translation covariance, hence the QCA property.
Lines 2292–2298 of [ 16 ] specify the finite local algebras, their canonical inclusions, translation covariance, and the locality inclusion
The finite-dimensional maps determined by this locality inclusion follow the adjacent-pair ordering convention of [ 203 ] .
Let \(d{\gt}0\), let \(\omega \) be a star-algebra automorphism of \(\mathcal A^{(d)}\), and suppose that \(\omega \) propagates within the finite neighborhood \(\mathcal N\). For every finite region \(\Lambda \), define the finite-region restriction
to be the unique star-algebra homomorphism satisfying
The finite-region restriction is injective, and for every \(A\in \mathcal A_\Lambda \) one has
The defining equality follows from the locality inclusion and the injectivity of \(\iota _{\Lambda +\mathcal N}\). If two local observables have the same image under \(\omega _{\Lambda ,\mathcal N}\), their canonical images become equal after applying \(\omega \). Injectivity of \(\omega \) and of \(\iota _\Lambda \) then gives equality of the two local observables.
If \(\Lambda \subseteq \Gamma \), then for every \(A\in \mathcal A_\Lambda \),
Apply the canonical inclusion into the quasi-local algebra to both sides. Both expressions become \(\omega (\iota _\Lambda (A))\); injectivity of the target inclusion gives the equality.
Suppose in addition that \(\omega \) is translation covariant. For \(a\in \mathbb Z\) and \(A\in \mathcal A_\Lambda \),
Here \((\Lambda +a)+\mathcal N=(\Lambda +\mathcal N)+a\).
The left-hand side is \(\omega (\tau _a(\iota _\Lambda (A)))\). Translation covariance moves \(\tau _a\) past \(\omega \), and the finite-region translation formula gives the right-hand side.
Let \(\Gamma ,\Delta \subset \mathbb Z\) be disjoint finite regions. Writing \(\mathcal C_\Gamma \) and \(\mathcal C_\Delta \) for their configuration spaces, restriction to the two regions gives
with the \(\Gamma \)-configuration first. Reindexing matrix rows and columns gives a star-algebra equivalence
For \(A\in \mathcal A_\Gamma \) and \(B\in \mathcal A_\Delta \),
Evaluate both matrices on pairs of configurations. For the first local inclusion, restriction to \(\Gamma \) gives the matrix coefficient of \(A\), while equality of the complementary \(\Delta \)-configurations gives the matrix coefficient of the identity. This is \(A\otimes \mathbf1\). Interchanging the two regions gives \(\mathbf1\otimes B\).
Define the finite local image by
It is a star-subalgebra star-isomorphic to \(\mathcal A_\Lambda \). If \(\Lambda +\mathcal N=\Gamma \cup \Delta \) with \(\Gamma \cap \Delta =\varnothing \), then
is the bipartite matrix star-subalgebra to which the left and right support-algebra constructions apply. No support algebra is defined in this statement.
For \(x\in \mathbb Z\), set
The order \(L_x,P_x\) is the left–right factor order in equation RR2x of [ 203 , lines 1251–1266 ] . The same four-site localization occurs in [ 16 , lines 2313–2318 ] .
For the neighbourhood \(\mathcal N=\{ -1,0,1\} \),
Substitute (1082). Adding \(-1,0,1\) to the two points of \(E_x\) gives
The largest point of \(L_x\) is \(2x\), while the smallest point of \(P_x\) is \(2x+1\), so the two sets are disjoint. Finally, \(L_{x+1}=\{ 2x+1,2x+2\} =P_x\).
Let \(\omega \) be a star-algebra automorphism of the homogeneous quasi-local algebra which propagates within \(\{ -1,0,1\} \). Write the finite image of \(\mathcal A_{E_x}\) in the ordered \(L_x\times P_x\) coordinates as
Define
After the canonical finite-region embeddings, these form one family of star-subalgebras of the quasi-local algebra. Here the matrix embedding is the composition
Under this identification, the canonical local inclusion in [ 16 , lines 2292–2298 ] is exactly the displayed composition. Formula (1087) is equation RR2x in [ 203 , lines 1261–1266 ] . Cirac et al. use the homogeneous even factor in [ 16 , lines 2322–2328 ] ; the odd factor and unified family are supplied by the GNVW construction.
While GNVW allow the cell size \(d(y)\) to depend on \(y\), the present definition treats a homogeneous chain with fixed size \(d\); see [ 64 ] .
For every \(x\in \mathbb Z\), the finite image satisfies
This is the homogeneous, full-matrix instance used in the two-sided containment at [ 203 , lines 1276–1278 ] ; see [ 64 ] . Cirac et al. state only the weaker inclusion in the left support algebra tensored with the unrestricted right physical factor at [ 16 , lines 2322–2328 ] .
Apply Theorem 18.10.1.16 to \(S_x\) in the ordered coordinates of (1085). Its left support is \(\mathcal R_{2x}\) and its right support is \(\mathcal R_{2x+1}\) by (1087), which gives (1089).
If \(\widehat{\mathcal R}_y\) denotes the canonical quasi-local copy of \(\mathcal R_y\), then for every \(x\in \mathbb Z\),
More generally, the canonical image of any matrix on a finite region \(\Lambda \) is supported in \(\Lambda \). This is the homogeneous specialization of the localization accompanying equation RR2x in [ 203 , lines 1261–1274 ] ; see [ 64 ] .
An element of \(\widehat{\mathcal R}_{2x}\) is the canonical image of a matrix in \(\mathcal R_{2x}\subseteq \mathcal A_{L_x}\) and is therefore supported in \(L_x\). The same argument places \(\widehat{\mathcal R}_{2x+1}\) in \(\mathcal A_{P_x}\).
If \(\Lambda \subseteq \Gamma \) are finite regions, then \(\iota _\Lambda (\mathcal A_\Lambda ) \subseteq \iota _\Gamma (\mathcal A_\Gamma )\). If the finite regions \(\Lambda \) and \(\Gamma \) are disjoint, then the two canonical images generate the image of their union,
This is the expansion of an observable on several cells into a product of observables on disjoint groups of cells used in [ 203 , lines 592–596 ] and proved in [ 237 , lines 341–364 ] .
Monotonicity follows from \(\iota _\Gamma \circ \iota _{\Lambda ,\Gamma }=\iota _\Lambda \), and it gives the inclusion \(\supseteq \) in (1091). For the remaining inclusion, let \(\mathcal V\subseteq \mathcal A_{\Lambda \cup \Gamma }\) be the star-subalgebra of those \(A\) whose canonical image lies in the join on the right-hand side. In the bipartite coordinates \(\beta _{\Lambda ,\Gamma }\), the canonical inclusion of \(\mathcal A_\Lambda \) is \(X\mapsto X\otimes \mathbf1\) and that of \(\mathcal A_\Gamma \) is \(Y\mapsto \mathbf1\otimes Y\), so \(\beta _{\Lambda ,\Gamma }(\mathcal V)\) contains \(M_{\mathcal C_\Lambda }(\mathbb C)\otimes \mathbf1\) and \(\mathbf1\otimes M_{\mathcal C_\Gamma }(\mathbb C)\). The join of these two subalgebras has underlying vector space \(M_{\mathcal C_\Lambda }(\mathbb C)\boxtimes M_{\mathcal C_\Gamma }(\mathbb C)\), and every matrix on \(\mathcal C_\Lambda \times \mathcal C_\Gamma \) lies in that span. Hence \(\beta _{\Lambda ,\Gamma }(\mathcal V)\) is everything, and \(\beta _{\Lambda ,\Gamma }\) is bijective, so \(\mathcal V=\mathcal A_{\Lambda \cup \Gamma }\).
For \(x\ne y\) the pairs \(E_x\) and \(E_y\) are disjoint, and every finite region \(\Lambda \) satisfies
where \(X_\Lambda =\{ \lfloor i/2\rfloor \mid i\in \Lambda \} \).
Both statements are integer arithmetic: the four sites \(2x,2x+1,2y,2y+1\) are distinct for \(x\ne y\), and every \(i\) satisfies \(i=2\lfloor i/2\rfloor \) or \(i=2\lfloor i/2\rfloor +1\).
The pair algebras generate the algebraic local algebra,
The completion is not involved: this is an equality of algebras of local observables.
For a finite set \(X\) of pair labels, induction on \(X\) gives
For \(X=\varnothing \) the region is empty and contained in \(E_0\), so monotonicity applies. For \(X\cup \{ x_0\} \) with \(x_0\notin X\), the pair \(E_{x_0}\) is disjoint from \(\bigcup _{x\in X}E_x\), so (1091) splits the left-hand side into the join of \(\iota _{E_{x_0}}(\mathcal A_{E_{x_0}})\) with the algebra handled by the induction hypothesis. Every local observable is supported in some finite region \(\Lambda \), which is covered by (1092); monotonicity and (1094) place it in the join.
For a star-algebra automorphism \(\omega \) of the quasi-local algebra propagating within \(\{ -1,0,1\} \), define
Each \(\widehat{\mathcal R}_y\) is contained in \(G\). This is the algebraic join associated with the algebra generated by all \(\mathcal R_y\) in [ 203 , lines 1276–1279 ] . No claim that \(G\) is proper or that it fails to be norm closed is made here.
For every \(x\in \mathbb Z\),
and consequently \(\omega \bigl(j(\mathcal A_{\mathrm{loc}})\bigr)\subseteq G\). Inclusion (1096) is the containment \(\alpha (\mathcal A_{2x}\otimes \mathcal A_{2x+1})\subseteq \mathcal R_{2x}\otimes \mathcal R_{2x+1}\) at [ 203 , lines 1276–1278 ] , in the homogeneous fixed-\(d\) setting; see [ 64 ] .
Write \(S_x\) for the finite image of \(\mathcal A_{E_x}\) in the ordered \(L_x\times P_x\) coordinates. By (1089), \(S_x\) is contained in \(\mathcal R_{2x}\boxtimes \mathcal R_{2x+1}\), which is the underlying vector space of the join of \(\mathcal R_{2x}\otimes \mathbf1\) and \(\mathbf1\otimes \mathcal R_{2x+1}\). The canonical quasi-local map on \(L_x\cup P_x\) sends \(X\otimes \mathbf1\) to the canonical embedding of \(X\in \mathcal R_{2x}\) and \(\mathbf1\otimes Y\) to the canonical embedding of \(Y\in \mathcal R_{2x+1}\), so it maps that join into \(G\). It sends the image of \(A\in \mathcal A_{E_x}\) to \(\omega (j_{E_x}(A))\), which proves (1096). By (1093), every local observable lies in the algebra generated by the \(\iota _{E_x}(\mathcal A_{E_x})\), and \(\omega \circ j\) is a star-algebra homomorphism, so its image lies in \(G\).
The site-indexed support algebras generate the quasi-local algebra in the norm-closed sense,
In [ 203 , lines 1276–1279 ] the algebras \(\mathcal R_y\) are said to generate an algebra containing \(\alpha (\mathcal A(\mathbb Z))\), which equals \(\mathcal A(\mathbb Z)\) because \(\alpha \) is an automorphism. Here this generation statement is expressed by the norm-closure equality (1097) in the homogeneous fixed-\(d\) setting; see [ 64 ] .
An injective star-algebra homomorphism of complex C-star algebras is isometric, so \(\omega \) is continuous and \(\omega ^{-1}(\overline G)\) is closed. By (1096) it contains \(j(\mathcal A_{\mathrm{loc}})\), which is dense, so \(\omega ^{-1}(\overline G)=\mathcal A\). Since \(\omega \) is surjective, every \(z\in \mathcal A\) equals \(\omega (\omega ^{-1}(z))\in \overline G\).
If \(z\in \mathcal A\) satisfies \([z,R]=0\) for every \(y\in \mathbb Z\) and every \(R\in \widehat{\mathcal R}_y\), then \([z,A]=0\) for every \(A\in \mathcal A\). This is the step from commutation with all \(\mathcal R_y\) to commutation in the quasi-local algebra at [ 203 , lines 1279–1282 ] ; see [ 64 ] .
The elements commuting with \(z\) and with \(z^*\) form a norm-closed star-subalgebra. Each \(\widehat{\mathcal R}_y\) is star closed, so the hypothesis applied to \(R^*\) gives \([z^*,R]=0\) as well; hence that star-subalgebra contains every \(\widehat{\mathcal R}_y\), therefore contains \(G\), and being closed it contains \(\overline G=\mathcal A\) by (1097).
For pairwise disjoint finite regions \(\Lambda ,\Gamma ,\Delta \), successive restriction in left–middle–right order gives
Let \(T_x=(L_x\cup P_x)\cup P_{x+1}\). The three regions \(L_x,P_x,P_{x+1}\) are pairwise disjoint, and
Substitute the three pair definitions and compare their six sites.
In the coordinates of Definition 18.10.2.129, the canonical inclusion from \(\Lambda \cup \Gamma \) is \(X\mapsto X\otimes \mathbf1\), and the canonical inclusion from \(\Gamma \cup \Delta \) is \(Y\mapsto \mathbf1\otimes Y\), with the ordered factors \(\Lambda ,\Gamma ,\Delta \).
Restrict each reconstructed configuration to the retained region and its complement. In the first inclusion the complementary coordinates are equal precisely on \(\Delta \); in the second they are equal precisely on \(\Lambda \). The two matrix entries are therefore the left and right overlapping lifts, respectively.
For every \(x\in \mathbb Z\), the canonically embedded support algebras \(\widehat{\mathcal R}_{2x+1}\) and \(\widehat{\mathcal R}_{2x+2}\) commute elementwise.
The source regions \(E_x\) and \(E_{x+1}\) are disjoint, so their canonical quasi-local observables commute. Multiplicativity of \(\omega \) preserves this equality. Embed the two finite images into \(\mathcal A_{T_x}\) and use the tripartite coordinates above to obtain
The overlapping-support theorem, in the order \(\operatorname {Spp}_{\mathrm R}(S_x)\) followed by \(\operatorname {Spp}_{\mathrm L}(S_{x+1})\), gives the claim.
Define \(Q_{2x}=L_x\) and \(Q_{2x+1}=P_x\).
Every element of \(\widehat{\mathcal R}_y\) is supported in \(Q_y\).
Split according to the parity of \(y\) and apply the corresponding localization of \(\widehat{\mathcal R}_{2x}\) or \(\widehat{\mathcal R}_{2x+1}\).
If \(y\ne z\), then \(Q_y\) and \(Q_z\) are disjoint unless
for some \(x\), or unless this ordered pair is reversed.
Write each index in its even or odd form. Two regions of equal parity are disjoint. In the mixed-parity cases, the defining two-site sets intersect exactly for the displayed consecutive odd–even pair.
Distinct members of the canonically embedded family commute elementwise:
This is the homogeneous fixed-\(d\) specialization of the consecutive/disjoint argument in [ 203 , lines 1270–1274 ] , using Lemma sppcomm from lines 1221–1246; compare [ 237 , lines 1174–1194 ] . The four-site localization is established in [ 16 , lines 2313–2329 ] ; see [ 64 ] for the homogeneous scope of the adjacent-generation theorem.
In the exceptional odd–even order apply Theorem 18.10.2.132; the reversed order follows by symmetry. Every remaining ordered pair has disjoint physical supports, so disjoint quasi-locality applies.
Translation by two sites advances each of the three two-site regions by one index:
Add \(2\) to each of the two points of (1082) and compare with the same set at the index \(x+1\).
Let \(X\in M_{I\times J}(\mathbb C)\) and write \(e_{rs}\) for the matrix units of either factor. Then
Every coefficient of the expansion used at [ 203 , lines 1188–1191 ] and [ 237 , lines 1137–1169 ] is therefore a sum of products formed inside the ambient algebra.
Compare entries. On the left of (1105), the entry at \(((i,t),(j,u))\) equals \(X((i,r),(j,s))\) when \(t=u\) and vanishes otherwise. On the right, the summand indexed by \(t\) contributes \(X((i,r),(j,s))\) exactly when both second coordinates equal \(t\), so the sum over \(t\) reproduces the same entry. Exchanging the roles of the two factors yields (1106).
Let \(\Gamma \) and \(\Delta \) be disjoint finite regions and let \(A\in \mathcal A_{\Gamma \cup \Delta }\), written in the ordered \(\Gamma \times \Delta \) coordinates. For configurations \(r,s\in \mathcal C_\Delta \) and \(i,j\in \mathcal C_\Gamma \), the canonical quasi-local copies of the two coefficient families are
where a hat denotes the canonical image in the quasi-local algebra. Both right-hand sides are formed inside the quasi-local algebra alone.
In the bipartite coordinates the inclusion of \(\mathcal A_\Gamma \) is \(X\mapsto X\otimes \mathbf1\) and the inclusion of \(\mathcal A_\Delta \) is \(Y\mapsto \mathbf1\otimes Y\). Transport (1105) and (1106) through the inverse of the bipartite coordinate equivalence, then apply the canonical map of \(\mathcal A_{\Gamma \cup \Delta }\) into the quasi-local algebra, under which a finite-region inclusion leaves the quasi-local observable unchanged.
Let \(\omega \) be a star-algebra automorphism of the homogeneous quasi-local algebra which propagates within \(\{ -1,0,1\} \) and commutes with every lattice translation. Then, for every \(y\in \mathbb Z\),
and in the two parities
The displacement is two sites of the original chain (one blocked cell); the shift automorphism in [ 203 , lines 1267–1268 ] shows that single-site translation exchanges the inequivalent even and odd support algebras.
Covariance of the support algebras under translation is the identity displayed at [ 237 , lines 1218–1226 ] for the algebras defined at [ 237 , lines 1199–1206 ] , and the ordered even and odd factors are equation RR2x at [ 203 , lines 1251–1266 ] . The translation-covariant fixed-\(d\) setting is that of [ 16 , lines 2292–2298 ] .
The statement treats the one-dimensional translation-invariant setting [ 80 ] , with homogeneous cell size \(d\) [ 64 ] .
Fix \(x\) and put \(\Lambda =E_x\), \(\Gamma =L_x\), \(\Delta =P_x\). A finite-region observable belongs to the finite local image exactly when its quasi-local copy lies in the image of \(\mathcal A_\Lambda \) under \(\omega \). Hence, by (1107), the canonical quasi-local copy of \(\mathcal R_{2x}\) is generated by the elements
and the copy of \(\mathcal R_{2x+1}\) is generated by the analogous elements built from (1108) with \(\Gamma \) in place of \(\Delta \). Since a star-algebra automorphism carries the algebra generated by a set to the algebra generated by the image of that set, it suffices to translate the two generating families.
Translation carries a matrix unit of a region to the matrix unit of the translated region at the translated configurations, and covariance gives \(\tau _2(\omega (\widehat B))=\omega (\tau _2(\widehat B))\), whose right-hand side is \(\omega \) applied to the quasi-local copy of the translated observable. Reindexing the summation over \(\mathcal C_\Delta \) along the configuration translation therefore turns (1111) into the same family for the regions \(\Lambda +2\) and \(\Delta +2\), and the translation is a bijection between the two families. By (1104) those regions are \(E_{x+1}\) and \(P_{x+1}\), so the translated family generates \(\widehat{\mathcal R}_{2x+2}\). The odd case is identical with \(\Gamma \) in place of \(\Delta \) and \(L_{x+1}\) in place of \(P_{x+1}\).
Finally, splitting \(y\) by parity and using \(2x+2=2(x+1)\) and \(2x+3=2(x+1)+1\) gives (1109) and (1110).
In [ 16 , lines 2300–2306 ] , eventual constancy of finite-chain conjugation defines a norm-preserving star-algebra automorphism of \(\mathcal A_{\mathrm{loc}}\) satisfying the support bound \(\mathcal N=[-4D^4,4D^4]\cap \mathbb Z\) and translation covariance, extending uniquely to \(\mathcal A\). The following statements develop this direct-limit completion from compatible forward and inverse finite-local actions.
For each finite region \(\Lambda \), let
be star-algebra homomorphisms such that, whenever \(\Lambda \subseteq \Gamma \),
Let \(f,g\colon \mathcal A_{\mathrm{loc}}\to \mathcal A_{\mathrm{loc}}\) be the maps induced by these compatible families. Compatible finite-local automorphism data require
for every \(A\in \mathcal A_\Lambda \).
The compatible families induce star-algebra homomorphisms
Apply the star-algebra universal property to each compatible family.
For every finite region \(\Lambda \) and \(A\in \mathcal A_\Lambda \),
These are the evaluation identities supplied by the universal property.
Compatible finite-local automorphism data determine a star-algebra equivalence
whose forward and inverse maps are \(f\) and \(g\), respectively.
Induct on finite-region representatives in the algebraic direct limit. The two inverse assumptions give
Thus \(f\) and \(g\) are mutually inverse.
For every \(A\in \mathcal A_{\mathrm{loc}}\),
Both identities follow from the defining forward and inverse maps of \(F\).
Assume \(d{\gt}0\). The forward local norm hypothesis is
for every finite region \(\Lambda \) and every \(A\in \mathcal A_\Lambda \).
Under the forward local norm hypothesis, every \(A\in \mathcal A_{\mathrm{loc}}\) satisfies
Induct on finite-region representatives. For \(A=\iota _\Lambda (A_\Lambda )\),
Under the forward local norm hypothesis, for all \(A,B\in \mathcal A_{\mathrm{loc}}\),
Apply the forward norm identity to \(A-B\) to prove that \(F\) is an isometry. Since \(F\circ F^{-1}\) is the identity, the right-inverse law then makes \(F^{-1}\) an isometry as well.
Under the forward local norm hypothesis, every \(A\in \mathcal A_{\mathrm{loc}}\) satisfies
Apply the inverse isometry to the distance from \(A\) to \(0\) and use \(F^{-1}(0)=0\).
Under the forward local norm hypothesis, the algebraic equivalence extends to a star-algebra equivalence
of the quasi-local completion.
The forward norm formula makes \(F\) an isometry, and the inverse law makes \(F^{-1}\) an isometry. Apply the completion extension for star-algebra equivalences to these two continuous maps.
Let \(j\colon \mathcal A_{\mathrm{loc}}\to \mathcal A\) be the canonical completion map. For every \(A\in \mathcal A_{\mathrm{loc}}\),
These are the canonical-image formulas for the continuous extension of a star-algebra equivalence and for its inverse.
For every finite region \(\Lambda \) and \(A\in \mathcal A_\Lambda \),
Substitute \(j_\Lambda =j\circ \iota _\Lambda \) into the dense evaluation formulas and use \(F(\iota _\Lambda (A))=f_\Lambda (A)\) and \(F^{-1}(\iota _\Lambda (A))=g_\Lambda (A)\).
For a finite neighborhood \(\mathcal N\subset \mathbb Z\), the forward family has support bound \(\mathcal N\) if
for every finite region \(\Lambda \) and every \(A\in \mathcal A_\Lambda \).
If the forward family has support bound \(\mathcal N\), then the completed automorphism \(\overline F\) propagates within \(\mathcal N\).
Let \(X=j_\Lambda (A)\) be supported in \(\Lambda \). Choose \(B\in \mathcal A_{\Lambda +\mathcal N}\) such that \(f_\Lambda (A)=\iota _{\Lambda +\mathcal N}(B)\). Then
so the image is supported in \(\Lambda +\mathcal N\).
The forward family commutes with unit translation if, for every finite region \(\Lambda \) and every \(A\in \mathcal A_\Lambda \),
If the finite-local unit-translation formula holds, then every \(A\in \mathcal A_{\mathrm{loc}}\) satisfies
Induct on finite-region representatives and write \(A=\iota _\Lambda (A_\Lambda )\). Then
If the finite-local unit-translation formula holds, then the completed automorphism \(\overline F\) is translation covariant.
By Theorem 18.10.2.49, it suffices to prove that \(\overline F\) commutes with translation by one site. Induct on the completion. On every \(A\in \mathcal A_{\mathrm{loc}}\),
The equality set is closed because both composites are continuous, so the identity extends from the canonical dense subalgebra to the completion.
Let \(d{\gt}0\). Suppose the compatible forward family preserves the local operator norm, has a finite support bound, and satisfies the finite-local unit-translation formula. Then the completed automorphism \(\overline F\) is a one-dimensional QCA.
The support hypothesis supplies a finite forward propagation neighborhood, while the unit-translation formula supplies translation covariance. These are exactly the two defining properties of a one-dimensional QCA.
For \(a\in \mathbb Z\) and \(N\geq 0\), put \(I(a,N)=\{ a,a+1,\ldots ,a+N-1\} \). The site numbering \(i\mapsto a+i\) identifies configurations on \(I(a,N)\) with length-\(N\) configurations. Reindexing both matrix coordinates gives a star-algebra equivalence \(C_{a,N}:\mathcal A_{I(a,N)}\to M_{d^N}(\mathbb C)\). Explicitly, \(C_{a,N}(X)_{\sigma \tau }=X_{\widetilde\sigma \widetilde\tau }\), where \(\widetilde\sigma (a+i)=\sigma _i\). This includes \(N=0\) and the one-dimensional algebra on the empty interval.
Let \(b,c\geq 0\), \(I=I(a,N)\) and \(J=I(a-b,b+N+c)\). Then \(I\subseteq J\). For configurations \(\sigma ,\tau \) on \(b+N+c\) consecutive sites,
where \(M=\{ b,b+1,\ldots ,b+N-1\} \) and \(\sigma |_M\) denotes the configuration \(i\mapsto \sigma _{b+i}\) on \(N\) sites. This is the identity-tensor inclusion of [ 16 , Appendix ] expressed in increasing integer-site coordinates.
Restriction to \(I\) selects the middle \(N\) coordinates. Equality of the two configurations on \(J\setminus I\) is equality on all added sites. Substitute these identifications into the local inclusion formula.
For \(d{\gt}0\) and \(a\in \mathbb Z\), coordinate transport and the finite-region inclusion give a star-algebra inclusion \(j_{a,k}:M_{d^k}(\mathbb C)\to \mathcal A\), including \(k=0\). It preserves the matrix operator norm: \(\| j_{a,k}(X)\| =\| X\| \). This is the interval observable convention in [ 225 , Section 3 ] .
The coordinate equivalence is isometric between the finite matrix algebras, and the finite-region inclusion preserves norm in the completion.
A compatible family of finite-region states consists of complex-linear functionals \(f_\Lambda \colon \mathcal A_\Lambda \to \mathbb {C}\), indexed by finite regions \(\Lambda \Subset \mathbb {Z}\), such that, for every inclusion \(\Lambda \subseteq \Gamma \) and every \(X\in \mathcal A_\Lambda \),
Compatibility determines a complex-linear functional \(f_{\mathrm{loc}}\colon \mathcal A_{\mathrm{loc}}\to \mathbb {C}\) by \(f_{\mathrm{loc}}(\iota _\Lambda (X))=f_\Lambda (X)\). For \(d{\gt}0\), this functional is continuous in the operator-norm topology.
For every finite region \(\Lambda \) and \(X\in \mathcal A_\Lambda \), \(f_{\mathrm{loc}}(\iota _\Lambda (X))=f_\Lambda (X)\). If \(d{\gt}0\), then \(|f_{\mathrm{loc}}(A)|\leq \lVert A\rVert \) for every \(A\in \mathcal A_{\mathrm{loc}}\).
The direct-limit property gives the stated values. Every algebraic local observable has a finite-region representative, and its norm is the norm of that representative. Thus \(|f_{\mathrm{loc}}(\iota _\Lambda (X))| =|f_\Lambda (X)|\leq \lVert X\rVert =\lVert \iota _\Lambda (X)\rVert \).
For \(d{\gt}0\), let \(\omega \colon \mathcal A\to \mathbb {C}\) be the continuous linear extension of \(f_{\mathrm{loc}}\) to the operator-norm completion.
For every algebraic local observable \(A\), one has \(\omega (j(A))=f_{\mathrm{loc}}(A)\). For every finite region \(\Lambda \) and \(X\in \mathcal A_\Lambda \), one has \(\omega (j_\Lambda (X))=f_\Lambda (X)\).
Continuous extension preserves the values on the original normed space. Apply this to \(A=\iota _\Lambda (X)\) for the finite-region formula.
Every compatible family of finite-region states, with \(d{\gt}0\), has a unique continuous complex-linear extension \(\omega \colon \mathcal A\to \mathbb {C}\) with the prescribed finite-region values. It satisfies \(\omega (I)=1\), \(\lVert \omega \rVert =1\), and, for every \(A\in \mathcal A\), \(|\omega (A)|\leq \lVert A\rVert \) and \(\omega (A^\dagger A)\geq 0\). Compatibility of the finite-region functionals is an explicit hypothesis.
The sets defined by \(|\omega (A)|\leq \lVert A\rVert \) and \(\omega (A^\dagger A)\geq 0\) are closed, since multiplication, involution, and \(\omega \) are continuous. These inequalities hold on the dense algebraic local subalgebra, hence on its completion. Evaluation at a finite-region identity gives \(\omega (I)=1\) and \(1\leq \lVert \omega \rVert \); contractivity gives the reverse inequality. Two continuous extensions agree on all finite-region observables, then on the algebraic local algebra, and therefore on its completion.
Let \(d{\gt}0\), and let \(\mathcal A_d\) denote the quasi-local observable algebra. Its state space consists of all continuous complex-linear functionals \(\omega \) such that \(\| \omega \| =1\), \(\omega (I)=1\), and \(\omega (X^*X)\ge 0\) for every \(X\in \mathcal A_d\). A state is pure if it is an extreme point of this set, viewed as a real convex set. Translation invariance is not required of these functionals. These are the state and purity conventions in [ 225 , Section 1 and Section 3 ] .
Let \(\phi ,\psi \) be states, let \(0{\lt}t{\lt}1\), and set \(\omega =(1-t)\phi +t\psi \). If \(\omega (X^*X)=0\), then \(\phi (X^*X)=0\). If \(\omega \) is a state, \(P=P^*=P^2\), and \(\omega (P)=1\), then \(\phi (P)=1\).
Positivity gives two nonnegative real numbers whose strictly positive weighted sum is zero, so both numbers vanish. Apply this to \(I-P\); \((I-P)^*(I-P)=I-P\) and normalization gives the projection assertion.
Let \(\omega \) be a state, and let \((P_i)_{i\in J}\) be any family of self-adjoint projections with \(\omega (P_i)=1\). Suppose every state \(\phi \) satisfying \(\phi (P_i)=1\) for every \(i\in J\) equals \(\omega \). Then \(\omega \) is pure.
In a nontrivial convex decomposition of \(\omega \), each constituent has expectation one on every \(P_i\). The uniqueness hypothesis forces the left constituent to equal \(\omega \), which is the extreme-point condition.
The normalized positive continuous functionals on the quasi-local algebra form a convex set over the real numbers.
If \(\varphi ,\psi \) are states and \(a,b\geq 0\) satisfy \(a+b=1\), then \(\| a\varphi +b\psi \| \leq a+b=1\) and \((a\varphi +b\psi )(I)=1\). Since \(\| I\| =1\), evaluation at the identity gives the reverse norm bound. Positivity follows by taking the same convex combination of their nonnegative values on adjoint squares.
Let \(\varphi \) be pure among all states of the quasi-local algebra. Suppose that \(\omega _i\) are states indexed by a finite set, that \(w_i\geq 0\) and \(\sum _iw_i=1\), and that \(\varphi =\sum _iw_i\omega _i\). Then \(\varphi =\omega _i\) for some \(i\). No translation-invariance condition is imposed on these states.
The state \(\varphi \) belongs to the convex hull of the \(\omega _i\). This hull is contained in the full state space, so extremality in the state space implies extremality in the smaller hull. Every extreme point of the convex hull of a finite set belongs to that set.
For \(L{\gt}0\), \(a\in \mathbb Z\) and \(N\geq 0\), the expansion of the blocked interval \(I(a,N)\) is
Negative starts and the empty interval are included.
Euclidean division by \(L\) shows that the quotient \(q=\lfloor z/L\rfloor \) of an integer \(z\) satisfies \(a\leq q{\lt}a+N\) exactly when \(aL\leq z{\lt}(a+N)L\).
Let \(L{\gt}0\), \(d\geq 0\), \(a\in \mathbb Z\) and \(N\geq 0\). Let \(e_{N,L}\) decode the \(N\) blocked spins into \(NL\) consecutive spins, placing residue \(r\) of blocked site \(i\) at site \(Li+r\). Define the matrix reindexing \(\mathcal R_{N,L}(X)_{\sigma \tau } =X_{e_{N,L}^{-1}(\sigma ),e_{N,L}^{-1}(\tau )}\). Then
Here the target region is identified using \(\widehat{I(a,N)}_L=I(aL,NL)\). This expresses the site grouping of [ 16 , Appendix, lines 2308 and 2313–2320 ] in consecutive interval coordinates.
The site \(L(a+i)+r\) has interval coordinate \(Li+r\) relative to \(aL\). Thus decoding followed by consecutive numbering agrees with flattening the blocked configurations. Apply this identity to both matrix indices.
For \(d{\gt}0\), \(L{\gt}0\), \(a\in \mathbb Z\), \(N\geq 0\) and \(X\in M_{(d^L)^N}(\mathbb C)\),
Evaluate the completed blocking equivalence on the finite interval representative, then apply the finite coordinate identity.
Let \(d_1,d_2{\gt}0\) and let \(e:\mathcal A_{d_1}\to \mathcal A_{d_2}\) be a star-algebra isomorphism. The induced continuous complex-linear equivalence between functional spaces is \(T_e\omega =\omega \circ e^{-1}\); thus \((T_e\omega )(X)=\omega (e^{-1}X)\).
Under the preceding hypotheses, \(\| T_e\omega \| =\| \omega \| \). Moreover, \(T_e\) maps the entire state space of \(\mathcal A_{d_1}\) onto the entire state space of \(\mathcal A_{d_2}\), and \(T_e\omega \) is pure if and only if \(\omega \) is pure. No translation invariance is assumed. Purity has the meaning used in [ 225 , Section 3, lines 1469–1482 ] .
A star-algebra isomorphism of complex C-star algebras is isometric. Inverse precomposition therefore preserves the dual norm. It also preserves the identity and adjoint squares, so it maps the state spaces onto one another. Its restriction to real scalars is a linear equivalence, and linear equivalences carry extreme points to extreme points.
Let \(d,L{\gt}0\) and let \(\mathcal B_L:\mathcal A_{d^L}\to \mathcal A_d\) be the site-blocking isomorphism. A continuous functional \(\omega \) on the blocked chain defines the original-lattice functional \(T_L\omega =\omega \circ \mathcal B_L^{-1}\). This is the state transport associated with the regrouping of sites in [ 225 , lines 825–836 ] .
The functional \(T_L\omega \) has the same norm as \(\omega \), is a state exactly when \(\omega \) is a state, and is pure exactly when \(\omega \) is pure. This applies to all state functionals, without an invariance condition under translations.
Apply the star-algebra equivalence theorem to \(\mathcal B_L\).
18.10.3 Full-matrix presentation of a factor with scalar centre
Let \(I\) be a finite nonempty set and let \(S\subseteq M_I(\mathbb {C})\) be a unital star-subalgebra whose centre consists of the multiples of its unit,
Then there is an \(r\geq 1\) with
the first isomorphism being one of star-algebras.
This is the single-block case of the structure theorem for finite-dimensional \(C^*\)-algebras [ 237 , Proposition Csform, lines 2082–2098 ] for an algebra presented inside a matrix algebra; see [ 22 ] .
A star-subalgebra of a complex matrix algebra is semisimple, so it is isomorphic to a finite product \(\prod _{k=1}^{m}M_{d_k}(\mathbb {C})\) with every \(d_k\geq 1\). The element that is the unit in the \(k\)-th coordinate and zero in the others is central, hence by (1141) a multiple \(\lambda \mathbf1\); comparing its \(k\)-th coordinate with another one gives \(\lambda =1\) and \(\lambda =0\), so \(m\leq 1\). The unit of \(M_I(\mathbb {C})\) is nonzero because \(I\) is nonempty, so \(m=1\) and \(S\) is a simple ring. The Wedderburn theorem over the algebraically closed field \(\mathbb {C}\) then produces an \(r\geq 1\) and an isomorphism of \(\mathbb {C}\)-algebras \(S\cong M_{r}(\mathbb {C})\), and conjugating it by a positive definite matrix makes it preserve adjoints [ 216 , “A \(*\)-subalgebra with scalar centre is a full matrix algebra” ] . A star-isomorphism is in particular a \(\mathbb {C}\)-linear isomorphism, and \(\dim _{\mathbb {C}}M_{r}(\mathbb {C})=r^2\) [ 216 , “Dimension of a subalgebra presented as a full matrix algebra” ] .
Gross, Nesme, Vogts and Werner apply this conclusion to the site-indexed support algebras [ 203 , lines 1276–1282 ] : an element of \(\mathcal R_x\) commuting with all of \(\mathcal R_x\) commutes with every \(\mathcal R_y\), hence with the algebra they generate, which is the whole quasi-local algebra; its centre is scalar, so (1141) holds for \(\mathcal R_x\) and \(\mathcal R_x\cong M_{r(x)}(\mathbb {C})\).
18.11 Depth estimates for a merging tree
The merging construction of [ 240 ] gives numerical recurrences for circuit depth. The results below concern those recurrences; they do not assert that an arbitrary tensor admits the required circuit construction or conditioning bounds.
Let \(T_j,q_j\) be real sequences, let \(a\in \mathbb R\) and \(C\geq 0\), and suppose \(q_j\geq 1\) for every nonnegative integer \(j\). If
then for every nonnegative integer \(L\),
Induct on \(L\). The initial case is \(T_0\leq a\). At the induction step, use \(\prod _{j{\lt}L}q_j\geq 1\) to bound the additive overhead by \(C2^{L+1}\prod _{j{\lt}L}q_j\). Multiplication by \(q_L\geq 0\) gives
Under the hypotheses of Theorem 18.11.1, suppose also \(a\geq 0\). Let \(L,c\) be nonnegative integers. If \(\prod _{j{\lt}L}q_j\leq (2^L)^c\), then
Substitute the assumed product bound into the preceding estimate. Its coefficient \(2^L(a+CL)\) is nonnegative.
Let \(T_j\) be a real sequence, \(a\in \mathbb R\), \(C\geq 0\), and \(q\geq 1\). Suppose \(T_0\leq a\) and \(T_{j+1}\leq q(2T_j+C2^{j+1})\) for every nonnegative integer \(j\). Then
Apply the product estimate to \(q_j=q\) and use \(2^Lq^L=(2q)^L\).
For every real \(C\) and every nonnegative integer \(L\),
Expand \(2^{L+1}=2\cdot 2^L\) and distribute multiplication.
For \(N=2^L\), the sequence \(T_L=CL2^L\) has order \(N\log N\) when \(C{\gt}0\). Thus a recurrence with conditioning equal to one need not yield a linear estimate. This numerical observation is not a lower bound for implementing an MPU.
18.11.1 Boundary Gram matrices of a parity rotation
The factorization \(I_A\otimes cI_B+P_A\otimes isP_B\), with Hermitian involutions \(P_A,P_B\), gives the following two Gram matrices. Their algebraic inverse-trace identity is distinct from the identification of all admissible boundary states and the infimum defining the conditioning cost.
For complex numbers \(c,s,x,y\), define
When the parameters are real, \(x,y\) represent the expectations of the two involutions in exterior density operators.
For the matrices of Definition 18.11.1.1,
The identity holds for arbitrary complex parameters, with the convention that the inverse of a singular matrix and the reciprocal of zero are zero.
Express each inverse as its adjugate divided by its determinant. The determinants are \(1-x^2\) and \(c^2s^2(1-y^2)\). The mixed off-diagonal contributions to the trace cancel, leaving numerator \(c^2+s^2\).
18.11.2 Interval isometries for product-projection phase gates
Let \(P_j\) be orthogonal projections on the individual sites and \(|z|=1\). The unitary \(I+(z-1)\bigotimes _jP_j\) is a product-projection instance of an MPO-projector unitary from [ 240 ] . The following boundary frames supply interval isometries directly, without requiring realization by exterior density operators.
For a square complex matrix \(P\) and a complex number \(z\), define
The displayed components are stacked vertically. For the interior map, their order is the lexicographic order of the two bond labels.
If \(P\) is an orthogonal projection, the prefix and interior maps of Definition 18.11.2.1 are isometries. If also \(|z|=1\), the suffix map is an isometry.
Sum the Gram products of the displayed components, using \(P^\dagger =P\) and \(P^2=P\). For the prefix and interior maps this gives \(I\). For the suffix map, the coefficient of \(P\) is
Define
The columns of \(C_L,C_R\) are the left and right bond vectors, respectively. The matrix \(K\) gives the coefficients of their bilinear contraction.
The frames in Definition 18.11.2.3 are invertible and obey
Multiply the two-by-two matrices. Their determinants are \(\det C_L=1/2\) and \(\det C_R=1\). Evaluate the inverse Gram matrices by their adjugates and determinants.
The bond contraction in Theorem 18.11.2.4 identifies matching tensor labels. For adjacent intervals it multiplies \(P_{jk}\) and \(P_{k+1,l}\) by their tensor product, giving \(P_{jl}\). Its norm is two and is independent of the phase \(z\).
18.11.3 Finite coefficient alphabets at a cut
A coefficient matrix at a cut factors through the corresponding MPO bond. When its coefficients belong to a finite alphabet, the number of distinct residual coefficient functions can be bounded without a smallest-Schmidt-value assumption.
Let \(M\) be a matrix over a field \(K\), indexed by an arbitrary row set \(I\) and a finite column set \(J\). There is a subset \(J_0\subseteq J\) of cardinality \(\operatorname {rank}M\) such that two rows of \(M\) are equal whenever they agree at every column in \(J_0\).
Choose a basis of the column space among the columns of \(M\). Agreement at these columns is preserved under linear combinations, so it implies agreement at every column.
Let \(M\) have an arbitrary row set and a finite column set over a field. Suppose every entry belongs to a finite set \(S\). The set of distinct rows is finite and has cardinality at most \(|S|^{\operatorname {rank}M}\). If also \(S\) is nonempty and \(\operatorname {rank}M\leq D\), this number is at most \(|S|^D\).
Restrict each row to the chosen columns. This injects the set of distinct rows into a set of \(|S|^{\operatorname {rank}M}\) functions. The rank-bound consequence uses \(|S|\geq 1\).
Let \(A\) and \(B\) be matrices over a field with compatible middle index set of cardinality \(D\) and a finite column set for \(B\). Suppose every entry of \(AB\) belongs to a nonempty finite set \(S\). The set of distinct rows of \(AB\) is finite and has cardinality at most \(|S|^D\). In particular, zero-one entries give at most \(2^D\) distinct rows.
Use \(\operatorname {rank}(AB)\leq \operatorname {rank}A\leq D\). For the zero-one specialization, take \(S=\{ 0,1\} \).
18.11.4 Unit-circle geometry and diagonal circuits
The following elementary geometry is the rank-two step in the diagonal circuit argument of [ 250 ] .
Let \(u,v,w\in \mathbb C\) have the same real part and the same squared modulus. Then \(u=v\), \(u=w\), or \(v=w\).
Equality of squared moduli gives equal squares of the imaginary parts. Three real numbers with the same square have at most two values.
Let \(u,v,w\) be three distinct complex numbers of modulus one. If \(\operatorname {Re}(zu)=\operatorname {Re}(zv)=\operatorname {Re}(zw)\), then \(z=0\).
The three products have the same real part and the same modulus. Two are equal; their factors are distinct, so \(z=0\).
Let \(u,v,w\) be distinct complex numbers of modulus one. If \(|a+bu|=|a+bv|=|a+bw|=1\), then \(a=0\) or \(b=0\).
Expand the squared moduli. The real parts of \(a\overline b\overline u\), \(a\overline b\overline v\) and \(a\overline b\overline w\) agree. Thus \(a\overline b=0\).
Let \(I,J\) be sets with \(J\) nonempty. Suppose \(a,b:I\to \mathbb C\) and \(t:J\to \mathbb C\) satisfy \(|t_j|=1\) and \(|a_i+b_it_j|=1\) for all \(i,j\). Then either \(a_i=0\) or \(b_i=0\) for every \(i\), or there are \(j_0,j_1\in J\) such that \(t_j\in \{ t_{j_0},t_{j_1}\} \) for every \(j\in J\).
If \(t\) has three distinct values, apply the preceding theorem to each row. Otherwise choose one value, and, if it exists, a second distinct value. There can be no third.
The construction of [ 250 ] gives an exact circuit with \(O(N^{\log _2 3})\) gates for any diagonal MPU with consecutive operator Schmidt ranks at most two. A sequential traversal uses \(O(N)\) auxiliary qubits; a parallel version uses \(O(N^{\log _2 3})\) auxiliary qubits and logarithmic depth. For diagonal MPUs of arbitrary maximal bond dimension \(D\), reversible phase evaluation gives operator-norm error at most \(\varepsilon \) with resources polynomial in \(N,D,\log (1/\varepsilon )\). These estimates concern diagonal operators; Theorem 18.12.8 gives a separate construction for arbitrary unitaries of consecutive cut rank at most two.
Let \(K\) be a field, \(P,Q\) finite sets, and let \(A:I\times P\to K\), \(B:P\times J\to K\), \(C:I\times Q\to K\), and \(E:Q\times J\to K\) be matrices. For \(s,t\in K\), the matrix \(H_{ij}=s(AB)_{ij}(CE)_{ij}+t\) factors through the index set \((P\times Q)\sqcup \{ *\} \).
At \((p,q)\) use left entry \(sA_{ip}C_{iq}\) and right entry \(B_{pj}E_{qj}\). At \(*\) use left entry \(t\) and right entry \(1\). Distributivity gives their product equal to \(H\).
Under the preceding hypotheses suppose \(J\) is finite and every entry of \(H\) is zero or one. The set of distinct rows of \(H\) is finite and has cardinality at most \(2^{|P||Q|+1}\). In particular, \(|P|=|Q|=2\) gives at most 32 rows.
Apply the finite-alphabet row bound to the displayed factorization. Its middle index has cardinality \(|P||Q|+1\).
18.12 Exact circuits for matrix product unitaries
The constructions of [ 249 ] give exact circuits for unitaries with bounded consecutive operator Schmidt ranks. The rank-two arguments are followed by a general construction using positive metrics in the real affine spaces of prefix Gram matrices. The latter removes the spectral conditioning hypothesis at every fixed bond bound.
Let \(K\) be a field and let \(J,A\) be finite sets. For a matrix \(M:I\times (J\times A)\to K\) and \(f:A\to K\), put \(M_f(i,j)=\sum _a M(i,(j,a))f(a)\). Then \(\operatorname {rank}M_f\leq \operatorname {rank}M\). Similarly, for finite \(I\) and a matrix \(M:(A\times I)\times J\to K\), contraction \(M_f(i,j)=\sum _a f(a)M((a,i),j)\) does not increase rank.
In the first case write \(M_f=MQ\), where \(Q_{(j',a),j}=\delta _{j',j}f(a)\). In the second write \(M_f=PM\), where \(P_{i,(a,i')}=\delta _{i,i'}f(a)\). Rank cannot increase under multiplication on either side.
Let \(T_j\) be a real sequence, let \(a\in \mathbb R\), \(C\geq 0\) and \(r\geq 2\). Suppose \(T_0\leq a\) and \(T_{j+1}\leq rT_j+C\) for every nonnegative integer \(j\). Then \(T_L\leq (a+C)r^L-C\) for every nonnegative integer \(L\).
Induct on \(L\). At the step use \(r((a+C)r^L-C)+C\leq (a+C)r^{L+1}-C\), since \((r-2)C\geq 0\).
Let square complex matrices \(E,F\) satisfy \(E^\dagger E+F^\dagger F=EE^\dagger +FF^\dagger =I\). There are unitaries \(V,W\) such that \(E=V\sqrt{E^\dagger E}\), \(F=W\sqrt{F^\dagger F}\), and \(E^\dagger E\) commutes with \(V^\dagger W\).
The equality-of-Gram-matrices extension theorem supplies unitary polar factors, including at zero singular values. Their output Gram matrices are \(V(E^\dagger E)V^\dagger \) and \(W(F^\dagger F)W^\dagger \). The two completeness identities imply \(V(E^\dagger E)V^\dagger =W(E^\dagger E)W^\dagger \). Multiplication by \(V^\dagger \) on the left and \(W\) on the right gives the commutation assertion.
Let \(P\) be an orthogonal projection and put \(\mathcal E(P)=\left(\begin{smallmatrix} P & I-P \\ I-P & P \end{smallmatrix}\right)\). Then \(\mathcal E(P)\) is a Hermitian unitary. Let \(Q_0=\left(\begin{smallmatrix} I & 0 \\ 0 & 0 \end{smallmatrix}\right)\) be the zero-record projection. For any square matrices \(X_0,X_1\) on another factor,
Thus every input with its record qubit zero has its record zero at the end.
Multiply the blocks using \(P^2=P\), \(P(I-P)=(I-P)P=0\), and \((I-P)^2=I-P\). Matrices acting on distinct tensor factors commute.
Put \(\mathcal H=2^{-1/2} \left(\begin{smallmatrix} I & I \\ I & -I \end{smallmatrix}\right)\). Then \(\mathcal H\operatorname {diag}(I,R)\mathcal H =\mathcal E((I+R)/2)\). If \(R\) is a Hermitian involution, \((I+R)/2\) is an orthogonal projection. For a unitary \(B\) and any square matrix \(C\),
The first identity follows by multiplying the Hadamard blocks. For the second, multiply those same blocks with \(B\) and \(BB^\dagger C=C\). The projection assertion follows from \(R^2=I\) and \(R^\dagger =R\).
Let square complex matrices \(E,F\) satisfy \(E^\dagger E+F^\dagger F=EE^\dagger +FF^\dagger =I\). There are unitaries \(L,R\) and diagonal matrices \(D_E,D_F\) with \(E=LD_ER\) and \(F=LD_FR\).
Put \(H=E^\dagger E\), and choose unitary polar extensions \(E=V\sqrt H\) and \(F=W\sqrt{I-H}\). The second normalization gives \(VHV^\dagger =WHW^\dagger \). Thus \(V^\dagger W\) commutes with \(H\); diagonalize both on the eigenspaces of \(H\). The resulting left and right bases give the simultaneous singular-value decomposition.
Let \(U\) be a bipartite unitary of operator Schmidt rank two. After possibly interchanging the factors, there are unitaries \(A_0,A_1\) and matrices \(B_0,B_1\) such that \(U=A_0\otimes B_0+A_1\otimes B_1\). The matrices \(B_\pm =B_0\pm B_1\) are unitary, and \(R=B_+^\dagger B_-\) is a Hermitian involution. The \(A_s\) belong to the first Schmidt space of \(U\) and the \(B_\pm \) to the second.
Take a Hilbert–Schmidt orthogonal Schmidt decomposition. Normalizing one pair and tracing the two unitary identities of \(U\) gives the hypotheses of Lemma 18.12.6 for the opposite pair. Repeat on the other side. Thus \(U\) is equivalent under local left and right unitary multiplication to a diagonal operator with a unit-modulus coefficient matrix of rank two. The circle–line argument of [ 249 , Lemma 3 ] gives two projective row types or two projective column types. This expresses the diagonal operator as two controlled phase terms. Restoring the local factors gives the claimed decomposition; \(R\) is unitarily conjugate to the difference of the two complementary sector projections. The two factor pairs are independent, so they span the original Schmidt spaces.
Let \(N\geq 1\). Every \(N\)-qubit unitary whose operator Schmidt rank is at most two at each consecutive cut has an exact circuit of \(O(N^{\log _2 6})\) one- and two-qubit gates, with \(O(\log (N+1))\) auxiliary qubits initialized and returned to zero. Arbitrary pairs may interact. Routing on a line gives gate count and depth \(O(N^{1+\log _2 6})\) with the same auxiliary-space bound.
At each balanced split use the two-sector decomposition. A clean qubit records the eigenvalue of \(R\) by a Hadamard, controlled \(R\), and a second Hadamard. Apply \(A_0,A_1\) conditioned on the record, erase it, and apply \(B_+\). Since \(R=B_+^\dagger B_-\) and \(R=R^\dagger \), the erasure and the final \(B_+\) combine into two controlled child calls. Recording takes two calls, and the \(A_s\) take two more, for six in total. An external control is retained by computing its conjunction with the record into two reusable clean qubits.
Every child is in an original Schmidt space, so contraction on the opposite interval preserves all internal rank bounds. Adjoint also preserves these ranks. The recursion has \(O(6^{\lceil \log _2N\rceil })\) nodes and uses three auxiliary qubits per level, with storage reused between calls. At rank one there are only two unitary factors. At one site a controlled unitary is an allowed two-qubit gate. The local diagonalizing unitaries used in the structural proof are never separately implemented.
18.13 Limits of recursion inside the original Schmidt spaces
The following finite-dimensional examples are discussed in [ 252 ] . They constrain a possible recursive proof, rather than providing a circuit complexity lower bound.
Let \((J_a)_{a=1}^3\) be the Cartesian spin-one matrices, \((\sigma _a)_{a=1}^3\) the Pauli matrices, and \(H=\sum _aJ_a\otimes \sigma _a\). Then \(H=H^\dagger \) and \(H^2=2I-H\). Consequently \(U=(I+2H)/3\) is unitary. Adjoining the identity on a two-dimensional sector gives the three-qubit unitary \(\widehat U=U\oplus I_2\).
Direct multiplication gives the two identities for \(H\). Substitution yields \(U^\dagger U=U^2=I\). The direct-sum extension is unitary on both orthogonal sectors.
Put \(W=\{ aI_3+K:a\in \mathbb C,\ K^T=-K\} \). Every unitary matrix in \(W\) is scalar, and \(W\) is not spanned by its unitary matrices.
A skew-symmetric matrix of odd size has a nonzero kernel vector. Norm preservation on that vector forces \(|a|=1\). Taking the trace of \((aI+K)^\dagger (aI+K)=I\) gives \(3=3|a|^2+\operatorname {tr}(K^\dagger K)\), hence \(K=0\). The nonzero spin matrix \(J_1\) belongs to \(W\) and is not scalar.
Put \(D=\operatorname {diag}(1/3,1/3,1/3,1)\) and \(\widehat W=\{ aD+(K\oplus 0):a\in \mathbb C,\ K^T=-K\} \). No matrix in \(\widehat W\) is unitary.
The last coordinate forces \(|a|=1\). The first three coordinates would give the unitary matrix \(aI_3/3+K\). The preceding theorem forces \(K=0\), so its diagonal forces \(|a|=3\), a contradiction.
The spin-one reflection has operator Schmidt rank four and left Schmidt space \(W\). Its three-qubit extension has the same rank and left Schmidt space \(\widehat W\). Thus an original Schmidt space of a unitary can fail to have even one unitary element.
The four left factors \(I,J_1,J_2,J_3\) are linearly independent, as are the four right factors \(I,\sigma _1,\sigma _2,\sigma _3\). In the extension, replace the left identity coefficient by \(D\) and the spin matrices by \(J_a\oplus 0\). Both factor families remain independent. Their spans are precisely the stated spaces.
For a real vector \(v\), the matrix \(v\cdot \sigma \) is Hermitian and its square is \(\| v\| _2^2I\). Let the eight vectors \(n_j\) be the rows of
Each vector has Euclidean norm one. Hence each \(n_j\cdot \sigma \) and the controlled operator \(V=\sum _j(n_j\cdot \sigma )\otimes |j\rangle \langle j|\) are unitary.
Expand the two-dimensional Pauli matrices. Each of the eight integer rows has squared length \(225\). The controlled operator is block diagonal in its control label, so unitarity follows from unitarity of each block.
Let \(T(v)=\operatorname {diag}(v\cdot n_j)\) for \(v\in \mathbb C^3\), and put \(B_a=T(e_a)\). The map \(T\) is injective, its range has complex dimension three, and its range is \(\operatorname {span}_{\mathbb C}\{ B_1,B_2,B_3\} \). It contains no unitary matrix. The controlled Pauli operator satisfies \(V=\sum _{a=1}^3\sigma _a\otimes B_a\).
The first three diagonal entries recover the coordinates of \(v\). Unit modulus at the first six entries would force those coordinates to have modulus one and pairwise zero real inner products. Three nonzero pairwise orthogonal vectors in the real plane \(\mathbb C\) would be linearly independent, contradicting its real dimension two. The range and tensor expansion follow by linearity of the displayed coefficients.
There is a four-qubit unitary with an open-boundary matrix product representation of bond dimensions \(3,3,2\) whose right Schmidt space at the first cut contains no unitary matrix.
Let \(q_0=e_1\), \(q_1=e_2\), \(q_2=e_3\), \(q_3=(3e_1+4e_2)/5\), and \(O=I-2\mathbf1\mathbf1^T/3\), with \(\mathbf1=(1,1,1)^T\). Put \(n_j=q_j\) and \(n_{j+4}=Oq_j\) for \(0\leq j{\lt}4\). The controlled Pauli operator \(V=\sum _{j=0}^7(n_j\cdot \sigma )\otimes |j\rangle \langle j|\) is unitary. At the second cut its coefficient vectors \((q_j,Oq_j)\) span a space of dimension three; at the last cut the right factors are diagonal one-qubit matrices. Its right Schmidt space at the first cut consists of \(\operatorname {diag}(v\cdot n_j)\), for \(v\in \mathbb C^3\). Unitarity would give \(|v_1|=|v_2|=|v_3|=1\) and \(\operatorname {Re}(v_a\overline{v_b})=0\) for all distinct \(a,b\). The mixed vector \(q_3\) gives the first orthogonality equation, and \(Oe_1,Oe_2\) give the other two. Three nonzero pairwise orthogonal vectors in the real plane \(\mathbb C\) are impossible.
Let \(n_0\in \mathbb R^3\) be a unit vector and \(O_i\in O(3)\). Put \(n(x)=O_1^{x_1}\cdots O_n^{x_n}n_0\) and \(U=\sum _x(n(x)\cdot \sigma )\otimes |x\rangle \langle x|\). This unitary has an open-boundary matrix product representation of maximal bond dimension at most three, and an exact circuit with \(2n\) two-qubit gates, at most \(n+1\) one-qubit gates, and no auxiliary qubits. With its target at one end of a line, it has an adjacent-gate circuit of size and depth \(O(n)\).
Write \(s_i=\det O_i\) and \(R_i=s_iO_i\in SO(3)\). A rotation through angle \(\theta \) about unit axis \(u\) lifts to \(V_i=\cos (\theta /2)I-i\sin (\theta /2)(u\cdot \sigma )\). The Pauli product rule gives \(V_i(v\cdot \sigma )V_i^\dagger =(R_iv)\cdot \sigma \). Thus, with \(W(x)=V_1^{x_1}\cdots V_n^{x_n}\), \(n(x)\cdot \sigma =(\prod _i s_i^{x_i}) W(x)(n_0\cdot \sigma )W(x)^\dagger \). Apply the two controlled products and the central target gate; each \(s_i=-1\) contributes a \(Z\) on its control. On a line, move the target past the controls during the first product and return it during the second, using two sweeps of adjacent swaps. Every logical position is restored.
Let \(n,t\geq 1\) and \(U=\sum _{y\in \{ 0,1\} ^n}|y\rangle \langle y|\otimes V(y)\) be a unitary with an open-boundary matrix product representation of maximal bond dimension \(D\), where \(V(y)\) acts on \(t\) qubits. Put \(N=n+t\). For \(0{\lt}\varepsilon {\lt}1\), there is a nonuniform circuit of \(\operatorname {poly}(N,D,2^t,\log (1/\varepsilon ))\) one- and two-qubit gates whose implemented physical unitary \(\widetilde U\) satisfies \(\| \widetilde U-U\| \leq \varepsilon \). The number of auxiliary qubits has the same polynomial bound, and all auxiliaries return exactly to zero. In particular, \(t\leq c\log _2N\) for a fixed \(c\) gives polynomial resources in \(N,D,\log (1/\varepsilon )\).
Put \(q=2^t\). A right-canonical representation of the normalized Choi vector has letter matrices of norm at most one. Compute the \(q^2\) block entries reversibly using matrix–vector contractions. Largest-entry-pivoted QR decomposes each computed block into \(O(q^2)\) two-level rotations and row permutations. Compare the numerical procedure to exact QR with the same pivot choices. Pivots remain at least \(1/(4\sqrt q)\); conservative error amplification is at most \((Cq)^{q^2}\). Its logarithm requires only polynomially many precision bits:
Convert the recorded rotations to binary angles, retaining all diagonal phases. A Gray path of length at most \(t\) implements each two-level operation using basis-pattern controls, with reusable conjunction qubits. Uniform block approximation gives \(\| \widetilde U-U\| =\max _y\| \widetilde V(y)-V(y)\| \). Since every computed bit depends only on unchanged controls, reversing the arithmetic erases all auxiliaries exactly. The detailed finite-precision proof is in [ 252 ] .
18.14 Completions and general approximation
Let \(J,V:\mathcal H\to \mathcal K\) be isometries between finite-dimensional complex Hilbert spaces with \(J^\dagger V=0\). Then \((V-J)^\dagger (V-J)=2I\), and \(S=I-(V-J)(V-J)^\dagger \) is a unitary satisfying \(SJ=V\) and \(SV=J\).
Orthogonality gives both cross Gram terms zero. Put \(W=V-J\); then \(W^\dagger W=2I\) and \((WW^\dagger )^2=2WW^\dagger \). Thus \(S=S^\dagger \) and \(S^2=I\). Multiplication by \(J\) or \(V\) gives the two asserted actions.
For a Kraus isometry \(V\psi =\sum _{a=1}^r A_a\psi \otimes |a\rangle \), take \(J\psi =\psi \otimes |0\rangle \). The completion uses only \(I,A_a,A_a^\dagger ,A_aA_b^\dagger \). If the collective isometry has internal operator cut ranks at most \(D\) and the flag is at an endpoint, the completion has ranks at most \((D+1)^2\). This bounds one completion; it does not bound repeated completion by a constant independent of recursion depth.
For every \(m\geq 1\) there is a contraction \(E\) which is an operator Schmidt factor of an open-boundary bond-two MPU with an exact \(2m\)-gate circuit, such that the positive defect \(\sqrt{I-E^\dagger E}\) has operator cut rank \(2^m\). The same contraction admits a signed unitary completion of bond two.
Put \(q=2^m\), \(h=\pi /(2q)\) and \(\Theta |i,j\rangle =h(i-j)|i,j\rangle \) on two \(m\)-qubit blocks. Take \(E=\cos \Theta \), \(F=\sin \Theta \), and \(U=E\otimes I+iF\otimes X\) with its target at an endpoint. Controlled target rotations give the exact circuit. The positive defect has coefficient matrix \(K_{ij}=\sin (h|i-j|)\). If \(Kv=0\), its interior second differences give \(2\sin (h)v_a=0\); the first and last rows then kill the endpoint coordinates. Thus \(K\) is invertible. Both \(E\) and \(F\) have rank two at this cut, and \(\left(\begin{smallmatrix} E & -F \\ F & E \end{smallmatrix}\right)\) supplies the signed completion.
Let \(N\geq 1\) and let \(U\) be an \(N\)-qubit unitary of consecutive operator cut ranks at most \(D\). For \(0{\lt}\varepsilon {\lt}1\), there are a nonuniform circuit unitary \(W\) and a clean auxiliary embedding \(J\psi =\psi \otimes |0\cdots 0\rangle \) with \(\| WJ-JU\| \leq \varepsilon \). For fixed \(D\), both gate and auxiliary-qubit counts are at most
This bounds the auxiliary output error, without asserting exact auxiliary erasure or a bound on arbitrary auxiliary inputs.
At each balanced cut, an Auerbach basis of the left Schmidt space and its norm-one coordinate functionals write a contraction as \(A=\sum _{i=1}^r A_i\otimes B_i\), with \(r\leq D\) and all factors contractions of inherited internal cut ranks. Recursively implement compressed blocks \(A_i/s,B_i/s\) for a fixed numerical \(s\). Their linear combination has ideal block \(A/(rs^2)\). An odd sine Fourier series of coefficient absolute sum at most one implements linear amplification on the required singular-value interval through Grover powers. A compact convolution kernel gives truncation degree \(O_D((1+\log (1/\eta ))^2)\). The Chebyshev perturbation estimate \(\| T_n(X)-T_n(Y)\| \leq n^2\| X-Y\| \), applied to Hermitian dilations, controls child errors. The combined gate and auxiliary cost obeys \(F_{\rm parent}\leq C_D M^c\sum F_{\rm child}\). Along \(\lceil \log _2N\rceil \) levels the required logarithmic precision grows at most polynomially in the initial precision and the number of levels, giving the displayed bound. Final constant-cost amplification of the unitary block yields a block \(B\) with \(\| B-U\| =O(\varepsilon ^2)\); unitarity then gives \(\| WJ-JU\| \leq \sqrt{2\| B-U\| }\). The complete Fourier and circuit estimates are in [ 252 ] , Section 7.
18.15 Uniform families without exact-length full rank
Fix a physical dimension \(d\geq 2\), a finite-dimensional bond space, matrices \(A^{ij}\) and boundary vectors \(l,r\). Suppose
is unitary for every \(N\geq 1\). Then \(U_N\) has an exact circuit of polynomial size and depth, with \(O(N)\) auxiliary qudits which begin and end in zero. The gates may be restricted to adjacent sites on a line. The constants and polynomial exponent depend on the fixed presentation; no exact-length full-rank assumption is required.
Let \(E_+\) be the span of all positive-word columns \(A_wr\) and quotient by the vectors annihilated by all positive-word rows \(lA_u\). This preserves the operators at lengths at least two, using endpoint tensors \(lA^{ij}\) and \(A^{ij}r\) on the quotient. Write \(w\) for its dimension. Cumulative cap lengths \(1,\ldots ,w\) span the quotient and its dual: a plateau in either cumulative span is invariant and therefore terminal.
Choose Hilbert coordinates on this quotient. For each cap length let \(P_m\) and \(Q_n\) be its left and right Gram matrices, with cap inputs averaged and cap outputs summed. Unitarity at length \(m+k+n\) gives, for a central interval tensor \(T\) of length \(k\),
This identity is separately linear in the two Gram matrices. Thus \(P=w^{-1}\sum _{m=1}^wP_m\) and \(Q=w^{-1}\sum _{n=1}^wQ_n\) satisfy every interval identity and are positive definite. One-sided cap traces give the endpoint identities. The Grams are averaged before taking square roots.
Put \(L=P^{1/2}\) and \(R=Q^{1/2}\). The amplitudes \(LTR\) define fixed interval isometries with two outer flags. Their flags merge by the contraction \(R^{-1}L^{-1}\), whose finite norm is a constant of the family. A fixed unitary dilation and exact subspace amplification give a bounded number of child invocations per merge. On a balanced tree the cost satisfies \(H(n)\leq c(H(\lceil n/2\rceil )+H(\lfloor n/2\rfloor ))+cn\), and is polynomial. The tree has \(O(N)\) logical flags, and the image reflections reuse one \(O(N)\) reversible scratch pool. All inner flags and scratch are erased exactly; the root has no outer flags. Adjacent swaps add at most a linear cost factor. The complete quotient, normalization, amplification and auxiliary count are proved in [ 249 ] , Section 4.
This removes Assumption 1 from the uniform-bulk circuit theorem of [ 240 ] . The averaging argument uses the same fixed presentation at every positive length. The following affine construction removes that restriction. Fixed trace boundaries \(\operatorname {Tr}(bA_{\rm word})\) are included: use the enlarged bond space of matrices, with each letter acting by left multiplication, right vector \(b\) and left functional the trace.
18.16 Polynomial exact circuits at arbitrary fixed cut rank
The real affine hull of a set of Hermitian matrices consists of Hermitian matrices. If \(\operatorname {Tr}(XQ)=z\) on the original set, with \(Q\) fixed, the same identity holds on its real affine hull.
Both properties are preserved by \(X,Y,Z\mapsto c(X-Y)+Z\) for every real \(c\).
Let \(\mathcal C\) be a real affine space of complex square matrices, and let \(Q{\gt}0\) satisfy \(\operatorname {Tr}(XQ)=1\) for all \(X\in \mathcal C\). Then \(\mathcal C\cap \{ X\succeq 0\} \) is compact. If this slice contains a positive definite matrix, its determinant has a positive definite maximizer. More generally, this last assertion holds for any compact set of positive semidefinite matrices containing a positive definite matrix.
The entire set \(\{ X\succeq 0:\operatorname {Tr}(XQ)=1\} \) is the continuous image of the compact set of density matrices under \(Y\mapsto Q^{-1/2}YQ^{-1/2}\). Intersect it with the closed affine space \(\mathcal C\). The determinant is continuous and real on positive semidefinite matrices. Its maximum is strictly positive by comparison with the assumed positive definite matrix, and a positive semidefinite matrix with nonzero determinant is positive definite.
For a positive definite \(r\times r\) matrix \(P\), with \(r\geq 1\), put \(Q=P^{-1}/r\).
For a nonsingular complex square matrix \(P\) and any matrix \(H\),
If \(P{\gt}0\) maximizes the determinant on the positive semidefinite part of a real affine space \(\mathcal C\) of Hermitian matrices, then \(\operatorname {Tr}(P^{-1}(X-P))=0\) for every \(X\in \mathcal C\).
Differentiate the determinant polynomial of \(I+zP^{-1}H\) and multiply by \(\det P\). The positive definite matrices form the interior of the positive semidefinite cone within the Hermitian matrices, so both signs of each Hermitian affine direction are feasible near \(P\). Fermat’s theorem gives a zero real derivative. The trace of a product of Hermitian matrices is real by cyclicity of the trace and conjugate transposition. Cancel the nonzero real determinant to obtain the complex trace identity.
The dual metric is positive definite and satisfies
If \(\operatorname {Tr}(P^{-1}(X-P))=0\), then \(\operatorname {Tr}(XQ)=1\).
Use \(PP^{-1}=P^{-1}P=I\) and \(\operatorname {Tr}I=r\).
Let \(\mathcal C\) be a real affine subspace of Hermitian \(r\times r\) matrices, with \(r\geq 1\). Suppose it contains a positive definite matrix, and there is a positive definite \(\overline Q\) with \(\operatorname {Tr}(P\overline Q)=1\) for all \(P\in \mathcal C\). Then there are \(P_*,Q_*{\gt}0\) such that
The compactness lemma supplies a positive definite determinant maximizer \(P_*\). Both signs of every affine tangent direction \(H\) are feasible near \(P_*\), so \(\operatorname {Tr}(P_*^{-1}H)=0\) by the derivative of the determinant. Apply this to \(H=P-P_*\) and use \(\operatorname {Tr}(P_*^{-1}P_*)=r\). The final trace identity follows from the algebra of the dual metric.
For positive \(P\) and its dual \(Q=P^{-1}/r\), the joining contraction is \(C=(\sqrt Q)^{-1}(\sqrt P)^{-1}\).
For \(P{\gt}0\) and \(Q=P^{-1}/r\), put \(C=(\sqrt Q)^{-1}(\sqrt P)^{-1}\). Then \(C=\sqrt r\, I\), \(C^\dagger C=rI\), and \(\langle \operatorname {vec}C,\operatorname {vec}C\rangle =r^2\). Thus the corresponding contraction bra has norm \(r\).
The positive square root commutes with inversion and with multiplication by nonnegative real scalars. Therefore \((\sqrt Q)^{-1}=\sqrt{rP}=\sqrt r\sqrt P\). Cancel \(\sqrt P\) and take the trace of \(C^\dagger C\).
Let \(P,Q\) be positive definite metrics on a bond of dimension \(r\geq 1\), with \(\operatorname {Tr}(PQ)=1\). Then
For fixed \(P\), the dual metric \(Q_*=P^{-1}/r\) is positive, satisfies the normalization and attains equality. Hence the joining contraction norm \(r\) is optimal among these normalized positive metrics. This assertion concerns this joining method; it gives no lower bound on arbitrary circuit complexity.
Set \(X=\sqrt Q\sqrt P\) and \(Y=\sqrt{Q^{-1}}\sqrt{P^{-1}}\). Then \(X^\dagger Y=I\), \(\operatorname {Tr}(X^\dagger X)=1\) and \(\operatorname {Tr}(Y^\dagger Y)=\operatorname {Tr}(Q^{-1}P^{-1})\). Hilbert–Schmidt Cauchy–Schwarz gives the inequality. The dual-metric identity gives equality for \(Q_*\).
For interval matrices \(A_{ab}:\mathbb C^s\to \mathbb C^r\), put
The first map is linear in \(P\). For prefix rows \(F_{ab}\), their density-weighted Gram is \(P_F(\rho )=\mathcal T_\rho (I)\), where the left virtual space is one dimensional.
For consecutive intervals \(A,B\), the transfer of their concatenation with input \(\rho \otimes \sigma \) is \(\mathcal T^B_\sigma (\mathcal T^A_\rho (P))\). In particular, \(P_{FA}(\rho \otimes \sigma )=\mathcal T^A_\sigma (P_F(\rho ))\).
Expand the finite sums, use \((AB)^\dagger =B^\dagger A^\dagger \), and permute the independent physical indices.
One has \(\operatorname {Tr}(Q\mathcal T_\rho (P)) =\operatorname {Tr}(\rho K(P,Q))\) for every \(\rho \). If this value is one for every density matrix \(\rho \), then \(K(P,Q)=I\). More generally, any complex matrix \(K\) satisfying \(\operatorname {Tr}(\rho K)=1\) for every density matrix is the identity; no Hermitian hypothesis on \(K\) is required.
Trace cyclicity and permutation of the finite sums give the pairing identity. For every nonzero vector \(v\), test against \(|v\rangle \langle v|/\langle v,v\rangle \) to obtain \(\langle v,(K-I)v\rangle =0\). Complex polarization gives \(K=I\), including all off-diagonal entries.
Let \(\mathcal S_F=\{ P_F(\rho ):\rho \succeq 0, \operatorname {Tr}\rho =1\} \), and let \(\mathcal C_F\) be its real affine hull. The interval transfer is also an affine map over the real scalars.
Each physical prefix Gram is positive semidefinite, and every matrix in \(\mathcal C_F\) is Hermitian. In the convention \((F_a)_{bv}=F_{ab}(v)\), one has \(P_F(\rho )=\sum _aF_a^\dagger \rho ^T F_a\).
Expand the matrix entries to obtain the sandwich formula. The transpose of a positive semidefinite matrix is positive semidefinite. Each sandwich and their sum are therefore positive semidefinite. Apply the real affine Hermitian closure lemma.
For every interval density matrix \(\sigma \), \(\mathcal T^A_\sigma (\mathcal S_F)\subseteq \mathcal S_{FA}\) and \(\mathcal T^A_\sigma (\mathcal C_F)\subseteq \mathcal C_{FA}\). The density factors may each be entangled throughout their respective intervals.
The concatenation identity sends \(P_F(\rho )\) to \(P_{FA}(\rho \otimes \sigma )\). Positivity and unit trace are preserved by the tensor product. An affine map sends the affine hull of a set into the affine hull of its image.
For square bond weights \(L,R\), define an interval map whose amplitudes, including the two virtual output indices \(u,v\), are \((LA_{ab}R)_{uv}\).
The vectorized map \(V\) has Gram \(V^\dagger V=K(L^\dagger L,RR^\dagger )\). Hence \(V\) is an isometry if \(\operatorname {Tr}(RR^\dagger \mathcal T_\rho (L^\dagger L))=1\) for every input density matrix \(\rho \).
The inner product of two vectorized matrices is their Hilbert–Schmidt trace pairing. Sum this identity over the physical output index, and apply density separation.
Suppose \(P\in \mathcal C_F\) and \(P,Q\succeq 0\), with \(\operatorname {Tr}(XQ)=1\) for every \(X\in \mathcal C_{FA}\). The interval map with amplitudes \(\sqrt P A_{ab}\sqrt Q\) is an isometry.
For every density matrix \(\rho \), transfer membership gives \(\mathcal T_\rho (P)\in \mathcal C_{FA}\), so its trace pairing with \(Q\) is one. Apply the full density-test isometry identity and the positive square-root identities.
Suppose the two affine spaces \(\mathcal C_F\) and \(\mathcal C_{FA}\) each contain a positive definite matrix and each admit a positive definite trace normalizer. Their bond dimensions are \(r,s\geq 1\). There exist positive definite \(P\in \mathcal C_F\) and \(S\in \mathcal C_{FA}\) whose dual metrics normalize their respective affine spaces and satisfy the inverse-metric trace identities \(r^2,s^2\). The interval map with amplitudes \(\sqrt P A_{ab}\sqrt{S^{-1}/s}\) is an isometry.
Apply determinant balancing to both Hermitian affine spaces, then use the earlier chosen metric and the later dual metric in the affine interval-isometry theorem.
Let \(F_a:\mathbb C^r\to \mathbb C^B\) and \(G_c:\mathbb C^E\to \mathbb C^r\). Define \(U_{(a,c),(b,e)}=(F_aG_c)_{be}\) and
For arbitrary matrices \(\rho ,\tau \), one has
Both cap Grams are positive semidefinite for positive semidefinite inputs. If \(U^\dagger U=I\), their pairing equals \(\operatorname {Tr}\rho \operatorname {Tr}\tau \). In particular, the maximally mixed suffix input normalizes every trace-one prefix input. The rectangular prefix formula agrees with the one-row prefix Gram above.
Write \(U^\dagger U\) as the sum of the rank-one Grams of its rows. The vectorization trace identity turns each product-density pairing into \(\operatorname {Tr}((F_aG_c)^\dagger \rho ^T F_aG_c\tau )\). Trace cyclicity and the finite sums give the displayed identity. Positivity follows from the matrix sandwiches. Substitute \(U^\dagger U=I\) and take the trace of a tensor product to obtain the normalized formula.
Suppose the physical input spaces are nonzero. If the prefix rows span \(\mathbb C^r\), their maximally mixed Gram is positive definite, providing a positive definite point in both \(\mathcal S_F\) and \(\mathcal C_F\). If the suffix columns span \(\mathbb C^r\), their maximally mixed Gram is positive definite. Under global isometry, it provides a positive definite trace normalizer for every trace-one prefix input.
The unnormalized suffix Gram is the frame operator of its columns; the prefix Gram is the transpose of the frame operator of its rows. A finite frame operator is positive definite precisely when its vectors span. Scale by the reciprocal input dimension and apply the global normalization identity.
For a prefix \(F\), middle interval \(A\), and suffix \(G\), define the longer prefix \(FA\) and longer suffix \(AG\) by ordinary contraction of their shared virtual indices. The resulting physical operator has coefficients \(F_{ab}A_{cd}G_{ef}\).
The operators obtained by contracting \((FA)G\) and \(F(AG)\) differ only by reassociation of their physical index triples. Global isometry is preserved by this reassociation.
Expand the two finite virtual sums and apply associativity of scalar multiplication. Reindex the physical coordinates by the natural product associativity bijections.
Suppose \(U=FG\) is globally isometric, its suffix input space is nonzero, and the suffix columns span the bond space. Then a positive definite matrix \(Q\) satisfies \(\operatorname {Tr}(XQ)=1\) for every \(X\in \mathcal C_F\).
Take the maximally mixed suffix Gram and extend its physical trace normalization to the real affine hull.
Let \(U=FAG\) be globally isometric, with nonzero physical input spaces and bond dimensions \(r,s\geq 1\). Suppose the rows of \(F\) and \(FA\), and the columns of \(AG\) and \(G\), span their respective bond spaces. There are balanced positive metrics \(P\in \mathcal C_F\) and \(S\in \mathcal C_{FA}\), with their dual metrics normalizing the entire affine spaces and their inverse-metric traces equal to \(r^2,s^2\). The middle interval with amplitudes \(\sqrt P A_{cd}\sqrt{S^{-1}/s}\) is an isometry.
Apply global normalization and the spanning criterion at both cuts. These supply positive definite normalizers and positive definite points in both affine spaces. Apply the two-cut determinant-balancing theorem.
For \(U=FG\), its cut coefficient matrix groups output and input indices on each side: \(W_{(a,b),(e,f)}=(F_aG_e)_{bf}\). For a three-part factorization \(FAG\), the first and second cut matrices are those of \(F(AG)\) and \((FA)G\), respectively.
If \(X\) has \(r\) columns, \(Y\) has \(r\) rows and \(\operatorname {rank}(XY)=r\), then the rows of \(X\) and columns of \(Y\) span \(\mathbb C^r\). The physical cut coefficient matrix factors through the virtual bond in precisely this way. Consequently, cut ranks equal to the two virtual dimensions imply all four spanning conditions for \(F,AG,FA,G\). The two cut matrices contain the same physical coefficients, grouped at their respective cuts.
Rank of a product is bounded by the rank of each factor, and each factor has rank at most \(r\). Both ranks therefore equal \(r\), giving the two spans. Apply this at both cuts. Matrix multiplication gives the coefficient factorization, and associativity gives the equality of regrouped coefficients.
Let \(FAG\) be globally isometric, with nonzero physical input spaces and virtual dimensions \(r,s\geq 1\). If its two bounding physical cut matrices have ranks \(r,s\), then the balanced positive metrics, affine normalization identities, contraction traces \(r^2,s^2\) and middle-interval isometry of Theorem 18.16.26 exist.
Derive the four spanning conditions from the two rank equalities, and apply the global-isometry result.
Consider an indexed family of globally isometric two-part factorizations \(F_jG_j\) with spanning prefix rows and suffix columns. The physical spaces and positive bond dimensions \(r_j\) may depend on \(j\). There is one chosen metric \(P_j\) at each index such that
The same conclusion holds when each physical coefficient flattening has rank exactly \(r_j\), since this implies both spanning conditions. All these identities hold for the same chosen family. In particular, the metrics may be chosen at every cut of a finite minimal chain before its interval isometries are assembled.
Global isometry and minimality give a positive normalizer and a positive point at each cut. Apply affine determinant balancing separately, and choose one of its metric witnesses at each index.
A prefix with scalar virtual bonds has physical matrix \(U_{ab}=F_{ab}(1,1)\). The empty prefix has one input, one output, and scalar coefficient one.
If the physical matrix of a scalar-bond prefix is an isometry, then \(P_F(\rho )=\operatorname {Tr}(\rho )I\) for every complex input matrix \(\rho \). For a nonzero input space, both its physical Gram set and real affine hull equal \(\{ I\} \). This also holds for the empty prefix. The one-dimensional identity is its own dual metric.
Closing the scalar bonds gives \(K(I,I)=U^\dagger U\). Trace pairing therefore gives the scalar Gram identity for every \(\rho \). A faithful density matrix witnesses the identity in the physical Gram set. Take its affine hull, and use the dimension-one dual-metric formula.
For a positive metric \(P\) on an \(r\)-dimensional bond, put \(S=\sqrt P\), \(T=\sqrt{P^{-1}/r}\) and \(C=r^{-1}T^{-1}S^{-1}\). Given weighted coefficients \(X_{ab}\) and \(Y_{cd}\) on adjacent intervals, their contracted coefficient is \(X_{ab}CY_{cd}\), vectorized over the two remaining virtual bonds.
The joining contraction \(C\) has squared Hilbert–Schmidt norm one. For arbitrary outside weights \(L,R\) and adjacent coefficients \(A_{ab},B_{cd}\),
Thus contraction gives \(r^{-1}\) times the parent interval map. If that parent map is an isometry, the contracted map has input Gram \(r^{-2}I\). The success probability is therefore the same for every input, including entangled inputs.
The unnormalized contraction has squared Hilbert–Schmidt norm \(r^2\). Divide by \(r\), cancel the two invertible square roots, and take the input Gram of the resulting scalar multiple.
For a projection \(P\), put \(R_P=I-2P\). For two maps \(G,H\) with common input and output spaces, put
An orthogonal projection gives a unitary reflection. If \(G^\dagger G=H^\dagger H=I\) and \(G^\dagger H=0\), then \(V_\theta \) is an isometry for every real \(\theta \) and \(V_\theta V_\theta ^\dagger \) is an orthogonal projection. If \(P\) is also an orthogonal projection, \(Q_\theta \) is unitary on the entire output space.
Square \(I-2P\), use the orthogonal Gram identities, and use \(V_\theta ^\dagger V_\theta =I\) to square its image projection. A product of the two reflections, with scalar phase minus one, is unitary.
Suppose \(G^\dagger G=H^\dagger H=I\), \(G^\dagger H=0\), \(PG=G\) and \(PH=0\). For all real \(\theta ,\phi \) and \(k\geq 0\),
In particular, for \(\ell \geq 0\) and \(\theta =\pi /(4\ell +2)\), \(Q_\theta ^\ell V_\theta =G\) exactly, with no residual phase.
Expand the two reflections on the orthogonal images of \(G,H\). The trigonometric addition identities give the one-step rotation. Iterate it by induction. The final angle is \((2\ell +1)\pi /(4\ell +2)=\pi /2\).
For a real coefficient \(t\), put \(s=\sqrt{1-t^2}\) and define
The two row blocks represent the two values of a new binary flag.
If \(t^2\leq 1\), then \(R_t\) is unitary on both flag values. If \(t^2\leq 1\) and \(V^\dagger V=I\), also \(V_t^\dagger V_t=I\). An orthogonal projection \(P\) gives an orthogonal projection \(P_t\). Moreover, for any uniform probability identity \(V^\dagger PV=p^2I\),
Thus a nonnegative attenuation coefficient multiplies the original nonnegative success amplitude by \(t\).
The two flag coefficients satisfy \(t^2+s^2=1\). Multiply the two-by-two rotation and the block matrices, using this identity for normalization and the first row block for the success Gram.
Given an isometry \(V\), success projection \(P\) and real success amplitude \(0{\lt}p{\lt}1\), put
Suppose \(V^\dagger V=I\), \(P\) is an orthogonal projection, \(0{\lt}p{\lt}1\) and \(V^\dagger PV=p^2I\). The maps \(G,H\) above satisfy
Thus both isometric subspaces follow from the uniform probability identity.
Projection identities give the two projected Grams \(p^2I\) and \((1-p^2)I\), and their mixed Gram is zero. Divide by their positive amplitudes. Adding the projected parts recovers \(V\).
Suppose \(V^\dagger V=I\) and \(P\) is an orthogonal projection. The operator \(Q\) is unitary on the entire output space. If \(V^\dagger PV=\sin ^2\theta \, I\) with \(0{\lt}\theta {\lt}\pi /2\), then the derived success and failure maps give
For \(\theta =\pi /(4\ell +2)\) and \(\ell \geq 1\), \(Q^\ell V=(\sin \theta )^{-1}PV\) exactly. If instead \(V^\dagger PV=I\), then already \(PV=V\).
Derive the orthogonal isometric decomposition. In the first quadrant, \(\sqrt{1-\sin ^2\theta }=\cos \theta \), so it is the initial amplification plane. Apply the rotation identities. At probability one the complementary projected Gram is zero, forcing the complementary map to vanish.
For \(r\geq 0\), define
For \(r\geq 1\),
Thus the merger success amplitude \(1/r\) can be attenuated to the prescribed exact angle, with at most \(r\) amplification rounds.
Positivity and the ceiling inequalities give the lower bound on \(\ell (r)\). Since \(\pi \leq 4\), its ceiling is at most \(r\). Also \(4\ell (r)+2\geq \pi r+2\), which bounds the angle by \(1/r\). The angle is in \((0,\pi /2)\), and \(\sin \theta \leq \theta \).
For a coefficient tensor \(\psi \) on a finite chain, let \(C_k\) be its coefficient matrix with rows indexed by configurations before cut \(k\) and columns indexed by the remaining configurations. Put \(E_k=\operatorname {span}\{ \text{columns of }C_k\} \) and \(r_k=\operatorname {rank}C_k\). Fixing the letter at site \(k\) defines a coordinate slice from functions on the longer prefix to functions on the shorter prefix. The last-cut vector is \(\psi \) regarded as a function on the full prefix.
Adjoining a letter on the prefix or suffix side gives the same coefficient, and joining the two restrictions of a configuration recovers \(\psi \). Each coordinate slice maps \(E_{k+1}\) into \(E_k\), and \(\dim E_k=r_k\). If \(\psi \ne 0\), every \(r_k\) is positive; at the two endpoint cuts it is one. The initial cut space is the full one-dimensional space, and the last-cut vector is a nonzero member of the last cut space.
The adjacent-cut identity follows by separating sites before, at, and after the new letter. Slices take coefficient columns to coefficient columns, and hence preserve their spans. A nonzero coefficient gives a nonzero entry at every cut. Each endpoint matrix has one row or one column.
Let \(0\leq k\leq N\). Number the sites before cut \(k\) by \(0,\ldots ,k-1\), and number the sites after the cut by \(0,\ldots ,N-k-1\). The corresponding bijections to the actual sites are \(i\mapsto i\) and \(j\mapsto k+j\). They induce bijections between the numbered configurations and the configurations on the two subsets of physical sites.
For every coefficient tensor \(\psi \) and every \(k\leq N\), the coefficient matrix indexed by the actual prefix and suffix configurations is the matrix indexed by numbered configurations after the preceding row and column bijections. Thus the two matrices have the same rank. No assumption on the local dimension or on the nonvanishing of \(\psi \) is required.
The site bijections reconstruct the same physical configuration, so corresponding entries agree. Reindexing rows and columns by bijections preserves matrix rank.
Choose a basis of each \(E_k\) indexed by \(r_k\) coordinates. The site matrix for a physical letter is the matrix of its slice \(E_{k+1}\to E_k\). Evaluation at a prefix configuration is a linear functional on \(E_k\). Padding the site matrices gives their products in a common matrix space, while their rectangular forms give an open-boundary chain of bond dimensions \(r_k\).
For a nonzero tensor of positive length, the endpoint bases can be chosen as \(1\) and \(\psi \). Successive slice matrices reconstruct prefix evaluation. Their full product between the zero endpoint coordinates is then exactly \(\psi \) at the given configuration, provided each intermediate rank fits the padding dimension. Thus the resulting rectangular open-boundary chain has exactly the original coefficients, including their normalization and phase.
Fix the two one-dimensional endpoint bases and choose bases at the other cuts. Composition of the evaluation maps gives the product formula. At the initial cut evaluation is the row selecting the zero coordinate; at the last cut its selected column evaluates \(\psi \).
Every nonzero coefficient tensor on \(N\geq 1\) sites whose consecutive physical cut ranks satisfy \(r_k\leq D\) has an exact open-boundary matrix-product representation with bond dimension \(r_k\) at each cut.
Use the chain of coordinate slices with the endpoint bases fixed above. Its bond dimensions are the physical cut ranks by construction, and reconstruction gives every coefficient.
Let \(F_k\) evaluate the chosen cut basis on each prefix configuration, and let \(G_k\) contain the coordinates of each coefficient column in that basis.
At every cut, \(C_k=F_kG_k\) and \(\operatorname {rank}F_k=\operatorname {rank}G_k=r_k\). The prefix rows and suffix columns both span the bond space. Fixing the next letter gives the corresponding multiplication by its site matrix. The normalized endpoint factors are one. All these factors and spanning properties can be chosen together with the exact minimal open-boundary representation.
Basis reconstruction gives the factorization. The basis evaluation map is injective, while coefficient columns span the cut space; both ranks are therefore \(r_k\). Composition with a coordinate slice gives the site identities and the endpoint normalizations.
For \(a\) data qudits, use \(a\) temporary qudits initialized in zero. At step \(j\), increment temporary coordinate \(j\) modulo \(d\) when data coordinate \(j\) is zero and either \(j=0\) or the preceding temporary coordinate is one. This is a reversible permutation on the full register. Put \(c_d=38(d^3)^6+1\); a step has gate budget \(4ac_d\) after routing.
For \(d\geq 2\) and every logical configuration \(x\), the conjunction keeps \(x\) and writes in temporary coordinate \(j\) whether its first \(j+1\) data coordinates are all zero. Each step acts on at most three sites. The full conjunction has an actual neighboring-pair circuit of at most \(4c_da^2\) gates.
Induct on the completed prefix. At the next step its temporary coordinate is still zero, and the previous Boolean value supplies the earlier prefix test. The controlled increment is independent of its target and supported on at most three sites. Synthesize that finite permutation and concatenate the routed steps.
For \(a\geq 1\), compute the prefix conjunction, change the phase by minus one when the final temporary coordinate is one, and undo the conjunction. Its gate budget is \(K(d,a)=8c_da^2+4a\).
Let the local dimension satisfy \(d\geq 2\). The constructed circuit is unitary on the full register and, for every logical input, returns the temporary register to zero while applying \(I-2|0\rangle \langle 0|\) to the tested register. This is an exact equality of linear maps and costs at most \(K(d,a)\) neighboring-pair gates. Injective placement on an \(n\)-site chain costs at most \(2nK(d,a)\); all other logical sites are unrestricted. For an empty tested register the reflection is the global phase \(-I\), implemented by one neighboring-pair gate when \(n\geq 2\).
On a clean temporary register the final Boolean value tests exactly whether the entire data register is zero. The diagonal phase changes no coordinate, so the inverse permutation erases every temporary value. Linear extension gives the complete initialized-subspace identity. The costs add the forward and inverse conjunctions and the one-site phase; arbitrary placement uses swap routing.
Extending rectangular bond matrices and vectors by zero preserves their products whenever the intermediate bond dimension is no larger than the common padding dimension. The outer dimensions need not satisfy this bound.
In the product sum, terms outside the intermediate bond space vanish. The remaining terms are exactly the rectangular product.
For a square matrix \(A\), define
If \(AA^\dagger A=A\), then \(\mathcal D_A\) is unitary. For every matrix of input columns \(V\),
The total output Gram is \(V^\dagger V\), and projection onto the first output copy has Gram \((AV)^\dagger AV\). The first-copy identity holds for arbitrary \(A\).
Both \(A^\dagger A\) and \(AA^\dagger \) are projections. Block multiplication gives \(\mathcal D_A^\dagger \mathcal D_A=I\), the displayed action, and its projected Gram.
If \(\sum _x\overline{w_x}w_x=1\), the matrix \(A=|z\rangle \sum _xw_x\langle x|\) satisfies \(AA^\dagger A=A\).
Multiply the two outer products and use the unit norm of the row.
Let \(w\) be the vectorization of the normalized balanced joining contraction. The bond reset sends this row functional to a specified pair of bond basis states. Its one-flag dilation is the two-copy dilation of that reset matrix.
A positive definite balanced metric gives a unitary bond dilation. On a clean flag input, its first output branch applies exactly the normalized contraction and resets the bond pair to the specified basis state. Its second branch records the complementary initial component.
The normalized contraction has vectorized norm one, so the bond reset is a partial isometry. Apply its explicit dilation and the first-copy action formula.
Set
Every unitary on \(n\geq 2\) qudits of dimension \(d\geq 2\) has an exact neighboring-pair circuit of at most \(G(d,n)\leq 38(d^n)^6\) gates, including its global phase. An isometry together with an injective placement of its input basis extends to such a circuit with the prescribed columns. Call a two-level gate special if its two-by-two block is a real rotation \(\begin{pmatrix} c & -s \\ s & c \end{pmatrix}\) with \(c^2+s^2=1\) or a phase \(\operatorname {diag}(\nu ,\overline\nu )\) with \(|\nu |=1\). A special two-level gate with \(k\) controls has cost at most \(4n3^k\); a special two-level gate between arbitrary configurations has cost at most \((2n+1)(4n3^n)\).
Eliminate matrix entries by two-level unitaries, express each by controlled one-site gates, and route its two-site factors. A separate one-site phase preserves exact matrix equality. Extension of orthonormal columns gives the isometry assertion.
On a chain of \(n\) sites with positive local dimension, injectively placing a neighboring-pair circuit of \(K\) gates requires at most \(2nK\) neighboring-pair gates.
Each placed gate acts on two distinct sites. Swaps bring them together and restore their positions at cost at most \(2n\).
Set \(t_r=r\sin \theta (r)\).
Let \(V^\dagger V=I\), let \(P\) be an orthogonal projection, and suppose \(V^\dagger PV=r^{-2}I\), with \(r\geq 1\). Attenuation by \(0{\lt}t_r\leq 1\) and \(\ell (r)\leq r\) reflection rounds give exactly
The equality includes the phase and holds on all coherent inputs.
The attenuated amplitude is \(t_r/r=\sin \theta (r)\). Exact amplification gives its normalized successful part. The two scalar normalizations cancel to leave \(rPV\).
If a unitary \(U\) has a \(K\)-gate circuit and reflection about \(EE^\dagger \) has an \(L\)-gate circuit, then reflection about \((UE)(UE)^\dagger \) has a \((2K+L)\)-gate circuit, since
A \(K\)-gate circuit repeated \(k\) times costs at most \(kK\). On \(n\geq 2\) sites of positive local dimension \(d\), an amplification round with reflection costs \(K,L\) costs at most \(2n+K+L\), including its phase.
Unitary conjugation gives the identity. Concatenate the forward circuit, the reflection, and the inverse circuit. Repetition concatenates copies; the prescribed global phase costs at most \(2n\).
Suppose \(C,q\geq 0\), \(r\geq q+1\), \(T(0)\leq a\), and \(T(j+1)\leq rT(j)+Cq^j\). Then
If also \(a\geq 0\) and \(r\leq 2^k\), this is at most \((a+C)(2^L)^k\). In particular, polynomial overhead in the interval length is compatible with polynomial total cost at a fixed child-call factor. For integer \(r\), one may take \(k=\lceil \log _2 r\rceil \).
Induction uses \((r-q-1)Cq^j\geq 0\) at each step. The binary upper bound on \(r\) gives the polynomial estimate.
Pair each output letter with its input letter, giving a coefficient tensor of local dimension \(d^2\). Splitting physical configurations at a cut and separating their output-input pairs are bijections. The resulting coefficient cut rank is the consecutive operator Schmidt rank.
Pairing and splitting commute, and the paired tensor recovers every original operator entry. A finite unitary on a positive physical alphabet has a nonzero coefficient tensor. If its consecutive operator Schmidt ranks are at most \(D\) and its length is positive, it therefore has an exact open-boundary representation with those ranks as its bond dimensions.
The configuration bijections act site by site. A zero paired tensor would make the entire unitary matrix zero, contradicting its unit Gram. Apply the minimal representation theorem.
Separate the output and input configurations in the prefix and suffix matrices of the paired coefficient tensor. The resulting factors are operator-valued prefix rows and suffix columns.
Every finite unitary on a positive-length chain with \(d{\gt}0\) admits endpoint-compatible minimal cut bases and a simultaneous family of balanced positive metrics. At cut \(j\), the metric \(P_j\) belongs to the actual prefix Gram affine hull, \(P_j\) and \(Q_j=P_j^{-1}/r_j\) are positive definite,
No factorization, spanning, isometry, or metric witnesses need to be supplied.
The constructed factors give the original unitary with its configurations bijectively relabelled, so their operator is isometric. Both spans follow from the minimal physical cut factorization and the bijection of paired configurations. Choose endpoint-compatible bases and apply simultaneous determinant balancing to these derived factors.
For \(d\geq 2\) and \(r\geq 1\), a bond basis embeds in \(q=\lceil \log _d r\rceil \) qudits with its zero label represented by the all-zero configuration, and \(r\leq d^q\leq dr\). Two encoded bonds of dimensions \(r,s\) and one physical site have padded dimension at most \(d^3rs\). The same bound holds after increasing the packet to at least two sites for pair-gate synthesis.
The ceiling logarithm gives both dimension inequalities. Embed the finite basis by cardinality and interchange its zero image with the all-zero configuration. Multiply the two flag bounds; the two-site exceptional packet also fits the displayed estimate.
For an injection of logical basis vectors into a larger basis, let \(J\) be its inclusion matrix. Appending an all-zero temporary register gives the zero-workspace inclusion as a special case.
The ambient operator \(U\) implements the logical operator \(Z\) with reusable initialized workspace when \(UJ=JZ\). This identity applies to the entire logical space.
Initialized-workspace implementations compose and repeat using the same workspace. If \(J^\dagger J=I\) and \(U\) is unitary, \(UJ=JZ\) forces \(Z\) to be unitary and gives \(U^\dagger J=JZ^\dagger \). Thus inverse calls also return the workspace to its initialized state on every logical input. The identities persist after tensoring with an arbitrary finite reference identity.
Multiply the two intertwining identities. Taking the Gram of \(UJ=JZ\) gives \(Z^\dagger Z=I\); ambient and logical unitarity then give the inverse identity. Tensor multiplication preserves the intertwining identity with a reference system.
A basis inclusion is an isometry, and multiplication by it selects the corresponding columns. For an isometry \(V\), injective input and output encodings in a register of \(n\geq 2\) qudits of dimension \(d\geq 2\) give an exact circuit \(U\) with \(UJ_{\rm in}=J_{\rm out}V\) and at most \(38(d^n)^6\) gates. When \(V\) is a logical unitary and the two inclusions coincide, this is an initialized-workspace implementation. The constructed zero-register reflection also satisfies this complete logical-space identity.
Encoded columns remain orthonormal. Extend them to a unitary with their prescribed input columns and synthesize that finite unitary. The zero-register assertion is its already proved exact clean-input matrix identity.
For cuts \(j\leq k\), an interval configuration assigns physical letters to the sites \(j,\ldots ,k-1\). Fixing these letters restricts the column space at cut \(k\) to the column space at cut \(j\). In the chosen cut bases, denote this restriction by \(A_{j,k}\). Separating every physical letter into output and input letters gives the corresponding operator interval.
Let \(U\) be a finite unitary, with \(d{\gt}0\) and \(N{\gt}0\). Its minimal cut bases admit positive definite metrics which normalize every interval \([j,k]\), simultaneously for all \(0\leq j\leq k\leq N\). The interval matrices satisfy \(A_{j,l}=A_{j,k}A_{k,l}\), with physical configurations concatenated. The statement includes inputs entangled among the interval sites; it requires no externally chosen interval isometries.
Prefix and suffix restrictions give the interval factorization in the minimal cut bases. Physical reindexing preserves the affine Gram spaces. Their transfer identity, applied to the single family of balanced cut metrics, makes every weighted interval an isometry. Composition follows by applying successive restrictions to a basis vector.
Write the two child isometries as a tensor product and regroup their outputs into physical coordinates, outer bond coordinates, and the two joining bond coordinates. Apply the normalized bond-reset dilation only to the joining coordinates and its binary flag. The remaining coordinates carry the identity.
Suppose the two weighted child maps and their parent map are isometries, formed with the same positive definite joining metric on a bond of dimension \(r{\gt}0\). The actual bond dilation is unitary. Its successful branch is the parent isometry with both joining bond labels reset to a specified basis vector, scaled by \(1/r\). Its success Gram matrix is \(r^{-2}I\). After the prescribed attenuation and \(\ell _r\) exact amplification rounds, the result is the parent isometry, with the joining bonds and both binary flags reset. The global phase is retained.
The normalized contraction row has norm one. Its partial-isometry dilation is unitary, and its first branch contracts precisely the two joining indices. Tensor-product Gram identities give the constant successful probability. The exact uniform-merging identity then erases both binary flags.
For a joining bond of dimension \(r\), use a qudit packet of \(\max \{ 2,\lceil \log _d(2r^2)\rceil +1\} \) sites to encode the two copies of the joining-pair space in the dilation.
For \(d\geq 2\), \(r{\gt}0\), and a positive definite joining metric, the packet admits an encoding whose prescribed reset vector is physical zero and an exact neighboring-pair circuit implementing the bond dilation on its entire encoded space. Its dimension is at most \(2d^3r^2\), and its gate count is at most \(38(2d^3r^2)^6\).
Choose a cardinality embedding and exchange the prescribed reset vector with zero. Extend the encoded logical unitary to the whole packet, then apply quantitative unitary synthesis.
An injective choice of \(a\) sites in an \(n\)-site logical register defines the diagonal reflection with phase \(-1\) precisely when those sites are all zero. A common pool of \(A\geq a\) initialized scratch sites supplies its reversible conjunction circuit. Denote the zero-register gate bound by \(K_d(a)\).
For \(d\geq 2\) and \(n\geq 2\), the selected-flags reflection has an actual circuit on \(n+A\) sites. It returns all \(A\) scratch sites to zero on every logical input and costs at most \(2(n+A)K_d(a)\) gates when \(a{\gt}0\). For \(a=0\), one neighboring-pair gate implements the required phase \(-1\). Unselected logical sites are unrestricted.
Place the reversible zero conjunction on the selected flags and the first \(a\) scratch sites, apply its phase, and reverse it. Its exact clean-input identity gives the logical reflection, with every unused scratch coordinate unchanged. The empty case is the scalar unitary \(-I\).
Place the real binary attenuation rotation on levels zero and one of a qudit, and let it be the identity on the other levels.
The rotation is unitary whenever \(t^2\leq 1\), and sends zero to \(t\lvert 0\rangle +\sqrt{1-t^2}\lvert 1\rangle \) exactly. At any site of an \(n\geq 2\) qudit chain it costs at most \(2n\) neighboring-pair gates. The prescribed merger attenuation \(t=r\sin (\pi /(4\ell _r+2))\) satisfies the required inequality.
The binary rotation is extended by the identity. Its first column gives the asserted amplitudes. Route its single-site support along the chain. The amplification budget proves feasibility of the prescribed angle.
Put \(q=\lceil \log _d D\rceil \). At each internal physical cut allocate two \(q\)-site bond registers and two amplification flags. The logical register consists of these sites and the physical chain. Append a scratch pool with as many sites as the logical auxiliary register. Consecutive indexing preserves the order physical sites, logical auxiliary sites, then scratch sites.
The logical auxiliary register has \(A=2(N-1)(q+1)\) sites, and the complete register has
For \(D{\gt}0\) one has \(D\leq d^q\leq dD\). Every positive bond dimension \(r\leq D\) admits an injective encoding in its assigned \(q\) qudits, with bond label zero represented by physical zero. For \(N=1\) the layout has one site; pair-gate synthesis may append one initialized padding site.
Count the finite products and disjoint unions defining the site sets. Ceiling-logarithmic capacity gives the dimension inequalities. A cardinality embedding followed by a transposition of two configurations gives the required zero-preserving encoding.
Encode the two joining bond labels using the given child bond encodings, followed by the dilation flag and one attenuation qudit. The logical bond dilation acts as the identity on every level of the attenuation qudit. The order of the two bond labels agrees with the vectorized joining contraction.
Let a positive bond of dimension \(r\) have a zero-preserving encoding in \(q\) qudits, and let its joining metric be positive definite. There is an actual circuit on \(2q+2\) qudits implementing the bond dilation in precisely this product encoding, preserving the entire attenuation qudit. Its reset vector is all zero. For \(q=\lceil \log _dD\rceil \) and \(D{\gt}0\), the packet dimension is at most \(d^4D^2\) and its gate count is at most \(38(d^4D^2)^6\).
The product encoding is injective and maps the specified reset labels and flags to zero. Extend the encoded full logical unitary, including the identity on the attenuation qudit, to the whole packet. Quantitative synthesis and the register-capacity estimate give the stated gate bound.
A one-site interval output consists of a physical letter and two bond labels. Encode the two labels separately in their assigned registers, allowing width zero at an endpoint cut. Its initialized input contains only the physical letter, with both bond registers in zero.
Every isometric one-site interval map admits a full logical unitary extension in these given product encodings, and an actual neighboring-pair circuit using one initialized scratch qudit. The scratch qudit returns to zero on every logical state. When both bond-register widths are at most \(q=\lceil \log _dD\rceil \) and \(D{\gt}0\), the dimension including scratch is at most \(d^4D^2\), and the gate cost is at most \(38(d^4D^2)^6\). The assertion also covers \(q=0\).
Encode the orthonormal output columns and extend them to a full logical unitary with the prescribed initialized input columns. Extend this full unitary along the one-scratch-qudit inclusion and synthesize the resulting unitary. The complete clean identity ensures cleanup of adjoint calls as well.
Let \(J\) be an initialized isometric inclusion. Suppose an actual child circuit of cost \(K\) implements a logical unitary \(Z\) cleanly along \(J\), and actual reflection circuits of costs \(B,L\) implement \(I-2EE^\dagger \) and \(I-2P\) cleanly along the same \(J\). Here \(E\) is an isometry and \(P\) an orthogonal projection. If
the amplified circuit has cost \(\ell (1+2K+B+L)+K\) and acts exactly as normalized postselection on the columns \(JE\). It also implements a full logical unitary cleanly along \(J\), so its adjoint may use the same workspace. The supplied circuits are the induction data for this assembly statement.
Ambient unitarity and the clean identity imply full logical unitarity of \(Z\), hence cleanup of the inverse child call. Each amplification round is the child circuit, the initial reflection, its inverse, the successful reflection, and the scalar phase \(-1\). Products and powers preserve the complete clean identity. The exact subspace-amplification formula gives the normalized successful columns with their phase retained.
Choose injective placements of the local logical sites in the full logical register and of the local scratch sites in the common scratch pool. Their disjoint union places the entire local circuit, preserving the logical and scratch blocks.
Suppose a local circuit satisfies its complete clean identity on every logical input. Its placed circuit satisfies the same identity on the full logical register and restores the entire larger scratch pool to zero. If the local dimension \(d\) is positive and the local circuit has \(K\) gates, its routed circuit on \(n+A\) sites has at most \(2(n+A)K\) gates. No additional cleanup hypothesis is required for the placed circuit.
The initialized basis inclusion selects the zero-scratch columns. In these columns, the placed matrix identity is precisely the local clean identity, with identity factors on every unused site. Injective site placement gives the stated routing bound.
If the two child circuits each cost at most \(T\), the joining primitive costs at most \(M\), and each reflection costs at most \(F\), exact amplification at a bond of dimension at most \(D\) costs at most
A numerical recurrence \(T_{j+1}\leq RT_j+C\) with \(R\geq 2\) and \(T_0\leq a\) satisfies, at balanced height \(L=\lceil \log _2N\rceil \),
For \(D{\gt}0\), the branching exponent satisfies \(\lceil \log _2(4D+2)\rceil \leq \lceil \log _2D\rceil +3\). These assertions are numerical consequences of the stated recurrence.
Substitute the joining and reflection bounds into the exact amplification gate count. Induct on \(j\) using \(T_j+C\leq (a+C)R^j\). Ceiling-logarithmic bounds give \(R\leq 2^{\lceil \log _2R\rceil }\) and \(2^L\leq 2N\). Finally \(4D+2\leq 8D\) for \(D\geq 1\).
The configurations of the interval between the two endpoint cuts are canonically identified with physical configurations of the complete chain. Both endpoint bond spaces have their normalized one-dimensional bases.
For every finite unitary with \(d{\gt}0\) and \(N{\gt}0\), the actual endpoint affine Gram spaces of the normalized minimal representation are singleton identity spaces. The coherent metric family therefore has \(P_0=P_N=I\). Its weighted complete interval is exactly the original unitary, entry by entry, including its complex phase. This family and all its interval isometries are derived from unitarity; no metric or interval witness is supplied.
The empty prefix has Gram equal to its input trace. At the final cut, global unitarity gives the same identity. Every normalized endpoint Gram is thus the identity, as is its entire affine hull. Minimal-coordinate reconstruction identifies the complete interval with the original matrix. Identity endpoint weights preserve it.
For positive definite \(P\) on a bond of dimension \(r{\gt}0\) and \(Q=P^{-1}/r\), the source’s transpose expression satisfies
These metrics give an explicit candidate of joining norm \(r\). The assertion does not bound the appendix’s infimum restricted to physical cap Grams in [ 240 ] .
Reverse the matrix product under transpose and use invariance of trace under transpose. The balanced inverse-trace identity gives \(r^2\). Its real part is nonnegative and its positive square root is \(r\). The interval and flag conventions are expanded explicitly in [ 249 ] , Section 5.
The support of an interval consists of its physical sites, all strictly interior bond and amplification sites, the inward-facing bond register at its left boundary, and the inward-facing bond register at its right boundary. Endpoint bond registers have width zero. The interior is initialized when every strictly interior auxiliary site is in its designated initial configuration. A leaf packet has one physical site and its two available boundary bond registers.
For adjacent nonempty child intervals \(\lbrack j,m)\) and \(\lbrack m,k)\), their logical supports are disjoint. Their union together with the two amplification flags at \(m\) is exactly the parent support. Operators supported on the two child intervals commute. The parent interior is initialized precisely when both child interiors and all joining auxiliaries are initialized. A leaf has no interior auxiliary sites, and its packet placement is injective with range exactly its interval support. Thus no neighboring bond register is borrowed at an endpoint.
Separate physical sites, bond sites, and flags. The two boundary sides at a joining cut are different registers; its flags belong to neither child. These observations give both disjointness and the stated union. The explicit leaf placement has the same range. Disjoint support implies commutation, and the partition of interior auxiliary sites gives the initialization equivalence.
Given an injective selection of qudit flags, include arbitrary configurations on the remaining sites by assigning zero to each selected flag. Denote its basis-inclusion matrix by \(E\).
For any injective basis encoding, its range projection is the diagonal indicator of its encoded configurations. Consequently, the selected-flag inclusion has
This is an orthogonal projection, and the reversible selected-zero circuit reflects it exactly. For \(d\geq 2\), an \(n\geq 2\) logical register and a scratch pool of size \(A\) at least the number of selected flags, an actual circuit implements \(I-2EE^\dagger \) with the selected-reflection gate bound and returns the whole pool to zero on every logical input. No reflection identity or circuit decomposition is assumed.
Multiplying an injective basis inclusion by its adjoint sums orthogonal basis projections over its image. The image of the selected-flag inclusion is exactly the stated zero-flag set. Substitute this projection identity into the already constructed shared-pool selected-reflection circuit.
Encode the label space of every internal cut in its common bond register, and encode a one-dimensional endpoint label space in the unique configuration of a zero-site register. In each case, the distinguished label zero is represented by physical zero.
A finite unitary whose minimal physical cut ranks are at most \(D\) admits simultaneous zero-preserving encodings at all cuts in precisely their allocated registers. Both endpoint ranks are derived to be one; no endpoint rank witness is required. Consequently the entire endpoint label space is represented by the unique empty configuration.
Nonvanishing of the operator coefficient tensor gives rank one at the empty and complete cuts. Its remaining cut ranks fit the ceiling-logarithmic capacity. Choose basis embeddings and exchange the image of the distinguished zero label with physical zero.
An interval of length one is a leaf. Split every longer interval at its midpoint into consecutive children of lengths \(\lfloor n/2\rfloor \) and \(\lceil n/2\rceil \). Label each internal node by its actual joining cut. A consecutive interval partition records these nonempty child intervals and their single-site leaves.
For every \(N{\gt}0\), midpoint splitting constructs a genuine binary partition of the \(N\) consecutive physical sites, without a supplied tree. Its leaves are precisely those \(N\) sites, in physical order; its internal nodes are precisely the \(N-1\) internal cuts, also in physical order. Every such cut occurs exactly once. Its height is exactly \(\lceil \log _2N\rceil \), including lengths which are not powers of two.
Strong induction on the interval length constructs its two strictly shorter nonempty children. Concatenate their site and cut ranges. The larger child has ceiling logarithm one less than the parent, which proves the exact height formula.
Give every leaf cost \(K\). At a node whose children have costs \(T_1,T_2\), let \(T_0=T_1+T_2+M\) and assign cost \(\ell (1+2T_0+B+L)+T_0\), where \(M\) bounds the joining operation, \(B,L\) bound the two reflections, and \(\ell \) is the number of amplification rounds at that node. Define \(C=(2D+1)M+D(1+B+L)\).
If every amplification count satisfies \(\ell \leq D\), then the recursively defined count on any binary tree of height \(h\) satisfies
On the actual midpoint partition of \(N{\gt}0\) consecutive sites,
These are bounds on the stated numerical recursion; existence of the corresponding recursive circuits is a separate assertion. Setting every round count equal to \(D\) gives exactly the recursion with child multiplier \(2D+1\) and additive term \(C\).
Each node has cost at most \((2D+1)(T_1+T_2)+C\). Keeping the reserve \(C\) in the induction invariant proves the height bound. The height of the midpoint tree is \(\lceil \log _2N\rceil \), and the ceiling-logarithmic power comparison gives the displayed polynomial bound.
Identify the physical configurations of a single-site interval with its local physical alphabet. Reindex its weighted interval isometry so that the output coordinates are, in order, its physical output, its right bond label, and its left bond label.
For \(d\geq 2\) and \(N{\gt}0\), a finite unitary with consecutive operator Schmidt ranks at most \(D\) admits one minimal open representation, one family of balanced positive cut metrics, and exact circuits for every weighted single-site interval of that same family. The endpoint metrics equal one and the full weighted interval equals the original unitary, including its complex phase. Each leaf circuit implements a unitary extension on its entire padded logical packet, using one workspace qudit which it returns to zero on every logical input. For left and right register widths \(q_-,q_+\), its gate count is at most \(38\bigl(d^{2+q_-+q_+}\bigr)^6\).
Choose normalized bases at the two endpoint cuts and derive the balanced metrics and all interval isometries from unitarity. Reindex each one-site interval and extend its isometry to a unitary on the padded packet. Apply the exact unitary synthesis with one initialized workspace qudit. Endpoint bond labels use zero-site registers.
For a chain of at least two sites, choose one qudit in the common workspace. Embed each leaf packet in its physical site and its two boundary bond registers, and place its workspace qudit in the chosen common site.
Let \(d\geq 2\) and \(N\geq 2\). A finite unitary with consecutive operator Schmidt ranks at most \(D\) admits coherent normalized interval metrics and exact leaf circuits placed in the complete register. Every logical leaf unitary acts only on its interval support. Its complete circuit returns the entire common workspace to zero on every logical input, with gate count at most
where \(n_{\mathrm{tot}}\) is the total number of physical, bond, flag, and workspace qudits.
Place the local circuit using the two site embeddings. The clean implementation identity is preserved under placement. A local gate uses at most \(2n_{\mathrm{tot}}\) gates after routing. The ceiling-logarithmic capacity bound gives local packet dimension at most \(d^4D^2\). Positivity of the minimal cut ranks supplies \(D{\gt}0\), and \(N\geq 2\) supplies the common workspace site.
For a one-site operator \(U\), define its two-site padding by applying \(U\) to the first site and the identity to the second.
Every one-site unitary in positive physical dimension has an exact implementation by one neighboring two-qudit gate with one padding qudit. The padding qudit remains exactly zero for every physical input, and the complete scalar phase is retained. In fact the padded operator is \(U\otimes I\) on the full two-site space.
The padded operator is unitary and supported on the sole neighboring pair. Its initialized columns are the columns of \(U\) tensored with the zero basis vector of the second site.
Concatenate a spectator basis encoding with the two bond registers and their dilation and attenuation flags. Each flag is an entire physical qudit, with the two distinguished values zero and one. For a positive cut metric \(P\) of dimension \(r\), let \(M_P\) be its normalized bond-reset operator. For joint child columns \(V\), define the normalized parent by \(r(I\otimes M_P)V\) and encode its output with both flags zero. Define the joining cost by the actual dilation and attenuation costs, including their routing, followed by the two selected-zero reflections and the amplification rounds.
Let \(d\geq 2\), \(r{\gt}0\), and \(P{\gt}0\). Encode each bond label in \(q\) qudits with its distinguished label represented by physical zero. Suppose that two child circuits implement full logical unitaries with the same initialized workspace, that their initialized product columns equal the prescribed encoding of \(V\), and that \(r(I\otimes M_P)V\) is an isometry. Let \(b\) be the number of flags initialized at the parent input and let the common workspace contain at least \(\max (b,2)\) qudits. Then an actual pair-gate circuit implements the encoded normalized parent exactly on those input columns. It also implements a full logical unitary, and its adjoint implements the adjoint logical unitary with the same workspace returned exactly to zero on every logical input. If \(K_1,K_2\) are the child costs and \(M\) is the joining cost, its gate count is
where \(R_b,R_2\) are the actual common-workspace reflection costs. The success probability is derived from the normalized parent isometry; it is not an additional assumption. The same full logical unitary is supported in any set containing both child supports, the initialized input flags, and the joining packet, including on padded logical states.
Construct the bond dilation and the attenuation rotation on the prescribed product basis. Their successful physical branch is \(\sin (\pi /(4\ell +2))\) times the encoded normalized parent. Its isometry identity gives the constant squared success amplitude. Construct both reflections by testing the selected initialized flags in the common workspace. Exact amplification gives the parent columns with their full phase, and the all-input clean identities justify every inverse child call. The preparation acts only on the joining packet. Conjugating the initialized reflection by that supported preparation and the child unitaries, then multiplying the two reflections and taking powers, preserves the claimed logical support.
This joining theorem is an induction step with explicit child columns and parent isometry as hypotheses. Identification of those columns with arbitrary MPU intervals, and the complete recursive existence statement, remain separate assertions.
The auxiliaries initialized at an interval input are the auxiliary sites in its logical support, including both boundary bond registers. Enumerate any finite logical support by a finite site injection, using the fixed consecutive ordering of logical sites.
Every set of logical auxiliary sites has cardinality at most the total number of allocated auxiliaries. In particular, the interior auxiliary sites of an interval, its two joining bond registers and two joining flags, and all auxiliaries initialized at its input fit in the common workspace. Their finite selections are constructed, and testing the selected consecutive coordinates for zero is equivalent to testing the original logical support.
Each support is contained in the image of the auxiliary-site injection. Inject it into the full auxiliary register and compare cardinalities. A finite enumeration transported through the logical coordinate equivalence gives the required site selection and its exact zero-test identity.
Decompose a complete logical configuration into its two disjoint child packets and its remaining sites. Concatenate prescribed input or output basis encodings on the child packets with a prescribed spectator encoding on the remaining sites.
Suppose the two child packets are disjoint and their individual column identities are \(XE_g=E_{g'}V\) and \(YE_h=E_{h'}W\). Placing the child operators in the complete register gives the joint column identity with output map \(V\otimes W\otimes I\), for every encoded spectator state. No extra joint column identity is assumed. In these coordinates the product of the placed operators is exactly \(X\otimes Y\otimes I\).
Expand the matrix product of the two disjoint placed operators. Agreement of the remaining coordinates reduces the sum to the two independent child matrix entries. Relabel the configuration by the two packets and the remaining sites, and apply the two individual column identities inside their tensor product.
Put \(q=\lceil \log _dD\rceil \), let \(g\) be the complete register size, and let \(A\) be the common workspace size. A common packet budget is
Reserve an additional \(16g^2\) for coordinate permutations, and use \(M=M_0+16g^2\) as a common leaf and node overhead. The common reflection budget is \(F=1+K_d(A)\, 2g\), where \(K_d(a)=8(38d^{18}+1)a^2+4a\). Define the midpoint-tree count using leaf cost \(M\), joining cost \(M\), and two reflection costs \(F\). Finally put
The placed leaf budget and the stated routed joining-packet budget are at most \(M_0\) for \(d\geq 2\) and \(D{\gt}0\). Every selected reflection testing at most \(A\) flags, including the empty selection, has cost at most \(F\). For \(N{\gt}0\), the latter satisfies
If every node uses at most \(D\) amplification rounds, the stated numerical tree count satisfies
The coefficient \(c(d,D)(D+1)^3\) is polynomial in \(D\) for fixed \(d\), of degree at most sixteen. This theorem bounds the numerical recursion and does not assume complete recursive circuit existence.
The capacity bound gives joining-packet dimension at most \(d^4D^2\) and \(q\leq D\). Monotonicity of \(K_d\) gives the uniform reflection bound. The allocation gives \(A\leq 2N(q+1)\) and \(g\leq 5N(q+1)\). Thus every node overhead is at most a coefficient depending only on \(d,D\) times \(\bigl(N(q+1)\bigr)^3\). Substitute these estimates in the actual balanced-tree recurrence and use \(\lceil \log _2(4D+2)\rceil \leq \lceil \log _2D\rceil +3\).
The reflection which changes sign precisely when a selected set of qudits is zero is supported on those qudits. All states of the remaining logical qudits are allowed. This includes the empty selection, whose reflection is the scalar minus identity.
A diagonal operator placed on a selected packet depends only on the selected configuration, and has a Kronecker delta on the remaining coordinates. Apply this identity to the local diagonal all-zero reflection.
Suppose \(Z\) is a unitary supported on \(S\), and the reflections about the initialized image \(EE^\dagger \) and the successful projection \(P\) are also supported on \(S\). Then the full logical amplification operator
is supported on \(S\), with its exact scalar phase retained. Support of the two projections themselves suffices to derive support of their reflections. No initialization of the remaining logical sites is imposed.
Conjugating the initialized reflection by \(Z\) gives the displayed image reflection. Operators supported on \(S\) are closed under adjoints, products, powers, addition, and scalar multiplication, including multiplication by minus one.
Enumerate an interval’s logical support as its physical packet. Its input encoding records the physical input configuration and sets every auxiliary to zero. Its output encoding records its physical output, right bond label, and left bond label, using prescribed injective encodings in the two boundary registers and setting every strict-interior auxiliary to zero.
The input and output maps are injective and agree with all of their recorded physical and boundary coordinates. The output has every strict-interior auxiliary exactly zero. Both maps include the zero-width endpoint registers. Consecutive child packets are disjoint and their site enumerations have precisely the prescribed interval supports.
Read the physical and two boundary registers to recover the encoded coordinates. The two boundary embeddings have disjoint images, and the remaining auxiliary entries are set to zero. The interval-support identities give the enumeration and disjointness statements.
Split the physical configuration of an interval \([j,k)\) into its two consecutive restrictions to \(\lbrack j,m)\) and \(\lbrack m,k)\).
The normalized joining contraction of the two balanced adjacent intervals equals the actual weighted parent interval, after splitting its physical coordinates, with the joining label pair reset to zero. Consequently the computed parent is an isometry whenever the left cut metric belongs to its prefix Gram affine space and the right dual metric normalizes its affine space. For every finite unitary on \(N{\gt}0\) sites in positive physical dimension, one endpoint-normalized minimal basis and coherent positive metric family satisfying these conditions exists, and all its joining parents are isometries simultaneously. No parent-isometry hypothesis is supplied in this existence statement.
The normalized bond reset cancels the two weighted metrics at the common cut. Multiplication of the actual minimal interval factors gives the parent factor. Relabel its physical coordinates by the two consecutive children and apply the previously derived weighted-interval isometry identity. The simultaneous normalized metric family follows from global unitarity.
Encode a child packet together with a basis encoding on its remaining logical sites. Taking the identity basis encoding on those sites allows every outside logical configuration.
Let two global operators have disjoint child supports. Their individual initialized-column identities, each retaining every outside logical configuration, imply their joint column identity with output map \(V\otimes W\otimes I\) for every spectator encoding. Local child matrices and the joint column identity are derived; neither is an additional hypothesis.
Support supplies local matrices. Relabel the complete configuration by a child packet and its complement; the global identity is then the local identity tensored with an identity on that complement. Recover the local identity by taking a fixed diagonal spectator entry, and apply the disjoint-child product-column theorem.
Extend a permutation of the logical sites by the identity on the appended workspace sites, transporting the disjoint sum to the consecutive site coordinates.
Every permutation of \(n\) qudit sites has an actual neighboring pair-gate circuit of at most \(2n^2\) gates. Conjugating a circuit of cost \(K\) by that permutation gives cost at most \(K+4n^2\), including its exact scalar phase. For positive local dimension \(d\), a logical site permutation fixing the appended workspace preserves every all-input clean implementation identity. For a register of total size \(n+A\), this conjugation costs at most \(K+4(n+A)^2\).
The finite permutation factors into at most \(n\) transpositions, each routed with at most \(2n\) neighboring swaps. Use the permutation circuit and its adjoint on the two sides of the original circuit. The extended permutation changes only logical coordinates and fixes each initialized workspace site, which gives the exact clean identity under conjugation.
Fix the minimal cut bases and one balanced metric family of the given unitary. The input of an interval consists of its physical configuration with all interval auxiliaries initialized to zero, together with an arbitrary configuration outside the interval. Its output consists of the weighted interval amplitudes in the prescribed cut-label encodings, with all strictly interior auxiliaries zero and the outside configuration unchanged. An interval implementation satisfies this complete column identity.
For adjacent nonempty intervals, suppose each logical operator has its interval support and satisfies the actual interval column identity. Their product has the tensor product of the two weighted child maps as its initialized columns, with the identity on every configuration outside their combined support. No joint column identity is an additional assumption.
The child supports are disjoint. Their individual column identities therefore determine the columns of their product by finite matrix multiplication. The prescribed cut-label encodings occur in the resulting product without a further change of bond basis.
Fix one minimal cut basis and balanced metric family. An interval circuit implementation of budget \(K\) consists of a full logical unitary supported on the interval and a neighboring-pair circuit of at most \(K\) gates. The circuit implements that logical unitary with the common workspace returned to zero on every logical input. Its initialized interval columns are the actual weighted interval columns, including arbitrary outside configurations.
Suppose single-site implementations of budget \(K\) and an adjacent-interval merging rule have been established for the same fixed basis and metric family. If that rule gives budget \(b(K_1+K_2)+M\) from child budgets \(K_1,K_2\), then every consecutive interval partition has an actual circuit with exactly its numerical tree budget. All logical support, workspace cleanup, and actual interval column identities are retained. Increasing a budget preserves these identities.
Induct on the consecutive interval partition. Its leaves use the given single-site circuits. Each node uses the given merging rule on the two actual child implementations, whose endpoint cuts coincide. The resulting gate budget is the defining numerical tree recursion. This conditional statement requires the leaf and merging constructions to be established separately.
At an internal cut, order the joining packet as the left child’s right bond register, the right child’s left bond register, the dilation flag, and the attenuation flag. Its consecutive site inclusion is determined by the allocated logical registers.
The ordered packet inclusion is injective and has the prescribed restrictions to both bond registers and both flags. There is a permutation of the full logical register sending its final packet to precisely these actual sites in this order. Both the remaining prefix size and this permutation are derived from the site inclusions; neither is an additional geometric assumption.
The allocated bond and flag sites are disjoint. Their injective enumerations give the packet inclusion. Its cardinality does not exceed the logical register size. Extend the correspondence between the final packet inclusion and the actual packet inclusion to a permutation of the finite site set.
Given an injective full basis encoding with a prescribed suffix depending only on its bond label, fix one bond label and restrict the full encoding to the prefix registers. This defines the prefix basis inclusion.
Suppose the suffix of the full encoding is the prescribed bond encoding, and its prefix is independent of the bond label. Then the prefix inclusion is injective, and its product with the prescribed suffix is exactly the full encoding.
Prefix equality, together with equality of the fixed suffix, gives equality of full encoded configurations. Full injectivity therefore gives prefix injectivity. Restriction to the two coordinate blocks proves the product identity.
Combine the prescribed child output inclusions on their disjoint interval supports with an arbitrary outside basis inclusion. Setting a selected set of outside coordinates to zero gives its initialized complement inclusion.
The joint output restricts to the prescribed left and right child configurations and to its prescribed outside configuration. Changing the two joining bond labels affects only their two allocated bond registers. Every other coordinate, including initialized interior auxiliaries and outside spectators, is independent of those labels.
Restrict the joint product inclusion to its disjoint coordinate blocks. The interval boundary configuration reads a bond label only at its allocated boundary register. The stated independence follows by distinguishing those boundary sites from all others.
For a one-site interval, identify its consecutive packet with the physical site followed by its right and left boundary bond registers. The induced configuration bijection preserves the prescribed physical and boundary coordinates.
For \(d\geq 2\) and \(N\geq 2\), a finite unitary of consecutive cut ranks at most \(D\) admits one normalized minimal basis and metric family whose placed leaf circuits satisfy the actual interval column identities. The previously constructed circuits and logical operators remain exactly the same, with their gate counts, support, and all-input workspace cleanup. The outside configurations are arbitrary. No separate interval column identity is assumed.
The packet coordinate bijection fixes the actual physical and boundary sites. Transport the input and output basis inclusions through it, together with the weighted single-site map. Reindexing the local operator commutes with its placement in the logical register. Thus the existing local columns give the actual interval columns without a further gate or change of unitary extension.
Include the physical chain into the logical register with its auxiliaries zero. Include the logical register into the complete register with the common scratch pool zero. Their composition includes the physical chain with every auxiliary zero.
Let a logical operator satisfy the actual full-interval column identity of the given finite unitary \(U\). Normalize the minimal endpoint bases and take the endpoint metrics in their actual prefix Gram spaces. If a complete circuit \(C\) implements that logical operator with the common scratch pool returned to zero on every logical input, then
where \(J\) initializes every logical auxiliary and scratch qudit. The physical output and the scalar phase follow from the given unitary; they are not additional assumptions.
The full packet contains every logical site, so its outside configuration is unique. Both endpoint bond registers have width zero. The actual endpoint Gram spaces and normalized bases make the full weighted interval equal to \(U\). The two root basis inclusions therefore become the physical inclusion with logical auxiliaries zero. Compose its column identity with the full logical clean-workspace identity to obtain the stated equality.
Append one padding qudit when \(N=1\), and none otherwise, to the physical register, logical auxiliaries, and reusable scratch pool. The physical basis inclusion initializes all three groups to zero.
The complete register has at most \(5N(q+1)+1\) sites, where \(q\) is the bond-register width. Its physical basis inclusion is the physical configuration followed by zeros on the logical auxiliaries, scratch pool, and padding.
The padding count is at most one. Apply the common register bound and expand the three successive initialized inclusions.
View the two joining flags as sites outside both child packets. Initialize exactly these flags and retain arbitrary configurations on all other outside sites.
The joining flags lie outside both child packets. The joint output inclusion, with these outside flags initialized, has both joining flags equal to zero.
The joining flag sites are disjoint from both interval packets. Their outside inclusion sets exactly these two coordinates to zero.
The actual joint child output restricted to the joining packet is precisely the active compatible bond code, with the shared right and left labels in contraction order and both flags zero.
Evaluate the prescribed boundary configurations on the two shared bond registers, then use the initialized joining-flag identities.
Regroup the physical outputs, outer cut labels, and outside configurations before the two joining labels. Pull a basis inclusion back along a site bijection to place the joining packet at the end.
The actual joint output admits a derived site bijection and a product code: a prefix encoding independent of the joining labels, followed by the compatible joining-packet code. The prefix encoding is injective. Neither the site bijection nor its factorization is supplied as a hypothesis.
Use the actual ordered joining packet and its complementary site bijection. Every prefix site is independent of the joining labels. Injectivity of the full joint output code therefore implies injectivity of its prefix factor.
Suppose two full clean child circuits have the stated encoded joint columns, logical support inside a prescribed set, and an isometric normalized parent. A site bijection putting the joining packet last yields a merger in the original coordinates. Its logical support, initialized columns, and scalar phase are preserved. Each child conjugation and the final return costs at most \(4g^2\) neighboring-pair gates, where \(g\) is the complete logical and scratch site count.
Conjugate both child circuits into the suffix coordinates. Apply the supported encoded merger, then conjugate its logical and physical operators back. The site permutation fixes the scratch pool. Its basis action transports the rectangular initialized columns exactly.
For \(N\geq 2\), \(0{\lt}r\leq D\), and a selected initial flag count within the allocated pool, the encoded merger including both child conjugations and its final return has gate count at most
where \(M\) is the common node budget and \(F\) is the common reflection budget. The quadratic routing reserve is included in \(M\).
Bound the joining preparation by the common packet budget, both reflections by \(F\), and the prescribed number of amplification rounds by \(r\leq D\). Expand the gate formula. The node reserve absorbs the three conjugations.
Tensor the two weighted interval columns with the identity on the remaining outside configurations, and move those configurations before the joining labels.
The normalized joining contraction commutes with the spectator identity after this regrouping. Thus its isometry follows from the actual normalized parent isometry. The regrouped child tensor is precisely the actual weighted child Kronecker tensor, with every spectator coordinate retained.
Expand the joining contraction entrywise. The spectator Kronecker delta passes through its finite sum. Reindex the actual child product and use the actual parent isometry.
Two injective basis encodings with the same image determine a unique bijection between their label sets, carrying each encoded configuration to itself.
The matrices of initialized basis inclusions respect composition and products. The derived label bijection transports equal-range encodings exactly. Appending a compatible active joining code is the corresponding product basis inclusion.
Equal images and injectivity determine the label bijection. Matrix multiplication of the basis inclusions reduces to their Kronecker deltas.
Pulling an initialized input encoding back along a site bijection transports its image to the zero-flag inclusion on the transported selected sites. This gives the complete initialized input subspace, retaining arbitrary configurations outside the selected flags.
Membership in the pulled-back image is membership in the original image after the site bijection. The zero conditions are precisely its transported selected sites.
The remaining sites outside two adjacent child packets and the joining flags are identified with the sites outside the parent packet. Join the two physical input configurations and transport the arbitrary remaining configuration along this site bijection.
The joint initialized child input is exactly the parent initialized input under the derived configuration bijection. Their images equal the zero-flag subspace selected by the parent auxiliary sites. The two actual child column identities, together with their support conditions, therefore give the joint initialized child columns; no input bijection or joint-column identity is assumed.
The parent support is the union of the two child supports and the joining flags. Its complement gives the remaining-site bijection. Evaluate the two input configurations on these disjoint sets. Compose the supported child identities with the resulting initialized inclusion.
Suppose the shared cut code sends its distinguished zero label to the zero bond configuration. The actual joint output with both shared labels reset to that label is exactly the parent output inclusion, after joining the physical outputs and transporting the arbitrary remaining configuration. This equality includes both joining flags and every interior auxiliary.
Evaluate on the left child, right child, joining flags, and parent complement. The reset code makes both shared bond configurations zero, the flags are initialized to zero, and the outer labels and arbitrary outside configuration agree with the parent boundary configuration.
For an ordinary periodic MPO of virtual dimension \(\chi \), every consecutive operator coefficient cut has rank at most \(\chi ^2\). The same bound holds for an arbitrary trace boundary. Scalar left and right open boundaries give the bound \(\chi \). These statements require no unitarity, normalization, minimality, or canonical-form assumption.
Split the ordered word at the physical cut. A trace contraction factors through its two open virtual indices; scalar open boundaries factor through one. The cut matrix rank is bounded by the dimension of this intermediate space. For an MPO, its paired-letter coefficient tensor is exactly the corresponding ordinary matrix-product tensor.
Physical and input-output coordinate bijections transport exact initialized column identities. Input-column reindexing commutes with the normalized joining parent. A full clean implementation through an isometric initialized inclusion also determines the exact logical columns from its ambient columns.
Use the matrix reindexing product identity. Reindexing input columns passes through the joining finite sum. To recover logical columns, multiply the ambient identity by the adjoint of the initialized inclusion.
Multiplication of an initialized basis inclusion by the reset columns selects its prescribed reset label. The same identity retains every spectator configuration in the regrouped joining tensor.
Expand the basis inclusion. Its Kronecker delta leaves only the reset label; the spectator delta is unchanged.
The two shared bond registers and both joining flags lie inside the parent interval support. Consequently the range of the actual ordered joining packet is contained in that support.
The joining cut is strictly between the parent endpoints. Its two bond registers belong to the respective interval boundary and interior sets, and its flags belong to the parent interior. Apply the site-coordinate bijection.
Every one-site unitary has a one-gate neighboring-pair circuit on the physical site and one padding qudit, with the padding returned exactly to zero. When \(N\geq 2\), the additional padding is empty: any exact circuit on the physical, logical auxiliary, and scratch register transfers to the complete register with the same gate count and physical columns.
At one site the complete register has two sites. Transport the padded physical unitary along this equality of site counts. At longer lengths, append the empty padding configuration and transport along the resulting site equality.
Each of two adjacent child supports is contained in their parent support. The actual selected initialized sites remain in the parent support after a site-coordinate change. If that change puts the actual joining packet last, its entire suffix range also lies in the transported parent support.
Use the consecutive support decomposition at the joining cut. The selected sites are the actual parent auxiliaries, and the suffix range is the image of the actual joining packet.
Given exact input and output coordinate identities, transport the actual joint child columns to the compatible encoded joining columns. The normalized parent remains an isometry under input reindexing and addition of arbitrary spectator identity factors.
Compose the initialized basis inclusions and reindex matrix products. Apply the normalized joining contraction before reindexing the input; its finite sum is unchanged. The spectator identity preserves the isometry.
Suppose the actual joint output inclusion has its derived product-coordinate description and the joining metric is positive definite. Returning the encoded normalized joining contraction to the original physical coordinates gives exactly the weighted parent interval columns. Both shared bond labels and joining flags are reset to zero. Arbitrary outside configurations are retained. The parent-column and reset equalities are consequences, rather than additional assumptions.
Transport the initialized basis inclusion and cancel the input-coordinate bijection. The normalized joining identity gives the weighted parent tensor. The concrete zero-label identity identifies the reset output inclusion with the parent inclusion, including its unchanged outside register.
An operator satisfying the actual parent columns on the joint child input satisfies every initialized parent column, with the outside configuration unrestricted.
The derived joint input-coordinate bijection covers the parent input inclusion. Evaluate the joint column identity at the inverse image of each parent column.
Let the minimal cut metrics be positive definite elements of their prefix Gram affine hulls, with their dual metrics normalizing every element of those hulls. Two exact supported implementations of adjacent intervals, with gate counts \(K_L,K_R\) and one common auxiliary workspace returned to zero on every logical input, give an exact supported parent implementation. Its initialized columns are the actual weighted parent interval, including arbitrary outside states. Its gate count is at most
where \(K\) and \(F\) are the uniform joining and reflection bounds. The same workspace is returned to zero on every logical input.
Derive the shared cut encoding, product coordinates, selected initialized sites, and normalized parent isometry from the actual minimal intervals. Apply exact clean amplification in these coordinates and return to the original site order. The preceding two column results establish the parent invariant. The uniform joining estimate gives the displayed recurrence.
Let \(d\geq 2\) and \(N\geq 2\), and let \(U\) be a unitary whose consecutive operator cut ranks are at most \(D\). There is an exact neighboring two-qudit circuit with at most
gates, where \(c(d,D)\) is the explicit polynomial coefficient in the uniform resource estimate. All initialized logical auxiliary and scratch qudits are returned to zero, and the physical action has the exact phase of \(U\).
Obtain the minimal representation, normalized metrics, and leaf circuits from \(U\). Supply the actual merger to the midpoint-tree induction, use the uniform resource estimate, and identify the root columns with \(U\).
Fix \(d\geq 2\). Let \(U\) be a unitary on \(N\geq 1\) qudits of consecutive operator Schmidt ranks at most \(D\). It has an exact circuit of neighboring two-qudit gates with gate count
and \(O_d(N\log (D+1))\) auxiliary qudits which begin and end exactly in zero. The same form of bound holds on a line. In particular, both exact and arbitrarily accurate operator-norm circuit implementations have polynomial resources at fixed \(D\).
Take a minimal open-boundary MPO representation, with cut dimensions \(r_j\leq D\) and \(r_0=r_N=1\). Let \(f_{\mathbf a,\mathbf b}\) be its prefix rows at cut \(j\). For each prefix density matrix \(\rho \), define
These are positive semidefinite. The maximally mixed prefix Gram is positive definite by minimality, as is the maximally mixed suffix Gram \(\overline Q_j\). Global unitarity gives \(\operatorname {Tr}(P_j(\rho )\overline Q_j)=1\). Apply the lemma to the real affine hull \(\mathcal C_j\) of all prefix Grams. Obtain \(P_j^*{\gt}0\) and \(Q_j^*=(P_j^*)^{-1}/r_j\) normalizing every element of \(\mathcal C_j\). At the endpoint cuts the affine space is \(\{ 1\} \), so both metrics are one.
For an interval from cut \(j\) to cut \(k\), write its tensor product as \(T_{\mathbf a,\mathbf b}\). Any interval density matrix \(\sigma \) defines the positive transfer
The identity \(\mathcal T_\sigma (P_j(\rho ))=P_k(\rho \otimes \sigma )\) gives \(\mathcal T_\sigma (\mathcal C_j)\subseteq \mathcal C_k\). Hence \(\operatorname {Tr}(Q_k^*\mathcal T_\sigma (P_j^*))=1\) for every density matrix \(\sigma \). This proves the complete interval isometry identity by polarization, including all off-diagonal input entries. With \(L_j=(P_j^*)^{1/2}\) and \(R_j=(Q_j^*)^{1/2}\), its amplitudes are \(L_jTR_k\).
At a joining cut the contraction is \(R_j^{-1}L_j^{-1}=\sqrt{r_j}\, I\), of norm \(r_j\leq D\). The normalized contraction is a Bell bra and has constant success amplitude \(1/r_j\) on the child images. Exact subspace amplification uses \(O(D)\) child invocations per merge. One-site isometry extensions and Bell transformations have polynomial gate cost in \(D\). Image reflections conjugate the initialized-auxiliary reflection by the full preparation, including both children, joining dilation, and attenuation. Their reversible conjunctions reuse one common \(O(N\log (D+1))\) scratch pool. The balanced recursion therefore has polynomial cost at fixed \(D\), with exponent \(O(\log (D+1))\). Every inner flag is erased exactly; the root interval is \(U\) with no outer flags. Routing on a line adds at most a linear factor in the total number of registers. The complete proof and bounds are in [ 249 ] , Section 5.
The metric is chosen in the positive semidefinite slice of an affine space, which may contain real affine combinations with negative coefficients. Its positivity supplies a physical isometry; the affine identities supply its normalization. This removes the spectral condition from the general nonuniform circuit statement of [ 240 ] . It asserts circuit existence with arbitrary gates, without an additional claim about computing exact gate parameters from finite-precision input data. A periodic bond-\(D\) presentation has an open presentation of bond at most \(D^2\), and is therefore covered at fixed \(D\).