- Boxes
- definitions
- Ellipses
- theorems and lemmas
- Blue border
- the statement of this result is ready to be formalized; all prerequisites are done
- Orange border
- the statement of this result is not ready to be formalized; the blueprint needs more work
- Blue background
- the proof of this result is ready to be formalized; all prerequisites are done
- Green border
- the statement of this result is formalized
- Green background
- the proof of this result is formalized
- Dark green background
- the proof of this result and all its ancestors are formalized
- Dark green border
- this is in Mathlib
The bounds of Theorem 13.14.8 hold for \(S(D)\) with \(\delta =\delta (\rho _D,\sigma _D)\) and states on \(D\). For states \(\rho ,\sigma \) on \(D\otimes E\), the change of \(I(D:E)=S(D)+S(E)-S(DE)\) is at most the sum of the two moduli, at \(\delta (\rho _D,\sigma _D)\) and \(\delta (\rho ,\sigma )\), and hence at most \(8\sqrt{\delta (\rho ,\sigma )}\, \log (e\, d_D)\), independently of the dimension of \(E\).
Let \(\Delta {\gt}0\) and \(p\ge 0\) be real, and set \(r_*=2p+10\). The constants \(A,T_0\) in Theorem 13.30.6.1 can be chosen as functions of \(\Delta ,p\) before \(b,L\) are specified. They satisfy the two coefficient bounds with threshold \(40+2p\), and (337) and (338) hold with \(r=r_*\) for every \(b\ge 0\) and \(L\ge 1\).
For \(s\in [0,1]\), \(t\in [0,1]\), and positive-definite matrices \(A_1,A_2,B_1,B_2\), the map \((A,B)\mapsto \Re \operatorname{tr}(A^s B^{1-s})\) is jointly concave:
Obtained from Theorem 7.7.13 by taking \(K=\mathbb {1}\).
The peripheral projection of a positive trace-preserving map is positive and trace-preserving, and then the phase-weighted map \(T_\varphi \) is positive and trace-preserving as well. If the original map is completely positive, then \(T_\phi \) and \(T_\varphi \) are quantum channels. This is the preservation assertion in the opening clause of [ Wol12 , Proposition 6.3 ] (item (ii) itself states only the composition identity).
- IsPositiveMap.peripheralProjection_isPositiveMap
- IsPositiveMap.peripheralProjection_isTracePreservingMap
- IsPositiveMap.peripheralWeightedProjection_isPositiveMap
- IsPositiveMap.peripheralWeightedProjection_isTracePreservingMap
- IsPositiveMap.peripheralProjection_isCPMap
- IsChannel.peripheralProjection
- IsChannel.peripheralWeightedProjection
Let \(T:M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) be a trace-preserving positive linear map. Then for all density matrices \(\rho _1,\rho _2\in M_{D}(\mathbb {C})\), \(\lVert T(\rho _1)-T(\rho _2)\rVert _{\operatorname{tr}} \leq \lVert \rho _1-\rho _2\rVert _{\operatorname{tr}}\). See [ Wol12 , Chapter 8, Eq. (8.80) ] .
Write \([k]=\{ 0,\ldots ,k-1\} \). Let \(B\subseteq [k]\) have cardinality \(r\), and fix its standard finite enumeration \([r]\simeq B\). A five-factor configuration on \([r]\) corresponds to a physical \(QYV\) configuration indexed by \(B\) and auxiliary \(C,R\) configurations indexed by \([r]\). Grouping the physical factors and applying this enumeration gives an equivalence of these coordinate sets. This is the change of traced coordinates used in [ Ope26b , Section 8, lines 520–549 ] .
For a bipartite density operator \(\rho \in M_{d_A}(\mathbb {C})\otimes M_{d_B}(\mathbb {C})\), its operator-Schmidt rank is the least integer \(r\) for which there are matrices \(A_t\in M_{d_A}(\mathbb {C})\) and \(B_t\in M_{d_B}(\mathbb {C})\) satisfying
No Hermiticity or positivity condition is imposed on the factors. This is the definition in [ DlCDN19 , Equation (1) ] ; the same formula defines the rank of an arbitrary complex bipartite matrix.
For \(\rho \succeq 0\) on \(\mathbb {C}^T\), the canonical purification is the vector in \(\mathbb {C}^T\otimes \mathbb {C}^T\) with coefficient matrix \(\sqrt\rho \). Its reduced state is \(\rho \) and its squared norm is \(\operatorname{tr}\rho \), so it is a possibly unnormalized purification of \(\rho \), and a purification in the sense of Definition 1.2.1 when \(\rho \) is a density operator. For \(s\in \mathbb {C}^T\otimes \mathbb {C}^{B_T}\) and \(s'\in \mathbb {C}^E\otimes \mathbb {C}^{B_E}\), write \(s\otimes s'\) for their product regrouped in \((\mathbb {C}^T\otimes \mathbb {C}^E)\otimes (\mathbb {C}^{B_T}\otimes \mathbb {C}^{B_E})\). Its reduced state on \(\mathbb {C}^T\otimes \mathbb {C}^E\) is the tensor product of the reduced states of \(s\) and \(s'\).
The Choi matrix of a linear map \(T:M_{d}(\mathbb {C})\to M_{d'}(\mathbb {C})\) is
an operator on \(\mathbb {C}^{d'}\otimes \mathbb {C}^{d}\). This is the correspondence of [ Wol12 , Proposition 2.1 ] .
Given a bipartite coordinate decomposition \(A\simeq Q\times T\), apply this decomposition in each of \(m\) copies and collect the two families:
The order of the copies is the same in both families.
The set of density matrices in \(M_{D}(\mathbb {C})\) is
For real \(a,b\) and initial real weights \(r_i\), define
When \(r_i\ge 0\) are squared input amplitudes, \(x\) is a diagonal density, and \(b{\gt}0\), \(F(x)\) is the squared norm after applying the filter \((x+bI)^{-a/2}\). The quotient is defined to be zero when \(F(x)=0\).
On the original doubled space \(\mathcal H\otimes \mathcal H\), define \(\Psi =\Omega \otimes \Omega \) and \(\mathbb H=H\otimes I+I\otimes H\). In coordinates, \(\Psi _{(i,j)}=\Omega _i\Omega _j\).
Let \(d_A{\gt}0\) and let \(\rho _{BC}\) be positive semidefinite. Define
Under the canonical reassociation from \(A\times (B\times C)\) to \((A\times B)\times C\), the right partial trace removes \(C\).
Let \(\rho _A\) and \(\rho _{BC}\) be positive semidefinite, and define
We use the canonical reassociation from \(A\times (B\times C)\) to \((A\times B)\times C\), so that the right partial trace removes \(C\).
Let \(V\) be a finite set of sites with finite local Hilbert spaces, and let \(\psi \in \bigotimes _{v\in V}\mathcal H_v\). For a region \(X\subseteq V\), let \(\rho _X=\operatorname {tr}_{X^c}|\psi \rangle \langle \psi |\). Given a set \(E\) of its eigenvalue indices, let \(P_E\) be the selected spectral projection and let \(z=\operatorname {tr}(P_E\rho _X)\). If \(z{\gt}0\), the global selected vector is
expressed in the original product basis. This vector is fixed by \(X\) and \(E\).
If \(P_A\) is the support projection of \(\rho _A\), define
Let \(\rho \) be Hermitian, with an orthonormal eigenbasis \((u_i)_i\) and real eigenvalues \((p_i)_i\). For a finite set \(E\) of eigenvalue indices, define
With the convention \(0^{-1}=0\), the normalized restriction at zero mass is the zero matrix.
Let \(\psi \in \mathcal H_A\otimes \mathcal H_B\) and let \(\rho _A=\operatorname {tr}_B|\psi \rangle \langle \psi |\). For a set \(E\) of marginal eigenvalue indices with positive mass \(z\), let \(P_E\) be the selected spectral projection. The normalized typical truncation is
For \(\rho ,\sigma \in M_{D}(\mathbb {C})\), put \(\widehat D(\rho \Vert \sigma ) =D(\rho \Vert \sigma )\) when \(\ker \sigma \subseteq \ker \rho \), and \(\widehat D(\rho \Vert \sigma )=+\infty \) otherwise. This is the usual infinite value when the support condition fails [ Ope26a , Section 2 ] .
For \(t{\gt}0\), set \(h(t)=-t\log t\), and set \(h(0)=0\). The entropy of a probability distribution \(a=(a_z)_{z\in Z}\) on a finite set is \(H(a)=\sum _{z\in Z}h(a_z)\). For a joint probability distribution \(P\) with row and column marginals \(p\) and \(q\), put
Let \(X\) and \(Y\) be finite sets. A matrix \(P=(P_{x,y})_{x\in X,y\in Y}\) is a joint probability distribution if \(P_{x,y}\geq 0\) for every \(x\in X\) and \(y\in Y\), and
Its row and column marginals are respectively
For a vector \(\psi \in \mathbb C^{E_\Lambda }\), identify its coordinates with a coefficient matrix \(M_R\) indexed by \(E_R\times E_{R^c}\). Define \(\rho _R=M_RM_R^\dagger \) and \(S_\psi (R)=S(\rho _R)\). For arbitrary \(R,T\), define the entropy combination \(I_\psi (R:T)=S_\psi (R)+S_\psi (T)-S_\psi (R\cup T)\). If \(\| \psi \| =1\), each \(\rho _R\) has trace one. For disjoint \(R,T\), the entropy combination is the quantum mutual information of the reduced state on \(R\cup T\).
Restricting a configuration to \(T,E,U\) and enumerating the first two bases gives a bijection \(E_\Lambda \simeq (\{ 1,\ldots ,d_T\} \times \{ 1,\ldots ,d_E\} )\times E_U\). Write \(\widetilde\psi \) for the same vector in these coordinates.
Let \(Q,Y,V,C,R\) be coordinate sets and let \(m\geq 0\). A configuration \(x\) assigns one coordinate in each of these five sets to each copy \(j\). The equivalence \(e_m\) groups these coordinates as
Thus its range is
The inverse places the five coordinates back in the same copy. This includes \(m=0\).
Regroup the good-copy factors, with their fixed common enumeration, by
Write \(e\) for this coordinate equivalence. The ordering is the one used for the paired merge estimate in [ Ope26b , Section 8, lines 513–549 ] .
For matrices \(\mathbb H',\mathbb H,W\) on \(\mathcal H\), define \(A_t=e^{it\mathbb H'}We^{-it\mathbb H}\) and, for \(h\ge 0\),
Truncation retains the original Gaussian mass, without division by \(\mu _h([-T,T])\). Write \(M_h\) and \(M_h^T\) when the three matrices are fixed.
For \(h{\gt}0\), define the centered Gaussian density of variance \(h\) by
Write \(\mu _h\) for the corresponding probability measure. At \(h=0\), set \(\mu _0=\delta _0\) and \(g_0(t)=0\) for every \(t\). Thus \(g_0\) is not a density of \(\mu _0\) with respect to Lebesgue measure.
Separate the two auxiliary registers by the coordinate equivalence
Both good registers precede both bad registers. Denote this equivalence by \(e\).
Let \(B\subseteq \{ 1,\ldots ,k\} \), put \(r=|B|\) and \(m=|B^c|=k-r\), and use the chosen finite-set equivalences to enumerate \(B^c\) and \(B\). For a coordinate set \(C\), write
where \(j_g\) and \(j_b\) are the inverse finite-set equivalences, followed by inclusion into the whole copy set. This is an equivalence, including when one of the copy groups is empty. No order-preserving enumeration is required.
A fixed division \([k]\simeq [m]\sqcup [r]\) of the copies induces the coordinate decomposition of the full configuration space into the configurations on the first and second groups. All physical and auxiliary factors use this same division.
A Hayashi Markov decomposition of a tripartite state \(\rho _{ABC}\) consists of a finite direct-sum decomposition
together with a unitary change of basis on \(B\), a probability vector \((p_j)_j\), and density matrices \(\rho _{A B_j^L}\) and \(\rho _{B_j^R C}\) such that, in the adapted basis, the state becomes
The terminology follows Hayashi’s presentation of quantum Markov structure [ Hay06 ] ; the block decomposition used by the MPDO argument is the structure theorem of [ HJPW04 ] .
Let \(A\) be Hermitian, with spectral decomposition \(A=U\operatorname{diag}(\lambda _i)U^\dagger \). Its support projection is
For a finite-dimensional system \(A\), there is a finite family of effects \((M_s)_s\), with \(0\leq M_s\leq \mathbf1_A\), whose complex linear span is the full matrix algebra on \(A\). One member is the identity. For an operator \(X\) on \(A\otimes B\), define its conditional slice by
The family may be chosen from the four rank-one effects occurring in the polarization identity, scaled so that every member is bounded by the identity.
For a linear map \(\Psi _B\) and a bipartite matrix \(\rho _{AB}\), define
where \(\Sigma \) denotes the canonical exchange of the two tensor factors.
A linear map \(\mathcal S\) between matrix algebras is completely positive in rectangular Kraus form if there are finitely many operators \(A_i:H\to K\) such that
No trace-preservation normalization is imposed.
A linear map \(\mathcal{S}\) between matrix algebras is trace-preserving completely positive if it has a Kraus form \(\mathcal{S}(X)=\sum _i A_iXA_i^\dagger \) with \(\sum _i A_i^\dagger A_i=I\). The Kraus operators may be rectangular, so the input and output dimensions need not agree.
Let \(V:\mathbb {C}^k\to \mathbb {C}^D\) be an isometry, so that \(V^\dagger V=\mathbb {1}_k\). Define \(\iota _V:M_{k}(\mathbb {C})\to M_{D}(\mathbb {C})\) by
The map \(\iota _V\) is complex-linear, multiplicative, and \(*\)-preserving. In general it is not unital: \(\iota _V(\mathbb {1}_k)=VV^\dagger \) is the projection onto the range of \(V\).
Assume in addition that the common average \(\bar\rho \) of Definition 13.8.57 is positive definite. Hayden–Jozsa–Petz–Winter instead reduce to this case by shrinking to the joint support of \(\rho _1,\ldots ,\rho _K\); that reduction is not re-derived here. By Lemma 13.8.58, \(\bar\rho \) is a positive definite fixed point of every \(F\in \mathbf F\), so Theorem 10.2.10 makes the fixed-point set of each adjoint map,
a \(*\)-subalgebra of \(M_{D}(\mathbb {C})\). The common invariant algebra is
and \(X\in A_0\) if and only if \(F^*(X)=X\) for every \(F\in \mathbf F\).
Let \(\rho _1,\ldots ,\rho _K\) be density matrices in \(M_{D}(\mathbb {C})\), \(K\ge 1\). A trace-preserving completely positive Kraus family \(F\) preserves \(\rho _1,\ldots ,\rho _K\) if \(F\rho _k=\rho _k\) for every \(k\). Write
for the set of such operations – non-empty since the identity operation belongs to it – and
for their common average.
Let \(\rho \) be a matrix on a finite-dimensional space \(B\). The state-preparation map from matrices on \(A\) to matrices on \(A\otimes B\) is
This is the elementary preparation operation used in the maps \(\mathcal T_1\) and \(\mathcal S_1\) of [ CPGSV16 , Appendix C.2, lines 1527–1533 and 1551–1555 ] . It is relocated here from the MPDO renormalization chapter; its Kraus-action and conditional-expectation consequences for the density-operator setting appear in Section 1.16 below.
Let \(E_{k\ell }\) denote the matrix unit with its only nonzero entry in row \(k\) and column \(\ell \). The transfer matrix \(\widehat T\) is the matrix indexed by pairs of bond indices with entries
Equivalently, this is the matrix of \(T\) under the column-stacking identification \(M_D(\mathbb C)\cong \mathbb C^{D^2}\): the matrix-units special case of Definition 3.19.2.
For the \(QC\) pair set \(D_C=F_Q+F_C-F_{QC}\), and for the \(VR\) pair set \(D_R=F_V+F_R-F_{VR}\). Each operator is Hermitian. On the common space write \(\widehat D_C=D_C\otimes I_{VR}\) and \(\widehat D_R=I_{QC}\otimes D_R\).
Let \(X \in M_{d \cdot d'}(\mathbb {C})\) be a bipartite matrix indexed by \((\{ 0,\ldots ,d-1\} \times \{ 0,\ldots ,d'-1\} )^2\). The left partial trace \(\operatorname{tr}_A(X)\) and right partial trace \(\operatorname{tr}_B(X)\) are the \(d' \times d'\) and \(d \times d\) matrices defined by
For an operator \(\rho \) on \(H_L\otimes H_R\), define \((\operatorname{tr}_L\rho )_{r,s}:=\sum _l\rho _{(l,r),(l,s)}\).
Let \(\sigma \) be positive semidefinite on \(H_L\otimes H_R\), and set \(\tau =\operatorname{tr}_R\sigma \). The Petz transpose formula on the support of \(\tau \) is
This is the support formula of [ HJPW04 , Theorem 3, equation (8) ] . It is not asserted to be trace preserving on operators outside the support of \(\tau \).
The map \(T_\phi \) is the projection onto the peripheral subspace along the non-peripheral subspace. The phase-weighted peripheral map is Wolf’s asymptotic dynamics \(T_\varphi =T\circ T_\phi \).
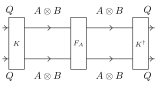
For two registers \(A,B\), the partial swap \(F_A\) exchanges the \(A\) factors of two replicas:
For a linear map \(V:\mathcal H_Q\to \mathcal H_A\otimes \mathcal H_B\), put \(K=V\otimes V\) and define the compression
The contraction below is read from left to right: first \(K\), then \(F_A\), then \(K^\dagger \). Each external leg is an original copy of \(Q\); each internal leg bundles one copy of \(A\otimes B\).
The regrouping \((r,c,x,y)\mapsto (r,x,c,y)\) identifies \((\mathcal H_R\otimes \mathcal H_C)\otimes (\mathcal H_X\otimes \mathcal H_Y)\) with \((\mathcal H_R\otimes \mathcal H_X)\otimes (\mathcal H_C\otimes \mathcal H_Y)\). For a vector \(\Omega \) on \(RCQ\), write its two replicas with both reference registers before both buffer registers:
Thus \(\Psi \) is the regrouped \(\Omega ^{\otimes 2}\) and \(\Phi =F_R\Psi \); both copies of \(C\) and \(Q\) retain their coordinates.
The density on physical factor \(j\) is the partial trace of \(|\Omega \rangle \langle \Omega |\) in the coordinates \(e_j\). Equivalently, its entries are
where \(y\) ranges over the configurations of the other two factors.
Let the physical and auxiliary coordinate sets be finite, and let \(m\geq 0\) be the number of good copies. Write the original physical factors as \(H_0=H_Q\), \(H_1=H_Y\) and \(H_2=H_V\). For \(j\in \{ 0,1,2\} \), let
be the coordinate identification that places the \(j\)th factor first and retains the original labels on its complement. On \(m\) copies, let \(c_j\) apply this identification to every copy and collect the copies of the two factors. This is the regional decomposition used in [ Ope26b , Section 8, lines 550–560 ] .
A linear map \(T : M_{D}(\mathbb {C}) \to M_{D'}(\mathbb {C})\) between matrix algebras of possibly different dimensions is positive if \(T(X) \ge 0\) whenever \(X \ge 0\), where \(X \ge 0\) means that \(X\) is positive semidefinite. For \(D' = D\) this is the notion of Definition 2.1.1.
For a complex-linear map \(P:\mathcal M\to \mathcal M\) and matrices \(H,B\in \mathcal M\), define, for every \(t\in \mathbb {R}\),
In particular, \(G_{P,H,B}(0)=P(B)\).
For matrices \(\rho ,\sigma \in M_{D}(\mathbb {C})\), define the trace-log expression
On the physical domain where \(\rho \) is a density matrix and \(\sigma \) is positive definite, this is the Umegaki relative entropy.
For \(a\le b\), set \(F_{a:b}=E_a\circ \cdots \circ E_{b-1}\), with \(F_{a:a}=\mathbb {1}_{M_{D_a}(\mathbb {C})}\). For successive rectangular Kraus families \(A_i^{s_i}\), set \(A^{\boldsymbol s}=A_a^{s_a}\cdots A_{b-1}^{s_{b-1}}\).
For a complex-linear map \(\mathcal L:M_{d}(\mathbb {C})\to M_{e}(\mathbb {C})\), its unnormalized rectangular Choi matrix \(J(\mathcal L)\in M_{de}(\mathbb {C})\) is the reshaping
When \(d=e\), this is \(d\) times the normalized Choi matrix convention in [ Wol12 , Proposition 2.1 ] .
Let \(\mathcal H_{\mathrm{phys}}\) be a finite tensor product of local coordinate spaces, and fix auxiliary coordinate spaces \(C,R\). An added site is distinguished from the original sites; applying this construction twice retains two distinct auxiliary coordinates. For disjoint physical regions \(Q,Y\), write \(F=(Q\cup Y)^c\). Restriction of configurations gives the equivalence
The five coordinate factors, in order, are \(Q,Y,F,C,R\).
On \(k\) copies, let \(G_k\) extract the original physical copies and the two original auxiliary registers from the full configuration. For any physical coordinate equivalence \(e\), let \(E_k(e)\) apply \(e\) independently to those physical copies and act identically on both auxiliary registers. Finally let \(F_k\) be the five-factor regrouping into these three registers. The actual regional equivalence is
It maps the original full configurations to the grouped five-factor configurations. The auxiliary coordinate sets and their order are unchanged. Empty regions and zero copies are included. These are the coordinate identifications in [ Ope26b , Section 8, lines 20–37 and 80–110 ] .
Let \(A,C,D\) be finite coordinate sets, let \(\Omega \in \mathbb C^A\), and let \(v\in \mathbb C^{A^k}\otimes \mathbb C^{C^k}\otimes \mathbb C^{D^k}\). Write \(R_B\) for the literal excitation operator, with factors \(I-|\Omega \rangle \langle \Omega |\) on \(B\) and \(|\Omega \rangle \langle \Omega |\) on its complement, and set \(w=(R_B\otimes I)v\). First form the whole auxiliary marginal \(\rho _{CD}=\operatorname {Tr}_{A^k}|w\rangle \langle w|\). Regroup its coordinates using
The actual good auxiliary marginal is the unnormalized matrix
Thus every physical copy, the bad auxiliary copies and every exterior copy are traced out; the good auxiliary copies are retained.
Let all five coordinate sets be finite. Put \(A=Q\times (Y\times V)\), let \(\Omega \in \mathbb C^A\), and let
be arbitrary. For \(B\subseteq \{ 0,\ldots ,k-1\} \), put \(G=B^c\), \(m=|G|\) and \(b=|B|\). Form the actual component \(w=(R_B\otimes I)u\). Use the same chosen enumeration of \(G\) in all five factors and the chosen enumeration of \(B\) in each auxiliary factor.
For a retained configuration \(x\), write \(e_m(x)=(a,(c,r))\). A discarded configuration consists of a physical assignment \(d\in A^B\) and auxiliary assignments \(c'\in C^b\), \(r'\in R^b\). Reconstruct the original physical register by placing \(a\) on \(G\) and \(d\) on \(B\). Reconstruct the two auxiliary registers by placing \((c,r)\) on \(G\) and \((c',r')\) on \(B\). Let \(f_B(x,(d,c',r'))\) be the value of \(w\) at these reconstructed coordinates. Define
This is the actual unnormalized rank-one partial trace. Only the bad physical and auxiliary copies are discarded. No condition on \(\Omega \) or \(u\) is imposed in the definition.
Regroup the same component \(w\) into retained and discarded factors:
The common density \(\Gamma _B(u)\) is \(\operatorname {Tr}_{\mathcal H_{\mathrm{tr}}}|w\rangle \langle w|\). It retains the four exterior good regions and is unnormalized. The discarded factors include the good middle copies and the middle coordinates within the bad physical copies, so every middle physical coordinate is traced.
Regroup \(w\) as a vector on \(\mathcal H_{\mathrm{ret}}\otimes \mathcal H_{\mathrm{tr}}\), where
The joint marginal \(\rho _{Q_GC_G}(w)\) is the partial trace of \(|w\rangle \langle w|\) over the second factor. Thus it retains the good physical \(Q\) coordinates and the good auxiliary \(C\) coordinates of the same component, without normalization.
For any \(\Omega \in \mathbb C^A\) and \(u\in \mathbb C^{A^k}\otimes \mathcal K\), define a vector \(w_B\in \mathbb C^{A^B}\otimes \mathcal K\) by
No normalization of \(u\) or \(\Omega \) is required for this definition.
For a physical vector \(\Omega \), let \(N_\Omega =\sum _{i=0}^{k-1}(I-|\Omega \rangle \langle \Omega |)_i\). Fix the two original auxiliary labels \(\ell _C,\ell _R\) and \(\tau \in \mathbb R\). Write \(E_C,E_R\) for their whole-copy label projections, and set
where \(S\) is the average of the simultaneous permutation matrices. Here the identity operators act on the corresponding copy registers. This is the low-defect construction in [ Ope26b , Section 8, (comparator:defect-mass) ] .
Let \(\mathcal H=\mathbb C^A\), let \(H\) be an operator on \(\mathcal H\), and let \(\Omega \in \mathcal H\). For \(k\ge 0\), define
For \(k{\gt}0\), write \(\overline H=k^{-1}H_\Sigma \).
Let \(u_d=d^{-1/2}\sum _{i=0}^{d-1}|i,i\rangle \) be the uniform auxiliary pair for \(d{\gt}0\), and set \(u_0=0\). For \(k=0\), use the empty tensor product. Regroup its literal tensor power into the two auxiliary systems and write it as \(U_k\). For a central label projector \(\Pi _\lambda \) on \((\mathbb C^d)^{\otimes k}\), define
All products and projections here act on the actual finite copy spaces.
For a physical vector \(\Omega \in X\otimes Y\otimes Z\), put
The physical and ancillary factors are reassociated in the stated coordinate order. Write \(M_X=\operatorname {tr}_Y((I_X\otimes T)\rho _{XY}Q)\).
For matrices \(Q\) on \(X\otimes Y\) and \(T\) on \(Y\), define
The second sum in (392) includes every basis vector, including those with zero eigenvalue. These are the operators in the amplification argument of [ Ope26b ] .
For every physical vector \(\Omega \), define
Write \(\phi =\mathcal R_X\Omega \). Substitution of the source’s Schmidt expansion into this definition gives its swapped-state expression. The identities below do not require that expansion as a hypothesis, nor do they require \(\Omega \) to be normalized or \(p\) to be its marginal spectrum. In the source application \(p\) is the nonnegative marginal spectrum; its zero eigenvalues contribute zero to \(\eta \).
- Entropy.restoringPhysicalGrouping
- Entropy.restoringPhysicalLift
- Entropy.restoringGlobal
- Entropy.restoringColumnGlobal
- Entropy.restoringCopy
- Entropy.restoringInitial
- Entropy.restoringRestored
- Entropy.restoringSelectedProjection
- Entropy.restoringSelectedProjection_isHermitian
- Entropy.restoringSelectedProjection_mul_self
For \(\rho ,\sigma \succeq 0\), the root fidelity is
where \(\sqrt{\, \cdot \, }\) is the positive square root. It is nonnegative. This is the convention of [ Ope26a , Section 2 ] .
For square complex matrices \(\rho \) and \(\omega \) and every \(\alpha \in \mathbb {R}\), set
Real powers are defined by continuous functional calculus, with negative powers equal to zero on the zero eigenspace. Thus \(\widetilde Q_\alpha \) is total even when \(\alpha =0\) or \(\omega \) is singular. For \(\alpha {\gt}1\), on positive semidefinite inputs satisfying \(\ker \omega \subseteq \ker \rho \), this convention gives the finite sandwiched Rényi trace term. In this regime, if the support inclusion fails, the totalized value remains finite but is not the divergence trace term.
For square matrices \(\rho \) and \(\omega \) of the same size, define
The negative power is defined by functional calculus and vanishes on the kernel of \(\omega \). On trace-one positive semidefinite matrices satisfying \(\ker \omega \subseteq \ker \rho \), its logarithm is the order-two sandwiched Rényi divergence [ MLDS\(^{+}\)13 , Definition 2 ] .
For a matrix \(A\in M_{D}(\mathbb {C})\), the singular values \(s_0(A),s_1(A),\ldots \) form a finitely supported family: only finitely many are nonzero. The Schatten one-norm of \(A\) is their sum, that is, the sum of the finitely many nonzero singular values:
This is the \(p=1\) case of the Schatten \(p\)-norm [ Wol12 , Chapter 8, Section 8.1 ] . The equivalent closed formula \(\lVert A\rVert _1=\sum _{i=0}^{D-1}s_i(A)\), summing over all \(D\) singular values including trailing zeros, is part of Theorem 13.1.4.
A vector \(\psi \in \mathbb {C}^{D}\otimes \mathbb {C}^{k}\) is identified with its coefficient matrix \(C_\psi \in M_{D,k}(\mathbb {C})(\mathbb {C})\). Its Schmidt rank is \(\operatorname{SR}(\psi )=\operatorname{rank}(C_\psi )\). We write \(\operatorname{SR}(\psi )\le r\) for the corresponding bounded-rank condition.
Let \(\tau =\sum _i\lambda _i|i\rangle \! \langle i|\) be positive semidefinite. Its inverse square root on the support is
For a positive semidefinite matrix \(\rho \ge 0\), the support projection \(P\) is the orthogonal projection onto the range of \(\rho \). Via the spectral decomposition \(\rho =U\operatorname{diag}(\lambda _1,\ldots ,\lambda _D)U^\dagger \), it is
where \(\mathbf{1}_{\lambda _j{\gt}0}\) is \(1\) if \(\lambda _j{\gt}0\) and \(0\) otherwise.
For \(T:M_{D}(\mathbb {C})\to M_{D}(\mathbb {C})\), let \(T_\phi \) be its peripheral spectral projection and define
This is Wolf’s notation in [ Wol12 , Chapter 8, Proposition “Convergence towards asymptotic states”, Eq. (8.112) ] .
For any matrix \(Y\in M_{D'}(\mathbb {C})\), define \(T'_Y:M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) by
A linear map \(T : M_{D}(\mathbb {C}) \to M_{D'}(\mathbb {C})\) between matrix algebras of possibly different dimensions is trace-preserving if \(\operatorname{tr}(T(X)) = \operatorname{tr}(X)\) for all \(X\). For \(D' = D\) this is the notion of Definition 2.1.3.
For a tripartite matrix \(\rho _{ABC}\) on \(\mathbb {C}^{d_A} \otimes \mathbb {C}^{d_B} \otimes \mathbb {C}^{d_C}\), the partial trace over \(A\) is
Define
On \((\mathcal H_A\otimes \mathcal H_C)\otimes (\mathcal H_R\otimes \mathcal H_B)\), define \(\mathrm{pre}_{acrb}=\Omega _{ab}u_{cr}\) and \(\mathrm{post}=\beta \otimes \chi \).
For a Hermitian matrix \(\rho \in M_{D}(\mathbb {C})\) with eigenvalues \(\lambda _0,\ldots ,\lambda _{D-1}\), the von Neumann entropy is
where \(0\log 0:=0\).
For \(A\in M_{D}(\mathbb {C})\) and a complex-linear map \(S:M_{D}(\mathbb {C})\to M_{D}(\mathbb {C})\),
If \(\psi \) and \(\phi \) are orthogonal unit vectors, then \(\lVert |\psi \rangle \! \langle \psi |-|\phi \rangle \! \langle \phi |\rVert _2=\sqrt2\). Consequently the orthogonal-pure-state supremum for \(S\) is at most \(\sqrt D\, \lVert S\rVert _{2\to 2}\sqrt2\). These are precisely the estimates in Wolf Equations (8.115)–(8.116).
Let \(A \in M_{m \times n}(\mathbb {C})\) and \(B \in M_{n \times m}(\mathbb {C})\). Then the charpoly-root entropy sum is invariant under the cyclic swap \(AB \mapsto BA\):
with roots counted with algebraic multiplicity.
For arbitrary \(Y\in M_{D'}(\mathbb {C})\), the rectangular (output-factor-first) Choi matrix of \(T'_Y\) is
See [ Wol12 , Chapter 8, Eq. (8.86) ] .
For states \(\tau _j\) on \(D\otimes E\) and probability weights \(p_j\),
The von Neumann entropy of a Hermitian matrix is the \(-x\log x\) sum over the real parts of the roots of its characteristic polynomial \(\chi _\rho \):
For any orthogonal projection \(P\) on \(\mathcal H_A\), put \(\psi _P=(P\otimes I_B)\psi \) and \(\psi _{I-P}=((I_A-P)\otimes I_B)\psi \). Then
A map in rectangular Kraus form sends positive semidefinite matrices to positive semidefinite matrices. Every trace-preserving completely positive Kraus map is a completely positive Kraus map.
Let \(\rho \) be a positive semidefinite operator on \(A \otimes R\) with reduced state \(\rho _R = \operatorname{tr}_A \rho \). Then the singular reference \((\mathbb {1}_A / d_A) \otimes \rho _R\) satisfies the support condition \(\ker ((\mathbb {1}_A / d_A) \otimes \rho _R) \subseteq \ker \rho \).
The label projectors are mutually orthogonal orthogonal projections with sum the identity, and they commute with every operator that commutes with all permutation operators. Every label observable is self-adjoint.
Let \(\tau \) be positive semidefinite on \(\mathcal H_S\), let \(X\) be a matrix on \(\mathcal H_S\), and let \(\overline\tau =\tau \otimes d_C^{-1}\mathbf1_C\). Then
The natural lifts from \(AB\) and \(BC\) to \(ABC\) preserve products and adjoints; the left lift preserves finite sums and complex scalar multiplication, and the right lift preserves finite sums. The right lift of \(U_B\otimes \mathbb {1}_C\) is \(\mathbb {1}_A\otimes U_B\otimes \mathbb {1}_C\). If \(X_{AB}\) is supported on a middle projection \(P\) from the right, \(Y_{BC}\) is supported on a middle projection \(Q\) from the left, and \(PQ=0\), then their overlapping lifts have zero product. Finally, positivity of either lifted operator implies positivity of the corresponding local operator whenever the complementary factor is nonempty.
- Matrix.leftOverlappingLift_mul
- Matrix.rightOverlappingLift_mul
- Matrix.leftOverlappingLift_star
- Matrix.rightOverlappingLift_star
- Matrix.rightOverlappingLift_kronecker_one
- Matrix.overlappingLifts_mul_eq_zero_of_middle_mul_eq_zero
- Matrix.leftOverlappingLift_sum
- Matrix.leftOverlappingLift_smul
- Matrix.rightOverlappingLift_sum
- Matrix.posSemidef_of_leftOverlappingLift_posSemidef
- Matrix.posSemidef_of_rightOverlappingLift_posSemidef
Let \(e_L:H_L\to H_L'\) and \(e_R:H_R\to H_R'\) be bijections, and write \(Z^{e_L\otimes e_R}\) for the corresponding simultaneous relabelling of the rows and columns of \(Z\). Then
Let \(A:H_A\to K_A\) and \(B:H_B\to K_B\) be linear maps between finite-dimensional complex spaces, and let \(X\) be an operator on \(H_A\otimes H_B\). If \(B^\dagger B=1\), then
If \(A^\dagger A=1\), then, symmetrically,
The identities include zero-dimensional spaces.
Let \(P_\tau \) be the orthogonal projector onto the support of \(\tau =\operatorname{tr}_R\sigma \). Then, for every matrix \(X\),
Let \(A\in M_{D}(\mathbb {C})\) be Hermitian with positive part \(A^+\). There is a matrix \(\Pi \) with \(0\leq \Pi \leq \mathbb {1}\), \(\Pi ^2=\Pi \), and \(\Pi A=A^+\), namely the orthogonal projection onto the support space of \(A^+\).
Let \(T:M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) be a trace-preserving positive linear map and let \(H\in M_{D}(\mathbb {C})\) be Hermitian, with Jordan decompositions \(H=P_+-P_-\) and \(T(H)=Q_+-Q_-\). Then \(\operatorname{tr}[Q_+]\leq \operatorname{tr}[P_+]\).
Let \(S,T\) be positive semidefinite matrices and let \(x\) be a vector. If \((t\mathbf1+S)^{-1}x=(t\mathbf1+T)^{-1}x\) for every \(t{\gt}0\), then \(\sqrt S\, x=\sqrt T\, x\). More generally, for any fixed matrix \(Q\), if \(Q(t\mathbf1+S)^{-1}x=Q(t\mathbf1+T)^{-1}x\) for every \(t{\gt}0\), then \(Q\sqrt S\, x=Q\sqrt T\, x\).
In particular, for positive definite \(A,B\) and every \(t{\gt}0\), put \(\Delta _{A,B}=A\otimes (B^{-1})^{\mathsf T}\). The source-\(B\) left–right resolvent satisfies
and
These are the positive-square-root specializations of the passage from relative modular resolvents to analytic functions of the relative modular operator in Jenčová–Ruskai, arXiv:0903.2895v4, lines 658–680.
Let \(p=(p_z)_{z\in Z}\) be a probability distribution on a finite set \(Z\). Define \(h(t)=-t\log t\) for \(t{\gt}0\) and \(h(0)=0\). Then
Let \(\omega _{XY}\) be positive semidefinite. Then
Equivalently, \(\omega _{XY}\) is supported on \(\operatorname {supp}\omega _X\otimes \operatorname {supp}\omega _Y\).
Let \(X,C\in M_{D}(\mathbb {C})\) with \(X\geq 0\). If \(C\geq 0\), then \(\operatorname{tr}[CX]\geq 0\); if \(C\leq \mathbb {1}\), then \(\operatorname{tr}[CX]\leq \operatorname{tr}[X]\).
For matrices \(\rho ,\sigma \in M_{D}(\mathbb {C})\),
Let \(\rho \) be a density matrix on \(A \otimes R\) with reduced state \(\rho _R = \operatorname{tr}_A \rho \), and suppose the support condition \(\ker ((\mathbb {1}_A / d_A) \otimes \rho _R) \subseteq \ker \rho \) holds. Then
Let \(a,b{\gt}0\). Then the function
is integrable on \((0,\infty )\), and
This is the scalar normalization \((\mathrm{intspec})\) in Jenčová–Ruskai, arXiv:0903.2895v4, §2.1, lines 406–413.
For Hermitian matrices \(\rho ,\sigma \) on a finite index set and any bijection \(e\) from that set onto another finite set,
Let \(T\) be an orthogonal projection and \(K=I_X\otimes T\). For every matrix \(A\),
If \(A\ge 0\), then \(\operatorname {tr}_Y(KAK)\le \operatorname {tr}_Y A\).
For arbitrary matrices \(A\) on \(X\otimes Y\) and \(T\) on \(Y\),
If \(A\le B\), then \(\operatorname {tr}_Y A\le \operatorname {tr}_Y B\).
For matrices \(M\) and \(P\), column-stacking vectorization satisfies
Let \(\zeta \) be a primitive \(d\)-th root of unity and let \(i,j\) range over the residues modulo \(d\). Then
Let \(T:M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) be a positive linear map with \(\operatorname{tr}[T(\rho )] = c\, \operatorname{tr}[\rho ]\) for some nonnegative real \(c\) and all \(\rho \in M_{D}(\mathbb {C})\). Then for all Hermitian \(H\in M_{D}(\mathbb {C})\), \(\operatorname{tr}[(TH)^+]\leq c\cdot \operatorname{tr}[H^+]\). Generalizes Lemma 13.1.18 from the trace-preserving case \(c=1\).
If \(P_\tau \) is the orthogonal projector onto the support of a positive semidefinite matrix \(\tau \), then
Let \(\tau \) be positive semidefinite and let \(c{\gt}0\). Then
For every finite-dimensional auxiliary space \(\mathcal H_R\),
The corresponding identity for an auxiliary left factor is
Consequently, for \(d_R{\gt}0\),
If \(P_\tau \) is the orthogonal projector onto the support of a positive semidefinite matrix \(\tau \), then
Let \(A,B\) be positive semidefinite, let \(t{\gt}0\), set \(B^+=(B^{-1/2}_{\mathrm{supp}})^2\), and let \(P_B\) be the support projection of \(B\). Then
Let \(A\) and \(B\) be positive semidefinite, and write \(B^+=(B^{-1/2}_{\mathrm{supp}})^2\). Then
Let \(A,B,C,D\) be positive semidefinite matrices. Write \(B^+=(B^{-1/2}_{\mathrm{supp}})^2\) and \(D^+=(D^{-1/2}_{\mathrm{supp}})^2\), and let \(P_B\) be the orthogonal projection onto \((\ker B)^\perp \). If, for every \(t{\gt}0\),
where the inverses act as relative-modular superoperators on matrices, then
This is the square-root specialization of the support functional-calculus passage in Jenčová–Ruskai, arXiv:0903.2895v4, lines 788–793. The projection \(P_B\) is essential: the source gives the common generalized resolvents only after restriction to \((\ker B)^\perp \). Deriving this restricted equality requires the preceding singular equality argument and its kernel hypotheses; these are supplied for finite families by Theorem 13.8.35.
Let \(I\) be a finite nonempty set. For each \(i\in I\), let \(S_i\) be a positive-semidefinite matrix, let \(P_i\) be its support projection, and let \(b_i\) lie in its support. Write
Assume also that \(b\) lies in the support of \(S\), and put \(x=Gb\). Then
In particular,
Jenčová and Ruskai give the positive-definite residual expansion in equations \((\mathrm{Mj})\) and \((\mathrm{eq:Schz1})\) of the Appendix to arXiv:0903.2895v4. The support assumptions make the same expansion valid for the generalized inverses of the \(S_i\) and of \(S\).
Let \(I\) be a finite nonempty set. For each \(i\in I\), let \(A_i\) and \(B_i\) be positive-semidefinite matrices of the same size. For \(t{\gt}0\), write
Then
No kernel inclusion between \(A_i\) and \(B_i\) is required. This lemma is a positive-semidefinite support-domain extension of the positive-definite calculation in equations \((\mathrm{Mj})\), \((\mathrm{eq:Schz1})\), and \((\mathrm{eq:Schwzt})\) at lines 1313–1343 of Jenčová–Ruskai, arXiv:0903.2895v4; their generalized-inverse notation is given at lines 254–262. The paper does not state this extension. Its later singular equality theorem at lines 761–785 assumes \(\ker B_i\subseteq \ker A_i\) and is not asserted here. The subsequent singular entropy-equality passage is recorded in the TNLean paper-gap note [ con26r ] .
If \(\rho ,\sigma \) are Hermitian with equal trace, then the positive and negative parts of \(\rho -\sigma \) both have trace \(\delta (\rho ,\sigma )\). For states, \(\delta (\rho ,\sigma )\le 1\), and the partial trace over a tensor factor does not increase \(\delta \).
If \(\rho _{ABC}\) is Hermitian, then \(\operatorname{tr}_A(\rho _{ABC})\), \(\operatorname{tr}_C(\rho _{ABC})\), and \(\operatorname{tr}_{AC}(\rho _{ABC})\) are all Hermitian. The same holds for bipartite partial traces \(\operatorname{tr}_A(\rho _{AB})\) and \(\operatorname{tr}_B(\rho _{AB})\).
Let \(T_\varphi :=T\circ T_\phi =T_\phi \circ T\) be Wolf’s asymptotic dynamics. For every matrix \(\rho \), every \(n\geq 0\), and every \(n{\gt}0\) in the second equality,
These are the numerator identities used in [ Wol12 , Chapter 8, Eq. (8.114) ] . They follow from \(T_\phi T=TT_\phi =T_\varphi =T_\varphi T_\phi \); the positive-iterate condition records that the zeroth power of \(T_\varphi \) is the identity.
Let \(T:M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) be a complex-linear map. Then
The left supremum is over distinct density matrices in \(M_{D}(\mathbb {C})\), and the right supremum is over orthogonal unit vectors in \(\mathbb {C}^D\). No positivity or trace-preservation assumption is imposed on \(T\). This is [ Wol12 , Chapter 8, Lemma 8.3, Eq. (8.81) ] .
Let \(S:M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) be complex-linear and let \(\rho _1\neq \rho _2\) be density matrices. Then
This is the pointwise inequality from Wolf Lemma 8.3 used in Equation (8.115).
For every \(A\in M_{D}(\mathbb {C})\), the trace norm is the sum of the square roots of the eigenvalues of the positive operator \(A^\dagger A\):
Fix a dimension \(d_C\ge 1\) and a primitive \(d_C\)-th root of unity \(\zeta \). For every matrix \(M\) on \(\mathcal{H}_S\otimes \mathbb {C}^{d_C}\), the uniform average of the conjugations by the \(d_C^2\) unitaries \(\mathbb {1}_S\otimes W(a,b)\) on the second factor is the partial trace over that factor tensored with the maximally mixed state \(\mathbb {1}_C/d_C\):
Let \(E\) be the set of indices with \(p_i{\gt}0\) and \(|-\log p_i-S|\le w\), and let \(z=\sum _{i\in E}p_i\). Then \(z\ge 1-\Pr \{ |K-S|{\gt}w\} \), and \(\mathrm e^{-S-w}\le p_i\le \mathrm e^{-S+w}\) for \(i\in E\).
Let \(I\) be a finite nonempty set. For each \(i\in I\), let \(A_i\) and \(B_i\) be positive-semidefinite matrices of the same size satisfying \(\ker B_i\subseteq \ker A_i\). For \(t{\gt}0\), write
Then
The kernel inclusions for the summands imply \(\ker (\sum _i B_i)\subseteq \ker (\sum _i A_i)\). This lemma is the source-\(A\) support-domain extension of the positive-definite residual calculation in equations \((\mathrm{Mj})\), \((\mathrm{eq:Schz1})\), and \((\mathrm{eq:Schwzt})\) at lines 1313–1343 of Jenčová–Ruskai, arXiv:0903.2895v4. The paper does not state this fixed-parameter extension separately. The lemma does not assert that equality of relative entropies makes the defect vanish.
Let \(X\) be a matrix on \(\mathcal H_S\otimes \mathbb C^{d_C}\) and let \(U_g=\mathbf1\otimes W_g\) for the \(d_C^2\) Weyl indices. Then
Let \(T\) be a complex finite-dimensional endomorphism, let \(T_\phi \) be its peripheral spectral projection, and let \(T_\varphi =T T_\phi \) be the phase-weighted peripheral map of Equation (6.13). For every positive integer \(n\),
The restriction \(n{\gt}0\) is essential: at \(n=0\) the first left-hand side is zero, whereas the right-hand side is the identity. In particular, the later condition \(d^2-1\leq n\) does not exclude this failure when \(d=1\).
If the Kraus map is trace-preserving and has a positive definite fixed point \(\rho {\gt}0\) with \(E(\rho )=\rho \), then \(\operatorname{Fix}(E^*)\) is a \(*\)-subalgebra of \(M_{D}(\mathbb {C})\).
The set of doubly stochastic matrices in \(M_d(\mathbb {R})\) is the convex hull of the \(d\times d\) permutation matrices, and its extreme points are exactly the permutation matrices. See [ Wol12 , Chapter 8, Theorem 8.6 ] . This statement concerns only doubly stochastic matrices; the corresponding assertion of Theorem 8.6 for doubly substochastic matrices is not included here.
Let \(A\in M_{k}(\mathbb {C})\) be Hermitian, let \(V:\mathbb {C}^k\to \mathbb {C}^D\) satisfy \(V^\dagger V=\mathbb {1}_k\), and let \(f:\mathbb {R}\to \mathbb {R}\) satisfy \(f(0)=0\). Then
where both sides use the continuous functional calculus on the respective finite spectra.
If \(A\in M_{n}(\mathbb {C})\) is Hermitian and \(f:\mathbb {R}\to \mathbb {R}\), then
In particular,
If \(A\) is positive semidefinite, then for every \(r\in \mathbb {R}\),
These identities include singular matrices and matrices whose index set is empty. They are project-derived rather than statements of CPSV16.
Let \(T:M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) be a trace-preserving, Hermiticity-preserving linear map and \(Y\in M_{D'}(\mathbb {C})\) Hermitian with \(\operatorname{tr}[Y]=1\). For \(\varepsilon \geq 0\), if the rectangular Choi matrix \(\tau (T)\) satisfies
then for all density operators \(\rho _1,\rho _2\in M_{D}(\mathbb {C})\),
See [ Wol12 , Chapter 8, Eq. (8.86) ] .
The map \(T\) is completely positive, in the sense that it admits a Kraus representation \(T(X)=\sum _{j}K_jXK_j^\dagger \) with \(K_j\in M_{d'\times d}(\mathbb {C})\), if and only if \(\tau \geq 0\). This is the complete-positivity clause of [ Wol12 , Proposition 2.1 ] .
Let \(X\) and \(Y\) be finite sets and let \(P=(P_{x,y})_{x\in X,y\in Y}\) be a joint probability distribution. With natural logarithms, \(I(X:Y)_P\leq \log \operatorname{rank}_{\mathbb {R}}P\). Equivalently, with logarithms to base two, \(2^{I(X:Y)_P}\leq \operatorname{rank}_{\mathbb {R}}P\).
Let \(X_{AB}\in \mathbf L(H_A\otimes H_B)\) and \(Y_{BC}\in \mathbf L(H_B\otimes H_C)\) be Hermitian, and suppose \([X_{AB}\otimes \mathbb {1}_C,\mathbb {1}_A\otimes Y_{BC}]=0\). There are positive integers \(d_q,m_q\), a unitary identification \(H_B\cong \bigoplus _{q=0}^{K-1}H_{q,l}\otimes H_{q,r}\), and Hermitian operators \(R_q\in \mathbf L(H_A\otimes H_{q,l})\) and \(S_q\in \mathbf L(H_{q,r}\otimes H_C)\) such that
This is the explicit coordinate form of the two block-action identities in [ Bei12 , Lemma 2.1 ] .
Suppose \(z{\gt}0\) and put \(\Omega _E=z^{-1/2}(P_E\otimes I_B)\Omega \). Then \(\| \chi \| =1\) and
In particular, every reduced state on a subsystem of \(B\) is preserved by this relabeling, as required in the marginal comparison of Section 7.
Let \(\rho ,\sigma \) be states on \(D\otimes E\), put \(\delta =\delta (\rho ,\sigma )\) and \(d_D=\dim D\), and let \(h(u)=-u\log u-(1-u)\log (1-u)\). Then
Neither bound depends on the dimension of \(E\).
Let \(I\) be finite, let \(x,p\in \mathbb R^I\) be nonnegative with \(\sum _i x_i=\sum _i p_i=1\), and let \(b,c{\gt}0\). Suppose that \(f:\mathbb R^I\to \mathbb R\) attains its minimum over the probability simplex at \(x\) and is Fréchet differentiable there, with
Then there exists \(0{\lt}\lambda \le 1\) such that
These are the simplex necessary conditions used in the patch-filter argument of [ Ope26a , Section 4 ] .
If \(x_i+b{\gt}0\) for every \(i\), then \(F\) is Fréchet differentiable at \(x\), with \(DF(x)v=-a\sum _i r_i(x_i+b)^{-a-1}v_i\). Suppose further that \(r_i\ge 0\), \(\sum _i r_i{\gt}0\), \(b{\gt}0\), and \(x_i\ge 0\). Then \(F(x){\gt}0\), \(p_i(x)\ge 0\), and \(\sum _i p_i(x)=1\). If also \(a{\gt}0\), \(\sum _i x_i=1\), and \(x\) minimizes the actual function \(F\) on the probability simplex, then the normalized weights \(p_i(x)\) satisfy (276)– (278) for some \(0{\lt}\lambda \le 1\).
With the notation of (289), the algebraic identity
holds for every \(H,\Omega ,E_0,\Delta \). If \(R\ge 0\), \(\| \Omega \| =1\), and \(\Delta \ge 0\), then
No eigenvector assumption is needed for this inequality.
Suppose \(\mathcal H=\mathcal H_A\otimes \mathcal H_B\), \(\| \Omega \| =1\), \(H\Omega =E_0\Omega \), \(\Delta \ge 0\), and \(H-E_0I\ge \Delta (I-|\Omega \rangle \! \langle \Omega |)\). Let \(F=F_A\) be the physical partial swap from Definition 13.28.1, and put \(\Phi =F\Psi \) and \(\mathbb H'=F\mathbb HF^\dagger \). Then
Both vectors and both Hamiltonians act on the same doubled physical space \((\mathcal H_A\otimes \mathcal H_B)^{\otimes 2}\).
Let \(U\) be unitary on \(\mathcal H\). Then \(\| U\Omega \| =\| \Omega \| \) and
Hence \(R\ge 0\) implies that the left side of (294) is positive semidefinite. If \(H\Omega =E_0\Omega \), then \((UHU^\dagger )(U\Omega )=E_0(U\Omega )\). These statements hold for every real \(E_0,\Delta \), without a normalization assumption.
The doubled vector satisfies
Consequently, \(\| \Omega \| =1\) implies \(\| \Psi \| =1\). If \(H\Omega =E_0\Omega \), then \(\mathbb H\Psi =2E_0\Psi \).
For positive semidefinite matrices \(A_1,\dots ,A_k\), \(S(\sum _jA_j)\le \sum _jS(A_j)\). With \(A_j=p_j\rho _j\) for states \(\rho _j\) and probability weights \(p_j\) this is the mixing bound \(S(\sum _jp_j\rho _j)\le H(p)+\sum _jp_jS(\rho _j)\).
For the reference in (86),
after canonical reassociation of the three tensor factors. The raw support-map summand is the maximally mixed specialization of [ HJPW04 , equation (10) ] . The complementary summand comes from the chosen support completion in (92). This theorem does not assert a Hayashi–Koashi–Imoto decomposition.
Let \(\rho \) be a Hermitian matrix and let \(\log \rho \) be its logarithm defined through the functional calculus. Then
If \(\rho _{BC}\) is positive semidefinite and \(\rho _B=\operatorname{tr}_C\rho _{BC}\), then
If \(P_B\) is the support projector of \(\rho _B\), then the support projector of \(d_A^{-1}\mathbf1_A\otimes \rho _B\) is
For the reference in (86),
For any PSD Hermitian matrix \(\rho \) with \(\operatorname{tr}(\rho ) = 1\) on an arbitrary finite index set, \(S(\rho ) \ge 0\). This is the analog of Theorem 13.6.4 for arbitrary finite index sets: it does not require the index set to be \(\{ 0,\ldots ,D{-}1\} \), so it applies to bipartite density matrices on \(\mathbb {C}^{d_A} \otimes \mathbb {C}^{d_B}\).
If \(z\ne 0\), then \(\sum _{i\in E}p_i'=1\). If \(z{\gt}0\) and \(p_i{\gt}0\), then \(p_i'{\gt}0\).
Let \(A=\sum _j M_j\) be a finite sum of Hermitian matrices. Suppose there are operators \(P_j\) such that
Then \(S(A)=\sum _j S(M_j)\). The operators \(P_j\) need only resolve the support of \(A\); their sum need not be the identity on the ambient space. This is the support form of the direct-sum entropy identity used in [ CPGSV16 , Appendix C.2, lines 1760–1770 ] .
For the reference in (86), the chosen complementary preparation term factors as
after the canonical reassociation of the three tensor factors. This follows from the chosen support completion in (92), not from [ HJPW04 , equation (10) ] .
For the reference in (86), the support Petz map for \(\operatorname{tr}_C\) factors as
after the canonical identification \((H_A\otimes H_B)\otimes H_C\cong H_A\otimes (H_B\otimes H_C)\). This is the maximally mixed specialization of [ HJPW04 , equation (10) ] . It is the tensor-product identity for the raw Petz support formula, not the Hayashi–Koashi–Imoto block decomposition.
For the reference in (80), the raw Petz map for \(\operatorname{tr}_C\) satisfies
Equivalently, for every product operator \(A_0\otimes X_B\),
The formulas use the canonical identification \((H_A\otimes H_B)\otimes H_C\cong H_A\otimes (H_B\otimes H_C)\).
This is the globally valid ambient-space form of [ HJPW04 , equation (10) ] . The literal identity-tensored formula in that equation is obtained on the support of \(\rho _A\), or after choosing an extension away from that support. For singular \(\rho _A\), the raw map on the full matrix algebra contains the compression \(X\mapsto P_AXP_A\).
Let \(X\) be an operator on \(H_A\otimes H_B\). If
then
If \(\rho _A\) is positive definite, then \(P_A=\mathbf1_A\), and this identity holds for every \(X\).
When \(\rho _A\) is singular, no global identity-tensored formula is asserted for the raw map outside the displayed support. Nor is the generic trace-preserving completion in Definition 13.6.63 asserted to factor: its complementary projection is \(\mathbf1_{AB}-P_A\otimes P_B\), which need not be the identity on \(A\) tensored with a projection on \(B\).
Set \(\rho _B=\operatorname{tr}_C\rho _{BC}\), and let \(P_A\) and \(P_B\) be the support projections of \(\rho _A\) and \(\rho _B\). Then
Each identity is understood after the same canonical reassociation of the three tensor factors.
Let \(z{\gt}0\). For every region \(B\) disjoint from \(X\), the same selected global vector satisfies
If also \(\| \psi \| =1\), then
These are the disjoint-region estimates of [ Ope26b , Section 8 ] .
If \(z{\gt}0\), then \(\| \psi _E\| =1\) and
For \(0{\lt}t{\lt}1\) the complementary mass satisfies
If \(S(\sigma )\le M\), \(M{\gt}0\) and \(c{\gt}0\), then at \(t=e^{-cM}\), \(\operatorname{rank}Q_t\le e^{cM}\) and \(\operatorname{tr}((\mathbb {1}-Q_t)\sigma )\le 1/c\).
Suppose \(S(\sigma )\le M\), \(M{\gt}0\), \(\rho \) is Hermitian of trace one and \(\| \rho -\sigma \| _1\le 1/16\). Then \(Q=Q_{e^{-16M}}\) satisfies \(\operatorname{rank}Q\le e^{16M}\) and \(\Re \operatorname{tr}((\mathbb {1}-Q)\rho )\le 1/8\). If moreover \(\rho ,x\ge 0\) commute, \(C{\gt}0\), \(u\ge 0\), \(M=C(1+u)\), \(R\ge (16C+\log 8)(1+u)\), and \(\rho \le x+e^{-R}\mathbb {1}\), then
Let \(\rho ,\sigma \) be Hermitian matrices of equal trace and \(0\le E\le \mathbb {1}\). Then \(\Re \operatorname{tr}(E\rho )-\Re \operatorname{tr}(E\sigma )\le \delta (\rho ,\sigma )\), where \(\delta (\rho ,\sigma )=\frac12\| \rho -\sigma \| _1\). In particular, for density \(\sigma \), Hermitian trace-one \(\rho \) and \(0{\lt}t{\lt}1\),
No commutation with \(\rho \) is required.
For any tripartite density matrix \(\rho _{ABC}\), equality in strong subadditivity holds if and only if \(\rho _{ABC}\) admits a quantum Markov decomposition on the middle subsystem \(B\).
This formulation introduces no new axiom: it is the same equality criterion as Theorem 13.8.78.
For any tripartite density matrix \(\rho _{ABC}\) on \(A \otimes B \otimes C\),
This formulation introduces no new axiom: it is the same strong-subadditivity statement as Theorem 13.8.4, which is proved there from Lieb concavity along the relative-entropy route [ LR73 ] .
Let \(\rho \) be a Hermitian matrix indexed by a finite set \(J\), and let \(e : I \to J\) be a bijection from a finite set \(I\). The reindexed matrix on \(I\) with entries \(\rho _{e(i)\, e(j)}\) has the same von Neumann entropy as \(\rho \).
Suppose that \(z=\sum _{i\in E}p_i{\gt}0\), and that real numbers \(S,w\) satisfy \(e^{-S-w}\le p_i\le e^{-S+w}\) for every \(i\in E\). Then
Let \(z{\gt}0\) and put \(\psi _{\mathrm{rem}}=((I_A-P_E)\otimes I_B)\psi \). The complementary marginal satisfies
If \(\| \psi \| =1\), then \(S(\rho _{\psi _E,B})\le S(\rho _B)/z\). These are the marginal estimates for the typical Schmidt truncation in [ Ope26b , Section 8 ] .
Let \(\psi \in \mathcal H_A\otimes \mathcal H_B\otimes \mathcal H_C\) and let \(\psi _E\) be its normalized spectral truncation on \(A\), with selected mass \(z{\gt}0\). Put \(\rho _B=\operatorname {tr}_{AC}|\psi \rangle \langle \psi |\) and \(\rho _{\psi _E,B}=\operatorname {tr}_{AC}|\psi _E\rangle \langle \psi _E|\). With the unnormalized discarded vector \(\psi _{\mathrm{rem}}=((I_A-P_E)\otimes I_{BC})\psi \), one has
If \(\| \psi \| =1\), then \(S(\rho _{\psi _E,B})\le S(\rho _B)/z\). This proves the estimates in [ Ope26b , Section 8 ] for every subsystem disjoint from the projected region.
The operator \(P_E\) is an orthogonal projection and commutes with \(\rho \). The normalized spectral restriction satisfies \(\rho _E=z^{-1}P_E\rho P_E\). If \(z\ne 0\), then \(\operatorname {tr}\rho _E=1\). If \(\rho \ge 0\) and \(z{\gt}0\), then \(\rho _E\ge 0\). If \(\rho \ge 0\) and \(\operatorname {tr}\rho =1\), then \(z\le 1\).
- Matrix.IsHermitian.isStarProjection_spectralSelection
- Matrix.IsHermitian.commute_spectralSelection
- Matrix.IsHermitian.normalizedSpectralRestriction_eq
- Matrix.PosSemidef.normalizedSpectralRestriction_posSemidef
- Matrix.IsHermitian.trace_normalizedSpectralRestriction
- Matrix.PosSemidef.spectralRestrictionMass_le_one
Let \(\rho \ge 0\), let \(S=S(\rho )\), and suppose that \(z{\gt}0\) and \(e^{-S-w}\le p_i\le e^{-S+w}\) for every \(i\in E\). Then
This gives the typical-Schmidt entropy estimates for actual reduced density matrices [ Ope26b , Section 8 ] ; zero eigenvalues outside \(E\) are permitted.
Let \(\rho \ge 0\) have trace one, with eigenvalues \(p_i\), and put \(S=S(\rho )\). For \(w\in \mathbb R\), take its canonical typical set
Suppose that
Then \(1-\delta \le z\le 1\) and \(z{\gt}0\). The actual spectral restriction \(\sigma =z^{-1}P_E\rho P_E\) is positive semidefinite with trace one and
This is a finite-dimensional consequence of the typical-set estimates in [ Ope26b , Section 8 ] , conditional on a spectral tail bound.
If \(z\ne 0\) and every selected eigenvalue is positive, then \(\operatorname {rank}\rho _E=|E|\). If \(\rho \ge 0\) and \(z{\gt}0\), then \(S(\rho _E)=S(p')\), where \(p_i'=p_i/z\) for \(i\in E\).
If \(z{\gt}0\), then \(\| \psi _E\| =1\), \(\operatorname {tr}_B|\psi _E\rangle \langle \psi _E|=z^{-1}P_E\rho _A P_E\), and \(\langle \psi ,\psi _E\rangle =\sqrt z\). If also \(\| \psi \| =1\), then
Let \(\psi \in \mathcal H_A\otimes \mathcal H_B\) be a unit vector. Form the preceding canonical set \(E\) from its actual marginal \(\rho _A\), with center \(S=S(\rho _A)\), and assume the same tail bound \(\delta {\lt}1\). Let \(\psi _E=z^{-1/2}(P_E\otimes I_B)\psi \) be the selected vector. Then
Under the hypotheses of Theorem 13.22.1.3,
These are the typical-Schmidt entropy estimates [ Ope26b , Section 8 ] .
Let \(\omega _j\) be density matrices and let \(p_j\geq 0\). Then
In particular, when the \(p_j\) form a probability distribution, this is
This is the entropy identity used in [ CPGSV16 , Appendix C.2, lines 1760–1770 ] .
Let \(k,r\) be nonnegative integers and \(0\le \tau \le 1/2\). If \(r\le \tau k\), then
These are the binomial estimates used before the inverse-compression inequality in [ Ope26b , Section 7 ] .
Let \(\Omega \in \mathcal H\), let \(B\subseteq \{ 1,\ldots ,k\} \), and put \(w=(R_B\otimes I_{\mathcal K})v\). Suppose \(\sigma B=B\) and \((U_\sigma \otimes V_\sigma )v=v\), where \(U_\sigma \) permutes the physical copies and \(V_\sigma \) is a permutation representation on \(\mathcal K\). Then \(V_\sigma \) commutes with \(\operatorname {Tr}_{\mathcal H^{\otimes k}}|w\rangle \langle w|\).
Let \(S\) be a finite set with \(k\) elements and \(0\le \tau \le 1/2\). Then
This is the subset-count estimate preceding the inverse-compression inequality in [ Ope26b , Section 7 ] .
In the setting of Theorem 13.16.1.5, the two marginals of \(\rho _c\) satisfy
Both compressed marginals are positive definite, including when one of their spaces has dimension zero.
For normalized finite-dimensional states,
Moreover, after enlarging the purifying space if necessary, an isometry on that space realizes overlap \(F(\rho ,\sigma )\) between purifications. In particular, if \(I(A{:}C)\le \delta \) for a pure state \(\Omega \) on \(\mathbb {C}^A\otimes \mathbb {C}^C\otimes \mathbb {C}^U\), then there are an isometry \(V:\mathbb {C}^U\to \mathbb {C}^A\otimes (\mathbb {C}^C\oplus \mathbb {C}^U)\) and unit vectors \(s\in \mathbb {C}^A\otimes \mathbb {C}^A\) and \(s'\in \mathbb {C}^C\otimes (\mathbb {C}^C\oplus \mathbb {C}^U)\) purifying \(\rho _A\) and \(\rho _C\), so that \(s\otimes s'\) purifies \(\rho _A\otimes \rho _C\), with \(\lVert (\mathbb {1}_{AC}\otimes V)\Omega -s\otimes s'\rVert \le \sqrt\delta \). This is [ Ope26a , Lemma 2.2 ] .
For a finite totally ordered family and \(P_i=\bigcup _{j{\lt}i}X_j\),
For pairwise-disjoint \(X,C,Z\), purity also gives \(I_\psi (X:C\mid Z)=I_\psi (X:C\mid (X\cup C\cup Z)^c)\).
The entropy expressions satisfy \(I_\psi (X:C\mid Z)=I_\psi (X:C\cup Z)-I_\psi (X:Z)\). For a normalized state and disjoint \(X,Z\), this implies \(I_\psi (X:C\mid Z)\le I_\psi (X:C\cup Z)\).
Let \(\psi \) be a normalized pure state on a finite product, and let \(G,B,C\) be pairwise-disjoint regions. Suppose \(G=D\mathbin {\dot\cup }\bigcup _{i\in \mathcal I_0}X_i \mathbin {\dot\cup }\bigcup _{j\in \mathcal I_1}Y_j\) is a disjoint partition with a total order on each finite index set. Put \(F=(G\cup B\cup C)^c\), \(P_i=\bigcup _{k{\lt}i}X_k\) and \(Q_j=\bigcup _{k{\lt}j}Y_k\). Assume \(I_\psi (X_i:C\cup B\cup P_i)\le \varepsilon _i\) and \(I_\psi (Y_j:C\cup F\cup Q_j)\le \delta _j\) for all indices. Then
This is the entropy estimate inside the proof of [ Ope26a , Lemma 3.2 ] , before the geometric counting argument. No nonempty-region or sign condition on the errors is required.
Let \(V\) be a finite set, with finite coordinate sets \(\mathcal B_v\), and let \(\mathcal H_R=\mathbb C^{\prod _{v\in R}\mathcal B_v}\) for \(R\subseteq V\). For unit vectors \(\Omega ,\Phi \in \mathcal H_V\), write \(\rho _\Omega =|\Omega \rangle \langle \Omega |\), \(\rho _\Phi =|\Phi \rangle \langle \Phi |\), and \(\delta =\tfrac 12\| \rho _\Omega -\rho _\Phi \| _1\). Then every region \(R\subseteq V\) satisfies
This is the regional form of Lemma 2.1 used in the scanner argument of [ Ope26b , Section 9 ] . The two vectors and the region are supplied to the estimate; no further choice is made.
Let \(\mathcal I\) be a finite totally ordered index set, and set \(P_i=\bigcup _{j{\lt}i}X_j\). If \(I_\psi (X_i:B\cup P_i)\le \varepsilon _i\) for each \(i\), then
Let \(\psi \) be a unit pure state, and put \(b=I_\psi (T:E)\). There are finite-dimensional spaces \(\mathcal B_T,\mathcal B_E\), an isometry \(W:\mathcal H_U\to \mathcal B_T\otimes \mathcal B_E\), and unit vectors \(s\in \mathcal H_T\otimes \mathcal B_T\) and \(s'\in \mathcal H_E\otimes \mathcal B_E\) such that
One may take \(\mathcal B_T=\mathbb C^{d_T}\) and \(\mathcal B_E=\mathbb C^{d_E}\oplus \mathcal H_U\). The isometry acts on all of \(\mathcal H_U\). This is the finite-product form of [ Ope26a , Lemma 6.4 ] .
The joint regional density matrix, expressed in the enumerated bases, is \(\rho _{TE}=\operatorname {Tr}_U |\widetilde\psi \rangle \langle \widetilde\psi |\). If \(\| \psi \| =1\), then \(\| \widetilde\psi \| =1\).
For a normalized pure state and disjoint \(X,Y\), \(I_\psi (X:Y)\le 2S_\psi (X)\). If \(D\) is disjoint from both \(C\) and \(Z\), then \(I_\psi (D:C\mid Z)\le 2S_\psi (D)\).
Let \(\psi \) be a normalized pure state on the finite tensor product. Suppose \(A=D\mathbin {\dot\cup }\bigcup _{i\in \mathcal I_0}X_i \mathbin {\dot\cup }\bigcup _{i\in \mathcal I_1}X_i\) is a disjoint partition, with a total order on each finite family. Put \(B=\Lambda \setminus A\) and \(P_i=\bigcup _{j\in \mathcal I_f,\, j{\lt}i}X_j\) for \(i\in \mathcal I_f\). If \(I_\psi (X_i:B\cup P_i)\le \varepsilon _i\) for all indices, then
This is [ Ope26b , Lemma 11.1 ] . Empty families, empty regions, and varying local dimensions are permitted.
For every real function \(f\) on the irreducible labels, the observables of \(\{ Q\} ,\{ C\} ,\{ Q,C\} \), expressed in the coordinates \(e\), are respectively
Those of \(\{ V\} ,\{ R\} ,\{ V,R\} \) are respectively
All spaces in these formulas comprise the same \(m\) good copies.
Set \(\Delta _{QC}=F_Q+F_C-F_{QC}\) and \(\Delta _{VR}=F_V+F_R-F_{VR}\). Let \(D_{QC}\) and \(D_{VR}\) be the corresponding paired-copy deficits, each extended by the identity on the other pair. In the coordinates \(e\),
For every real label function \(f\), express the five good factors in the physical–auxiliary coordinates \((Q_GY_GV_G),(C_GR_G)\). Then the observable \(L_{\{ j\} }(f)\) is
where \(L_{j,m}(f)\) belongs to the original copy action on \(H_j^{\otimes m}\).
Let \(U_g\) and \(V_g\) be permutation representations on finite-dimensional spaces \(\mathcal H\) and \(\mathcal K\). If \(v\in \mathcal H\otimes \mathcal K\) satisfies \((U_g\otimes V_g)v=v\), then
Under the hypotheses of Theorem 13.17.1.1, the matrix
is positive semidefinite, and
This is the faithful-marginal-support form of the order-two estimate obtained from [ Bei13 , Theorem 6, Equation (18) ] .
Let \(\rho _{AB}\geq 0\), and choose an eigenbasis of its faithful first marginal \(\sigma =\operatorname{diag}(p_1,\ldots ,p_{d_A}){\gt}0\). Suppose also that the second marginal \(\tau \) is positive definite. For the supported-marginal channel \(\Phi _\rho \), set
Then
Here \(\sigma ^T=\sigma \) because the chosen basis diagonalizes \(\sigma \).
For \(h\ge 0\) and \(\omega ,s\in \mathbb {R}\),
In particular, all these exponential moments are finite, and the centered Gaussian is sub-Gaussian with variance parameter \(h\). For \(h{\gt}0\), the first integral also equals \(\int _{\mathbb {R}}g_h(t)e^{i\omega t}\, dt\). The frequency \(\omega \) is angular frequency, so no additional factor of \(2\pi \) occurs in the exponent.
Under the hypotheses of Theorem 13.30.3.1, let \(h\ge 0\) and suppose \(x,y\in \mathcal H\) satisfy
for every \(k\). Then
Let \(h{\gt}0\) and let \(f\) take values in a real normed vector space. Then \(g_hf\) is Lebesgue integrable if and only if \(f\) is integrable with respect to \(\mu _h\). The integrals satisfy
for every measurable set \(S\). In particular, \(\int _S g_h(t)\, dt=\mu _h(S)\).
For Hermitian \(\mathbb H',\mathbb H\), every \(h\ge 0\) and \(T\in \mathbb {R}\),
Suppose \(\mathbb H'\) and \(\mathbb H\) are Hermitian and \(h\ge 0\). For every \(T\in \mathbb {R}\),
In particular, for \(T\ge 0\),
For \(h{\gt}0\) and arbitrary matrices \(\mathbb H',\mathbb H,W\),
If the two generators are Hermitian, these density integrands are integrable. At zero variance, \(M_0(\mathbb H',\mathbb H;W)=W\). For every \(h\ge 0\), \(M_h(\mathbb H',\mathbb H;0)=0\).
Let \(\mathbb H'v=Ev\) and \(\mathbb Hw=E'w\), where \(E,E'\in \mathbb {R}\). If \(\mathbb H'\) is Hermitian, then
If both generators are Hermitian, then for every \(h\ge 0\),
The vectors need not be normalized or real. In coordinates, \(\langle v,M_hw\rangle =\sum _j\overline{v_j}(M_hw)_j\).
Let \(K\) be Hermitian, \(\| \Omega \| =1\), \(K\Omega =\mathcal E\Omega \), and \(\Delta {\gt}0\). Suppose
For an orthonormal eigenbasis \(Ku_k=\lambda _ku_k\), each \(k\) satisfies one of the following alternatives:
Thus \(\Delta \) is a lower bound on the gap; equality with the least excitation energy is not required.
Assume (316), \(\Delta {\gt}0\), and \(\mathbb H'-\mathcal E I\ge \Delta (I-|\Phi \rangle \! \langle \Phi |)\). For every \(h\ge 0\),
Only the target Hamiltonian \(\mathbb H'\) needs a gap for this bound.
The function \(t\mapsto A_t\) is continuous for arbitrary matrices \(\mathbb H',\mathbb H,W\). If \(\mathbb H'\) and \(\mathbb H\) are Hermitian, then \(\| A_t\| =\| W\| \) for every \(t\). In that case \(A_t\) is integrable against \(\mu _h\) and its restriction to \([-T,T]\), for every \(h\ge 0\) and every \(T\in \mathbb {R}\).
For every \(h\ge 0\), the function \(g_h\) is nonnegative and integrable. For \(h{\gt}0\), \(\int _{\mathbb {R}}g_h(t)\, dt=1\).
Let \(\Delta {\gt}0\) and \(r\ge 0\) be real. There exist \(A{\gt}0\) and \(T_0{\gt}0\), depending only on \(\Delta \) and \(r\), such that
For every real \(b\ge 0\) and \(L\ge 1\), put \(B_*=1+b+\log L\), \(h=AB_*\), and \(T=T_0B_*\). Then \(h{\gt}0\), \(T\ge 0\), and
These bounds also hold for any \(A{\gt}0\) and \(T_0\ge 0\) satisfying (335) and (336).
Let \(\Delta {\gt}0\) and \(r\ge 0\) be real. There are constants \(a{\gt}0\) and \(T_0{\gt}0\), depending only on \(\Delta ,r\), with the following property. Let \(\mathcal H_R,\mathcal H_C,\mathcal H_Q\) be finite-dimensional complex Hilbert spaces, and put \(\mathcal H=\mathcal H_R\otimes \mathcal H_C\otimes \mathcal H_Q\). Suppose \(H\) is an operator on \(\mathcal H\), \(\Omega \) is a unit vector, and \(E_0\in \mathbb {R}\) and \(b\ge 0\) satisfy
With \(\rho _{RC}=\operatorname {Tr}_Q|\Omega \rangle \! \langle \Omega |\), \(\rho _R=\operatorname {Tr}_C\rho _{RC}\), and \(\rho _C=\operatorname {Tr}_R\rho _{RC}\), suppose also that \(D(\rho _{RC}\Vert \rho _R\otimes \rho _C)\le b\).
Let \(U_e\) regroup the two copies of \(\mathcal H\) as \((\mathcal H_R\otimes \mathcal H_C)^{\otimes 2} \otimes \mathcal H_Q^{\otimes 2}\), and let \(S\) exchange the two \(R\) registers while fixing both \(C\) and both \(Q\) registers. Set
Write \(\Psi =U_e(\Omega \otimes \Omega )\) and \(\Phi =S\Psi \). There are a Hermitian contraction \(W\) on \(\mathcal H_Q^{\otimes 2}\) and a real \(z\ge e^{-2b}\), chosen independently of \(L\), such that \(\langle \Phi | V\Psi \rangle =z\) for \(V=\mathbb {1}_{(RC)^{\otimes 2}}\otimes W\).
For every real \(L\ge 1\), put \(B_*=1+b+\log L\), \(h=aB_*\), and \(T=T_0B_*\). Then \(h{\gt}0\) and \(T\ge 0\). The unrenormalized integral
satisfies \(\| M_L\| \le 1\) and
This is the uniform Gaussian approximation step in the reset argument of [ Ope26a ] .
Under (316) and (319), suppose \(\Delta {\gt}0\), \(\| W\| \le 1\), and \(\langle \Phi ,W\Psi \rangle =z\in \mathbb {R}\). For every \(h\ge 0\),
For all complex matrices \(A,H\) indexed by \(n\) and all \(t\in \mathbb {R}\),
Let \(h\ge 0\), \(T\in \mathbb {R}\), and let \(H',H,W\) be arbitrary complex matrices indexed by \(n\). For the centered Gaussian measure \(\mu _h\) of variance \(h\), the actual full integral satisfies
Its unrenormalized truncation satisfies
Equivalently, \(R_e(M_h(H',H;W))=M_h(R_e(H'),R_e(H);R_e(W))\), with the same identity for \(M_h^T\). The variance, cutoff, and restricted Gaussian mass are preserved.
These identities include \(h=0\), when \(\mu _0=\delta _0\) and the full integral is \(W\). They also include \(T{\lt}0\), when \([-T,T]\) is empty and both truncated integrals vanish. No Hermiticity, positive variance, nonnegative cutoff, or nonempty-index assumption is required.
Let \(\mu \) be a measure on a measurable space \(X\) and let \(F:X\to \mathbb {C}^{n\times n}\) be any function. Then
The integrals use the convention that a nonintegrable function has integral zero. No integrability assumption is needed.
For \(h\ge 0\) and \(T\ge 0\), \(\mu _h(I_T^c)\le \tau _h(T)\). For \(h{\gt}0\), this gives the density estimate
Under (316) and (319), suppose \(\Delta {\gt}0\), \(h\ge 0\), and \(T\ge 0\). With \(\varepsilon =(q_h+\tau _h(T))\| W\| \),
In particular, at positive variance the common bound is exactly
Assume (316), \(\Delta {\gt}0\), and both lower-gap inequalities
For every \(h\ge 0\),
Let \(\Delta {\gt}0\) and \(r\ge 0\) be real. There exist \(A{\gt}0\) and \(T_0{\gt}0\), depending only on \(\Delta ,r\), with the following property. For every real \(b\ge 0\) and \(L\ge 1\), put \(B_*=1+b+\log L\), \(h=AB_*\), and \(T=T_0B_*\). Then \(h{\gt}0\) and \(T\ge 0\).
In any finite-dimensional complex Hilbert space, let \(H,H'\) be self-adjoint operators and let \(W\) be a contraction. Suppose that unit vectors \(\Psi ,\Phi \) and a real number \(E_0\) satisfy
Define \(z=\langle \Phi | W\Psi \rangle \) and the unrenormalized integral
Then \(\| M_T\| \le 1\), and
This is the uniform Gaussian approximation in the reset argument of [ Ope26a ] .
Let \(B\in M_{m,k}(\mathbb {C})\) and \(A\in M_{m',k}(\mathbb {C})\) satisfy \(B^\dagger B=A^\dagger A\), with \(m'\le m\). Then \(B=TA\) for some isometry \(T\in M_{m,m'}(\mathbb {C})\). Equivalently, if \(X\in M_{a,m}(\mathbb {C})\) and \(Y\in M_{a,m'}(\mathbb {C})\) satisfy \(XX^\dagger =YY^\dagger \) with \(m'\le m\), then \(X=YT^\dagger \) for some isometry \(T\in M_{m,m'}(\mathbb {C})\).
Let a group \(G\) act by permutations on finite sets \(Z\) and \(B\), with actions \(\alpha \) and \(\beta \). Let \(A\) be any set and \(e:Z\to A\times B\) a bijection satisfying
for every \(g\in G\) and \(z\in Z\). Let \(\pi _\alpha \) and \(\pi _\beta \) be the linear extensions of the two permutation representations to \(\mathbb C[G]\). For every \(h\in \mathbb C[G]\), \(a,a'\in A\), and \(b,b'\in B\),
Equivalently, the matrix in product coordinates is \(I_A\otimes \pi _\beta (h)\). Neither \(G\) nor \(A\) is required to be finite.
Let \(S_j\) be a finite family of subsystems and let \(a_j\in \mathbb R\). Writing \(F_{S_j,G}\) for the first-subgroup label entropy on the full space, the same coordinates give
No disjointness of the subsystems is required. This is a coordinate identity, as used in [ Ope26b , Section 8, lines 454–560 ] .
For a tripartite density matrix \(\rho _{ABC}\),
holds if and only if \(\rho _{ABC}\) admits a quantum Markov decomposition on the middle subsystem \(B\).
Let \(\rho _{ABC}\) be a tripartite density matrix satisfying
Then there are a decomposition
a unitary \(V_B\), probabilities \(p_j\), and density matrices \(\rho _{A B_j^L}\) and \(\rho _{B_j^R C}\) such that, for \(V=\mathbf1_A\otimes V_B\otimes \mathbf1_C\),
For every density matrix \(\rho \), there is one sequence \((\lambda _k)_{k\ge 0}\) such that, for all sufficiently large \(k\),
and
Let \(\sigma \) be a density matrix on \(\mathcal H_R^{\otimes k}\) which commutes with all copy permutations. Let \(a\in \mathbb R\) and \(w\ge 0\). Set \(L=-\log \sigma \), with the logarithm assigned value zero on the kernel. If
then there is a label \(\lambda \) such that
For every density matrix \(\rho \) on \(\mathcal H_R\), for all sufficiently large \(k\) there is a label \(\lambda \) satisfying
No invertibility of \(\rho \) is assumed.
Let \(\psi \in \mathcal H_S\otimes \mathcal H_R\) be a unit vector, let \(\rho =\operatorname {tr}_S|\psi \rangle \langle \psi |\), and let \(v_k\) be its literal tensor power regrouped into \(\mathcal H_S^{\otimes k}\otimes \mathcal H_R^{\otimes k}\). There is one sequence \((\lambda _k)\) for which, for all sufficiently large \(k\),
and \(\log d_{\lambda _k}=kS(\rho )+o(k)\).
Let \(\rho _{ABC}\) be a tripartite density matrix attaining equality in strong subadditivity. Then the ambient middle subsystem has a direct-sum tensor decomposition
In unitary coordinates adapted to this decomposition there are density matrices \(\sigma _j\) and positive, not necessarily normalized operators \(\omega _j\) such that
The tensor factors appear here in the order \(b_j^R\otimes b_j^L\), the reverse of HJPW’s \(b_j^L\otimes b_j^R\) order. Directions complementary to the minimum joint support form one-dimensional tensor sectors with zero \(\omega _j\).
This is [ HJPW04 , Theorem 6, equations (13)–(14) ] , lines 493–502.
If two operators \(X,Y\) on \(A\otimes B\) have
for every member of the finite effect family, then \(X=Y\).
Let \(\rho _{ABC}\) be a tripartite density matrix attaining equality in strong subadditivity, and put \(\rho _{AB}=\operatorname{tr}_C\rho _{ABC}\). If \(\widehat{\mathcal R}:B\to B\otimes C\) is the completed recovery channel, define
Then \(\varphi \) is trace-preserving and completely positive and
For each selected effect, let
The indices with \(p_s\neq 0\) form a finite nonempty set. For each such index, positivity of \(\xi _s\) makes \(p_s\) real and positive, and
is a density operator and \(\varphi (\mu _s)=\mu _s\). Consequently a Kraus representation of \(\varphi \) gives a single preserving operation for this finite nonempty density family.
This is the conditional-family construction in [ HJPW04 , Theorem 6, lines 493–505 ] . Effects with \(p_s=0\) are omitted before normalization; no artificial conditional state is introduced for them.
- Matrix.petzMiddleChannel
- Matrix.petzMiddleChannel_isKrausCPTP
- Matrix.idTensor_petzMiddleChannel_traceC_ABC_eq
- Matrix.ActiveConditionalEffectIndex
- Matrix.activeConditionalEffectIndex_nonempty
- Matrix.normalizedConditionalSlice
- Matrix.normalizedConditionalSlice_posSemidef
- Matrix.normalizedConditionalSlice_trace
- Matrix.map_conditionalSlice_eq_self_of_idTensorMap_eq_self
- Matrix.petzMiddleChannel_normalizedConditionalSlice
- Matrix.exists_preservingKrausFamily_normalizedConditionalSlice
Let \(\rho _{ABC}\) be a tripartite density matrix attaining equality in strong subadditivity, and let \(\mu _s\) be the finite nonempty family of normalized conditional states obtained from the active separating effects. On the minimum joint supporting subspace of this family there are tensor-product direct-sum coordinates such that
where the weights form probability distributions and all factors are density operators. The support isometry reconstructs every \(\mu _s\).
The channel
restricts to the same support and intertwines with its ambient action. In these coordinates its action on each diagonal summand is
The tensor factors are written in the reverse order from HJPW.
This is the application of HJPW Theorem 6, lines 493–505, to Properties 1 and \(2'\) from Appendix A, lines 761–816 and 853–882.
Let \(\rho _{ABC}\) be a tripartite density matrix attaining equality in strong subadditivity, and let \(V\) be the support isometry and \((e,U,\sigma _j)\) the direct-sum coordinates of Theorem 13.8.71. Put \(W=\mathbf1_A\otimes V\). Then
In the same support coordinates there are positive, not necessarily normalized operators \(\omega _j\) such that
The tensor factors are written in the reverse order from HJPW. The block equation is on the minimum joint supporting subspace; it does not assert an ambient direct-sum equivalence on subsystem \(B\).
Scope restriction (HJPW Theorem 6, equation (14)): the displayed direct sum is restricted to the minimum joint supporting subspace, whereas equation (14), lines 499–502, decomposes the ambient subsystem \(B\). This restriction is documented in the TNLean paper-gap note [ con26s ] .
Let \(\rho _{ABC}\) be a tripartite density matrix attaining equality in strong subadditivity, with the ambient decomposition
from Theorem 13.8.73. There are a finite-dimensional ancilla, a fixed pure ancilla vector, and one unitary \(U_{BCE}\) whose block-coordinate form is
On every supported sector, \(U_j\) dilates a trace-preserving completely positive map from \(b_j^R\) to \(b_j^R C\) that sends \(\sigma _j\) to a state whose \(b_j^R\) marginal is \(\sigma _j\). The resulting state is positive and has trace one. The displayed block form uses the order \(U_j\otimes \mathbf1_{b_j^L}\); in HJPW’s order it is \(\mathbf1_{b_j^L}\otimes U_j\).
The recovery operation determined by the chosen unitary agrees with the Petz recovery operation on every operator supported by the minimum joint supporting subspace, and
No equality of the two operations is asserted on the complementary ambient sectors.
This is [ HJPW04 , Theorem 6, equation (15) ] , lines 547–560, using Appendix A, Theorem 10, Property 2, lines 791–800, the equivalence with Property \(2'\) in lines 808–823, and the operation-level proof in lines 853–882.
Let \(\rho _{ABC}\) be a tripartite density matrix attaining equality in strong subadditivity, and let \(U_B\) and the factors \(\omega _j\) be those of Theorems 13.8.73 and 13.8.74. For each supported sector, put
This is a density matrix on \(\mathcal H_{b_j^R}\otimes \mathcal H_C\), where \(\widehat{\mathcal R}_j\) is the sector recovery operation. Read each middle-system summand in the HJPW order \(\mathcal H_{b_j^L}\otimes \mathcal H_{b_j^R}\), and set \(W=\mathbf1_A\otimes (U_B\otimes \mathbf1_C)\). Then
Thus every complementary block is zero, while the supported \(j\)th block, in the factor order \((A b_j^L)\otimes (b_j^R C)\), is \(\omega _j\otimes \widehat\rho _j\). The factors \(\omega _j\) remain unnormalized; no probabilities or normalized left factors are asserted.
This is the final substitution in [ HJPW04 , Theorem 6, equations (11), (14), and (15) ] , lines 562–570.
Let \(\rho \) be positive semidefinite on a finite-dimensional complex Hilbert space, with eigenvalues \(p_i\), and put \(M_p(u)=\sum _i p_i e^{-u\log p_i}\). For \(k\geq 0\) and \(u,s\in \mathbb R\),
The logarithm is assigned the value zero on the kernel. No trace normalization is assumed. Zero copies give the identity on the one-dimensional space of empty configurations.
Let \(\rho \) be a positive semidefinite matrix of trace one on a finite-dimensional complex Hilbert space of dimension \(d\). Write \(p_i\) for its eigenvalues, \(S=-\sum _i p_i\log p_i\), and \(M_p(v)=\sum _i p_i e^{-v\log p_i}\), with zero spectral weights contributing zero. Let \(K,r\in \mathbb R\) satisfy \(\log M_p(v)\leq vS+Kv^2\) for every \(|v|\leq r\). For a nonnegative integer \(k\), let \(\rho _k=\rho ^{\otimes k}\) and \(F_k=\sum _\lambda \log (\dim \lambda )\pi _\lambda \) be the central entropy observable of the copy-permutation action. If \(u\geq 0\), \(2u\leq r\), and \(2u\leq 1\), then
These bounds retain the entropy center in the signed moment estimates of [ Ope26b , Section 8 ] .
Let \(K,r\) be real and suppose \(\log M_p(v)\leq vS+Kv^2\) whenever \(|v|\leq r\). Let \(F_k=\sum _\lambda \log (\dim \lambda )\pi _\lambda \) be the central entropy observable for the permutation action on the \(k\) copies. If \(u\geq 0\), \(2u\leq r\), and \(2u\leq 1\), then
These are the explicit independent-copy bounds in [ Ope26b , Section 8 ] .
Let \((p_i)_i\) be any finite probability distribution, allowing zero weights, and let \(S,V\) be given by (355). For every \(k\ge 0\) and \(w{\gt}0\),
For every \(k\ge 0\) and \(w{\gt}0\),
In particular, for \(k{\gt}0\) and \(w=k^{3/4}\),
Thus the mass outside this entropy window tends to zero for a fixed density matrix as the number of copies tends to infinity.
For every real function \(f\) and \(k\ge 0\),
This identity also holds for any positive semidefinite \(\rho \) whose trace need not be one. A real function on a finite spectrum defines its spectral functional calculus without a global continuity assumption.
For every real number \(V\) and every integer \(m\ge 0\), there is an integer \(K\ge 1\) such that, for all integers \(k\ge K\),
In particular, the estimate applies to a nonnegative variance \(V\). It requires no spectral or representation label assumptions.
For every pair of matrices \(H^{\prime },H\in \mathcal M\), define
Then \(V\) is differentiable and \(V^{\prime }(t)=iG(t)V(t)\) for every \(t\in \mathbb {R}\). Neither matrix is required to be Hermitian.
Let \(V:\mathbb {C}^k\to \mathbb {C}^D\) satisfy \(V^\dagger V=\mathbb {1}_k\). For every \(A\in M_{k}(\mathbb {C})\),
Let \(\rho ,\sigma \in M_{D}(\mathbb {C})\) be density matrices with \(\sigma \) of full rank. Then the relative entropy vanishes exactly when the states coincide, \(D(\rho \Vert \sigma )=0\iff \rho =\sigma \). Together with nonnegativity, this is the order property that makes \(D\) a divergence.
Let \(\rho ,\sigma \in M_{D}(\mathbb {C})\) be density matrices satisfying the support condition \(\ker \sigma \subseteq \ker \rho \), that is, every vector annihilated by \(\sigma \) is annihilated by \(\rho \). Then the relative entropy is non-negative, \(D(\rho \Vert \sigma )\ge 0\).
Under the hypotheses of Definition 13.8.59, there are \(L\in \mathbb {N}\), positive dimensions \(d_0,\ldots ,d_{L-1}\) and multiplicities \(m_0,\ldots ,m_{L-1}\) with \(\sum _\ell d_\ell m_\ell =D\), and a unitary \(U\in M_{D}(\mathbb {C})\) such that a matrix \(A\in M_{D}(\mathbb {C})\) belongs to \(A_0\) exactly when
for some matrices \(B_\ell \in M_{d_\ell }(\mathbb {C})\).
Under the hypotheses of Definition 13.8.59, there are \(L\in \mathbb {N}\), positive dimensions \(d_\ell ,m_\ell \), a unitary \(U\), and density matrices \(\sigma _\ell \in M_{m_\ell }(\mathbb {C})\) such that, for every member \(\rho _k\) of the invariant family, there are matrices \(X_{\ell ,k}\in M_{d_\ell }(\mathbb {C})\) satisfying
The density matrices \(\sigma _\ell \) and the decomposition are common to the whole family.
No positivity or trace normalization is asserted for the matrices \(X_{\ell ,k}\). Thus this is the full-support fixed-point block form underlying HJPW Appendix A, lines 853–856, not the normalized decomposition of Property 1.
Let \(\rho _1,\ldots ,\rho _K\) be density operators, without a faithfulness assumption on their average. On their minimum joint supporting subspace there is one direct-sum tensor decomposition in which
where the weights form probability distributions and all displayed factors are density operators. Every trace-preserving completely positive operation preserving the compressed family acts on each diagonal summand as
In particular, every operation preserving the original family restricts to such an operation, and its action transports back through the support isometry by the intertwining identity above. The support isometry reconstructs every original \(\rho _k\) from \(\widehat\rho _k\).
This is HJPW Properties 1 and \(2'\) after the joint-support reduction in Appendix A, lines 761–816 and 853–882. The tensor factors are written in the reverse order from HJPW.
Let \(\rho _1,\ldots ,\rho _K\) be density operators and let \(Q\) be the support projection of their average. There are an integer \(r\) and an isometry \(V:\mathbb C^r\to \mathcal H\) with \(VV^\dagger =Q\) such that the compressed states \(\widehat\rho _k=V^\dagger \rho _kV\) are density operators, their average is positive definite, and
Every trace-preserving completely positive operation preserving all \(\rho _k\) compresses along the same isometry to a trace-preserving completely positive operation \(\widehat F\) preserving all \(\widehat\rho _k\). Its ambient and compressed actions intertwine:
This is the reduction to the minimum joint supporting subspace in HJPW, Appendix A, lines 761–763.
The map \(P_0^*\) is positive, unital, and idempotent, and its range is exactly \(A_0\).
Suppose in addition that every \(\rho _k\) is positive semidefinite with trace one. Under the explicit positive-definite common-average hypothesis of Definition 13.8.59, the common decomposition of Theorem 13.8.66 admits numbers \(q_{\ell |k}\geq 0\) and density matrices \(\tau _{\ell |k}\in M_{d_\ell }(\mathbb {C})\) such that, for every \(k\),
The density matrix \(\sigma _\ell \) is independent of \(k\). The tensor factors are written in the reverse order from HJPW Property 1. This is the full-support specialization of that state decomposition. No action of a preserving operation on the summands is asserted in this theorem; the next theorem supplies it under the same full-support hypothesis.
Use the decomposition of Theorem 13.8.67. For every trace-preserving completely positive operation \(F\) satisfying \(F(\rho _k)=\rho _k\) for all \(k\), and every summand \(\ell \), there is a trace-preserving completely positive operation \(F_\ell \) on \(M_{m_\ell }(\mathbb {C})\) such that \(F_\ell (\sigma _\ell )=\sigma _\ell \). If \(\iota _\ell \) denotes inclusion of the \(\ell \)-th diagonal summand and
then, for all \(A\in M_{m_\ell }(\mathbb {C})\) and \(B\in M_{d_\ell }(\mathbb {C})\),
This is the full-support specialization of HJPW Property \(2'\) (Appendix A, lines 808–816 and 860–882), with the tensor factors reversed. It does not include the joint-support reduction or the Stinespring form of Property 2.
Let \(T_0,\mu ,r\ge 0\) and \(v,K\in \mathbb {R}\) satisfy (340). For every \(b\ge 0\), \(L\ge 1\), and \(C\ge 0\), put \(B_*=1+b+\log L\) and \(\ell =\max \{ 0,\lceil KB_*\rceil \} \), the least nonnegative integer at least \(KB_*\). Then
Let \(T_0\ge 0\), \(v\ge 0\), \(\mu {\gt}0\), and \(r\ge 0\) be real. There is a constant \(K{\gt}0\), depending only on these four parameters, such that
Let \(T_0{\gt}0\), \(v\ge 0\), \(\mu {\gt}0\), and \(r\ge 0\) be real. There is one \(K{\gt}0\) satisfying (340) such that, for every \(b\ge 0\), \(L\ge 1\), and \(C\ge 0\), the choices \(B_*=1+b+\log L\) and \(\ell =\lceil KB_*\rceil \) satisfy \(\ell \ge 1\), \(KB_*\le \ell {\lt}KB_*+1\), and (341).
Under the same assumptions, \(\rho (P_L\otimes \mathbb {1}_R)=\rho \). For \(H_L=H_A\otimes H_X\) and \(H_R=H_B\), the two absorption identities are precisely the \(P_{AX}\) support-projector identities in [ CPGSV16 , Appendix D.2, lines 2228–2235 ] .
Let \(A:\mathbb {R}\to \mathcal M\) be continuously differentiable, and let \(M\ge 0\) satisfy \(\| A(s)\| \le M\) for every \(s\in \mathbb {R}\). For every \(X_0\in \mathcal M\), there is a differentiable path \(U:\mathbb {R}\to \mathcal M\) with \(U(0)=X_0\) such that, for every \(t\in \mathbb {R}\),
For a positive semidefinite matrix \(H\), \(\| H\| \le \operatorname{tr}H\). For a rectangular matrix \(B\), \(\| B\| ^2\le \operatorname{tr}(B^\dagger B)\).
For \(d_C\ge 1\), the matrix \(\tau _C=d_C^{-1}\mathbb {1}_C\) is positive definite and has trace one.
Let \(V\) be finite-dimensional and let \(f:V\to V\) have bounded orbits. For every \(x\in V\), the Cesàro averages satisfy
Moreover,
and \(P_fx=x\) if and only if \(fx=x\). The complex matrix specialization underlying [ Wol12 , Equation (6.14) ] is given below.
- LinearMap.HasBoundedOrbits.tendsto_birkhoffAverage_meanErgodicProjection
- LinearMap.HasBoundedOrbits.range_meanErgodicProjection
- LinearMap.HasBoundedOrbits.meanErgodicProjection_apply_eq_self_iff
- LinearMap.HasBoundedOrbits.isIdempotentElem_meanErgodicProjection
- LinearMap.HasBoundedOrbits.meanErgodicProjection_apply_meanErgodicProjection
- LinearMap.HasBoundedOrbits.comp_meanErgodicProjection
- LinearMap.HasBoundedOrbits.meanErgodicProjection_comp
Under the hypotheses of Theorem 10.9.15, the mean-ergodic projection of \(T\) satisfies
Consequently,
Here each summand is written on \(\mathbb {C}^{m_k}\otimes \mathbb {C}^{d_k}\), so \(\operatorname{tr}_{m_k}\) traces the first factor. This is the full-support part of Equation (6.63) in [ Wol12 , Theorem 6.14 ] ; the density matrices are not yet asserted to be positive definite.
Let \(A\) and \(B\) be positive semidefinite, with \(P_A\) and \(P_B\) the orthogonal projections onto their respective ranges. Then
Here the logarithm is extended by zero on the kernel. Neither matrix is required to be positive definite, and either index set may be empty. This auxiliary identity is project-derived rather than a theorem of CPSV16.
Let \(A\) and \(B\) be positive semidefinite, and let \(f\colon \mathbb {R}\to \mathbb {R}\) be multiplicative on the non-negative reals. Then
Let \(\rho _{AB}\) be a bipartite density operator and let \(\Phi _A\) and \(\Psi _B\) be trace-preserving completely positive maps whose input and output matrix algebras may have different dimensions. Then \(I(A':B')_{(\Phi _A\otimes \Psi _B)(\rho )}\leq I(A:B)_\rho \).
Let \(\rho _{AB}\) be a bipartite density operator and let \(\Phi _A\) be a trace-preserving completely positive map whose input and output matrix algebras may have different dimensions. Then \(I(A':B)_{(\Phi _A\otimes \operatorname{id}_B)(\rho )}\leq I(A:B)_\rho \).
Let \(\rho _{AB}\) be a bipartite density operator and let \(\Psi _B\) be a trace-preserving completely positive map whose input and output matrix algebras may have different dimensions. Then \(I(A:B')_{(\operatorname{id}_A\otimes \Psi _B)(\rho )}\leq I(A:B)_\rho \).
Let \(\rho _{AB}\succeq 0\) be a finite-dimensional bipartite operator with \(\operatorname{tr}\rho _{AB}=1\). Then
No positive-dimension or faithful-marginal hypothesis is required. The operator-Schmidt rank is the ordinary operator-Schmidt rank.
For any tripartite density matrix \(\rho _{ABC}\) on \(A \otimes B \otimes C\),
where the left-hand side is the bipartite mutual information of the reduced state \(\rho _{AB} = \operatorname{tr}_C(\rho _{ABC})\) and the right-hand side is evaluated by expanding \(I(A{:}BC) = S(\rho _A) + S(\rho _{BC}) - S(\rho _{ABC})\).
Write \(\rho _{ij}\in M_{d_B}(\mathbb {C})\) for the blocks determined by a basis of the first factor, and define \(\mathcal R_\rho (X)=\sum _{i,j}X_{ij}\rho _{ij}\). Then
Let \(V_A:\mathcal H_A\to \mathcal K_A\) and \(V_B:\mathcal H_B\to \mathcal K_B\) be isometries between finite-dimensional complex spaces. For every operator \(X\) on \(\mathcal H_A\otimes \mathcal H_B\),
This remains valid when one or more of the spaces have dimension zero.
Let \(\rho \geq 0\) be an operator on \(H_A\otimes H_B\). Let \(V_A:\widehat H_A\to H_A\) and \(V_B:\widehat H_B\to H_B\) be isometries whose range projectors are the support projectors \(P_A\) and \(P_B\) of the two marginals. Set \(W=V_A\otimes V_B\) and \(\rho _c=W^\dagger \rho W\). Then
No marginal is required to be faithful, and zero-dimensional coordinate spaces are permitted.
Let \(\rho \) be any matrix on the common space, and let \(\rho _{QC}=\operatorname {Tr}_{VR}\rho \) and \(\rho _{VR}=\operatorname {Tr}_{QC}\rho \). For all real \(a,b\),
The matrix need not be normalized, invariant under copy permutations, or independent between the two pairs. The identities are complex trace equalities, and hence also hold for their real parts.
Let \(e:K\simeq C\times R\), where \(R\) is finite. For arbitrary matrices \(A\) and \(B\) on the first factor and on \(K\), respectively, the partial trace on the \(R\) coordinate satisfies
where the coordinates of \(B\) are changed by \(e\) on both sides.
Let \(\sigma \) be positive semidefinite on \(H_L\otimes H_R\), and let \(\rho \) be any matrix on the same space such that \(\ker \sigma \subseteq \ker \rho \). Then
Let \(\rho \) and \(\sigma \) be positive semidefinite matrices on \(H_L\otimes H_R\) such that \(\ker \sigma \subseteq \ker \rho \). Then
Let \(X\) be a matrix on \(H_L\otimes H_R\), let \(w\in H_L\), and let \((e_r)_r\) be the distinguished orthonormal basis of \(H_R\). Then
Let \(\rho \) and \(\sigma \) be positive semidefinite matrices satisfying \(\ker \sigma \subseteq \ker \rho \), and suppose that
Fix a primitive \(d_C\)-th root of unity, put \(U_g=\mathbf1\otimes W_g\), and define the unweighted Weyl family
Then, for every Weyl index \(g\) and every \(t{\gt}0\),
In particular, the zero Weyl index gives the projected resolvent of the original pair \((\rho ,\sigma )\). No ambient resolvent equality is asserted. The support convention is that of Jenčová–Ruskai, arXiv:0903.2895v4, lines 717–720, and their common-resolvent equality argument is at lines 766–793. This is one analytic step toward the recovery implication of Hayden–Jozsa–Petz–Winter, Theorem 3 and equation (8); it is not the direct-sum Markov decomposition invoked in CPSV16, Lemma Lsigma3.
Let \(\rho \) and \(\sigma \) be positive definite and suppose that \(D(\rho \Vert \sigma ) =D(\operatorname{tr}_C\rho \Vert \operatorname{tr}_C\sigma )\). Put
Then
Hence the raw partial-trace Petz map satisfies \(\mathcal R_\sigma (\operatorname{tr}_C\rho )=\rho \). This is the positive-definite case only; no singular-support conclusion is asserted.
In the finite Weyl coordinates \(\mathbb C^{d_S}\otimes \mathbb C^{\mathbb Z/d_C\mathbb Z}\), let \(\rho \) and \(\sigma \) be positive semidefinite matrices satisfying \(\ker \sigma \subseteq \ker \rho \), and suppose that
Put
If \(P_\sigma \) is the orthogonal projection onto \((\ker \sigma )^\perp \), then
Consequently, \(\mathcal R_\sigma (\operatorname{tr}_C\rho )=\rho \) for the raw support Petz map. The projected relative-modular argument follows Jenčová–Ruskai, arXiv:0903.2895v4, lines 766–793, and the recovery formula is [ HJPW04 , Theorem 3, equation (8) ] . This result does not assert the middle-space direct-sum decomposition in [ CPGSV16 , Lemma Lsigma3, lines 1351–1363 ] .
Let \(\rho \) and \(\sigma \) be positive definite, and suppose that \(D(\rho \Vert \sigma )=D(\operatorname{tr}_C\rho \Vert \operatorname{tr}_C\sigma )\). For the uniformly weighted Weyl conjugates \(A_g=d_C^{-2}U_g\rho U_g^\dagger \) and \(B_g=d_C^{-2}U_g\sigma U_g^\dagger \), put \(A=\sum _gA_g\) and \(B=\sum _gB_g\). Then
For matrices \(M_0,\ldots ,M_{m-1}\) on \(A\), their tensor product in the preceding coordinates satisfies
The formula includes \(m=0\) and requires no positivity or normalization. It is the tensor-product identity used in [ Ope26b , Section 8, lines 550–560 ] .
Let \(x,\rho \in \mathbb {C}^{I\times I}\) be commuting positive semidefinite matrices, \(Q\) an orthogonal projection, and \(C,u,R\in \mathbb {R}\). Assume \(u\ge 0\), \(R\ge (C+\log 8)(1+u)\), \(\rho \le x+e^{-R}\mathbb {1}\), \(\operatorname{rank}Q\le e^{C(1+u)}\), and \(\operatorname{tr}((\mathbb {1}-Q)\rho )\le 1/8\). Then \(T=e^{-R}\rho (x+e^{-R}\mathbb {1})^{-1}\) satisfies \(\operatorname{tr}T\le 1/4\).
The range of \(T_\phi \) is the peripheral subspace, \(T_\phi \) is idempotent, and
On a peripheral \(\mu \)-eigenvector, \(T_\phi \) acts as the identity and \(T_\varphi \) acts as multiplication by \(\mu \). These are [ Wol12 , Equations (6.12) and (6.13) ] .
- Module.End.range_peripheralProjection
- Module.End.isIdempotentElem_peripheralProjection
- Module.End.peripheralProjection_comp
- Module.End.peripheralWeightedProjection_eq_comp
- Module.End.peripheralWeightedProjection_eq_peripheralProjection_comp
- Module.End.peripheralProjection_apply_of_mem_eigenspace
- Module.End.peripheralWeightedProjection_apply_of_mem_eigenspace
Let \(\rho \) and \(\sigma \) be density operators on the finite-dimensional product \(H_L\otimes H_R\) such that \(\ker \sigma \subseteq \ker \rho \). If
then the completed partial-trace Petz channel associated with \(\sigma \) recovers \(\rho \):
This is the right-partial-trace forward implication of [ HJPW04 , Theorem 3, equation (8) ] . The additional off-support term belongs to the trace-preserving completion and vanishes on \(\operatorname{tr}_R\rho \); it is not part of the formula in the cited equation.
For an arbitrary real function \(f\) and independently chosen real label functions \(g_A\), with \(A\in \{ QC,VR,C,R\} \), write \(L_A(g_A)=\sum _\lambda g_A(\lambda )\Pi _A^\lambda \). Then
In particular, \(J\) commutes with both merge deficits.
Set \(D_{QV}=F_Q+F_V-F_{QV}\) and \(J=\mathbf1_{[0,\infty )}(G_{\mathrm{phys}})\). Then
Zero copies and zero-dimensional factors are included.
The partial swap is a Hermitian unitary and has operator norm at most one. Its compression \(W\) is Hermitian for every \(V\). If \(V^\dagger V=I\), then \(\| W\| \le 1\).
- Matrix.partialSwap_isHermitian
- Equiv.partialSwap_symm
- Equiv.partialSwap_mul_self
- Matrix.partialSwap_mul_self
- Matrix.partialSwap_mem_unitaryGroup
- Matrix.norm_partialSwap_le_one
- Matrix.kronecker_self_conjTranspose_mul_self
- Matrix.compressedPartialSwap_isHermitian
- Matrix.norm_conjTranspose_mul_mul_le_of_isometry
- Matrix.norm_compressedPartialSwap_le_one
Let \(\Omega \in \mathcal H_R\otimes \mathcal H_C\otimes \mathcal H_Q\) be normalized, and let \(\rho _{RC}\) be its reduced state, with marginals \(\rho _R,\rho _C\). Suppose \(b\ge 0\) and \(D(\rho _{RC}\Vert \rho _R\otimes \rho _C)\le b\). Set \(\Psi =\Omega ^{\otimes 2}\) and \(\Phi =F_R\Psi \), grouping the two \(RC\) registers before the two \(Q\) registers. There exist a Hermitian operator \(W\) on the original doubled buffer \(\mathcal H_Q^{\otimes 2}\) with \(\| W\| \le 1\) and a real number \(z\) such that
This is the physical-buffer overlap construction in [ Ope26b ] .
Under the original-system hypotheses of Theorem 13.30.4.2, suppose \(\Delta {\gt}0\), \(b\ge 0\), and \(D(\rho _{RC}\Vert \rho _R\otimes \rho _C)\le b\), where \(\rho _{RC}=\operatorname {Tr}_Q|\Omega \rangle \! \langle \Omega |\). There are a Hermitian contraction \(W\) on \(\mathcal H_Q^{\otimes 2}\) and a real number \(z\ge e^{-2b}\) such that, with \(V=I_{(RC)^{\otimes 2}}\otimes W\), \(\langle \Phi ,V\Psi \rangle =z\). The same \(W,z\) satisfy the following statements for every \(h\ge 0\) and \(T\ge 0\). For the actual integrals \(M_h=M_h(\mathbb H',\mathbb H;V)\) and \(M_h^T=M_h^T(\mathbb H',\mathbb H;V)\),
For \(h{\gt}0\), \(\tau _h(T)=2e^{-T^2/(2h)}\). At \(h=0\), the probability integral gives \(M_0=V\) and the displayed bounds use \(\tau _0(T)=2\).
Let \(T\) be a reference register, \(F\) a Hermitian operator on \(\mathcal H_T\), and \(x,y\in \mathcal H_T\otimes \mathcal H_Q^{\otimes 2}\). Write \(\widetilde x=(I_T\otimes K)x\) and \(\widetilde y=(I_T\otimes K)y\). Then
This is an equality of complex numbers. Neither normalization nor an isometry hypothesis is needed.
For any \(\chi \in \mathcal H_L\otimes \mathcal H_M\) and unit vectors \(a\in \mathcal H_L\), \(a^{\prime }\in \mathcal H_M\), put \(\sigma _L=\operatorname {Tr}_M\vert \chi \rangle \langle \chi \vert \). Then
and the exact complex swap identity is
No normalization of \(\chi \) is required.
Let \(V:\mathcal H_Q\to \mathcal H_X\otimes \mathcal H_Y\) be any linear map, let \(\chi =(I_{RC}\otimes V)\Omega \), and view \(\chi \) across \(RX\mid CY\). Put \(\sigma =\operatorname {Tr}_{CY} \vert \chi \rangle \langle \chi \vert \) and use \(W=(V\otimes V)^\dagger F_X(V\otimes V)\). Then
Regrouping preserves inner products, \(\| \Psi \| ^2=\| \Omega \| ^4\), and a tensor product of two unit purifications is again a unit vector.
- Matrix.physicalLeftSwap_compressedPartialSwap_overlap_eq_purity
- Matrix.one_kronecker_mulVec_apply
- Matrix.doubledRegroup_one_kronecker_mulVec
- Matrix.star_doubledRegroup_dotProduct
- Matrix.star_regroupPurification_dotProduct
- Matrix.star_tensorPurification_dotProduct_eq_one
- Matrix.physicalLeftSwap_eq_mulVec
- Matrix.star_doubledRegroup_dotProduct_partialSwaps_eq_purity
- Matrix.partialSwap_kronecker_mulVec
- Matrix.partialSwap_one_mulVec
Suppose \(\| \Omega \| =1\), \(H\Omega =E_0\Omega \), \(\Delta \ge 0\), and \(H-E_0I-\Delta (I-|\Omega \rangle \! \langle \Omega |)\succeq 0\). For the operators and vectors in (325), both generators are Hermitian, \(\| \Psi \| =\| \Phi \| =1\), and
If \(\| \Omega \| =1\), then the three original marginals satisfy
The marginals may be singular. This is the nonnegativity of the physical entropy difference used in [ Ope26b , Section 8 ] .
Let \(\rho _{ABC}\) have trace one and suppose that, after reassociating the tensor factors, it factors as
Here the two factors act through their natural overlapping lifts. Then \(\rho _{ABC}\) admits a quantum Markov decomposition on the middle system \(B\).
Let \(H\) be positive semidefinite on a finite-dimensional complex Hilbert space, let \(S\) be a finite set, and let \((v_i)_{i\in S}\) be any vectors. Then
Suppose \(R\ge 0\), \(\Delta {\gt}0\), and \(\| \Omega \| =1\). Every vector \(\psi \) satisfying \(H\psi =E_0\psi \) obeys \(\psi =\langle \Omega ,\psi \rangle \Omega \). The vector \(\psi \) may be zero or unnormalized; no eigenvector equation on \(\Omega \) is required for this projection identity. If also \(H\Omega =E_0\Omega \), then
If \(P\ge 0\), then for all \(x,y\in \mathcal H\),
Let \(T:M_{D}(\mathbb {C})\to M_{D}(\mathbb {C})\) be positive and trace-preserving. The trace adjoint \(P_T^*\) of its mean-ergodic projection is positive, unital, and idempotent. It is a retraction onto the adjoint fixed-point space:
and \(P_T^*(Y)=Y\) if and only if \(T^*(Y)=Y\). This is the adjoint projection used in the proof of [ Wol12 , Theorem 6.14 ] .
Suppose \(p_j{\gt}0\) and \(L_j\leq R_j\) for every \(j\). If \(\sum _jp_jL_j=\sum _jp_jR_j\), then \(L_j=R_j\) for every \(j\). This is the positivity argument applied to strong subadditivity in [ CPGSV16 , Appendix C.2, lines 1770–1780 ] .
Let \(\rho _{AB}\succeq 0\), with marginals \(\rho _A\) and \(\rho _B\). Then
Equivalently, the support of \(\rho _{AB}\) is contained in \(\operatorname{supp}(\rho _A)\otimes \operatorname{supp}(\rho _B)\). This remains valid when either factor has dimension zero.
Let \(P:\mathcal M\to \mathcal M\) be complex linear, preserve Hermitian matrices, and satisfy \(\| P(X)\| \le \| X\| \) for every \(X\in \mathcal M\). For every pair of Hermitian matrices \(H^{\prime },H\in \mathcal M\), put
There is a differentiable path \(U:\mathbb {R}\to \mathcal M\) with \(U(0)=I\) such that, for every \(s\in \mathbb {R}\),
Every differentiable path \(W:\mathbb {R}\to \mathcal M\) with \(W(0)=I\) and \(W^{\prime }(s)=iG_P(s)W(s)\) for every \(s\in \mathbb {R}\) equals \(U\). The same path \(U\) satisfies the following estimate simultaneously for every \(t,\varepsilon \in \mathbb {R}\): if \(\| G(s)-G_P(s)\| \le \varepsilon \) for every \(s\in J_t\), then
Let \(P:\mathcal M\to \mathcal M\) be complex linear with \(\| P(X)\| \le \| X\| \) for every \(X\in \mathcal M\). For every Hermitian matrix \(H\in \mathcal M\), every matrix \(B\in \mathcal M\), and every \(t\in \mathbb {R}\),
Neither Hermiticity of \(B\) nor Hermitian preservation by \(P\) is required for this bound.
Let \(P:\mathcal M\to \mathcal M\) be complex linear and satisfy \(P(X)^\dagger =P(X)\) for every Hermitian matrix \(X\). For every pair of Hermitian matrices \(H,B\in \mathcal M\) and every \(t\in \mathbb {R}\), the matrix \(G_{P,H,B}(t)\) is Hermitian.
For every \(H\in \mathcal M\) and every differentiability order \(k\in \mathbb {N}\cup \{ \infty ,\omega \} \), the path \(t\mapsto e^{itH}\) is \(C^k\), where \(C^\omega \) denotes real analyticity. For every complex-linear map \(P:\mathcal M\to \mathcal M\), every \(H,B\in \mathcal M\), and every such \(k\), the path \(G_{P,H,B}\) is \(C^k\). Hermiticity, Hermitian preservation, and contractivity are not needed for these regularity assertions.
Let \(P:\mathcal M\to \mathcal M\) be complex linear, preserve Hermitian matrices, and satisfy \(\| P(X)\| \le \| X\| \) for every \(X\in \mathcal M\). For every pair of Hermitian matrices \(H,B\in \mathcal M\), there is a differentiable path \(U:\mathbb {R}\to \mathcal M\) with \(U(0)=I\) such that, for every \(t\in \mathbb {R}\),
For every path \(V:\mathbb {R}\to \mathcal M\), if \(V(0)=I\) and \(V\) is differentiable with \(V^{\prime }(t)=iG_{P,H,B}(t)V(t)\) for every \(t\in \mathbb {R}\), then \(V=U\).
Let \(\rho \in M_{d}(\mathbb {C})\) be a density matrix and let \(P_1,\ldots ,P_k\in M_{d}(\mathbb {C})\) be orthogonal projections satisfying \(\sum _{i=1}^k P_i=\mathbb {1}\). Define
Then
This is [ Wol12 , Chapter 8, Eq. (8.56) ] .
For every orthogonal projector \(P\) on \(\mathcal H_R^{\otimes k}\),
In particular, taking \(P\) to be an actual central Schur projector gives the squared norm in that sector.
Let \(\psi \in \mathbb {C}^A\otimes \mathbb {C}^R\) and \(\varphi \in \mathbb {C}^A\otimes \mathbb {C}^S\) be unit purifications of \(\rho \) and \(\sigma \), with \(\ker \sigma \subseteq \ker \rho \), and suppose \(\dim \mathbb {C}^S\ge \dim \mathbb {C}^A\) and \(\dim \mathbb {C}^S\ge \dim \mathbb {C}^R\). There is an isometry \(V:\mathbb {C}^R\to \mathbb {C}^S\) with
Without the dimension conditions, the same holds with \(\varphi \) replaced by its zero extension \(\widehat\varphi \) to \(\mathbb {C}^A\otimes (\mathbb {C}^S\oplus \mathbb {C}^A\oplus \mathbb {C}^R)\) and \(V\) taking values there.
Let \(\Omega \in (\mathbb {C}^T\otimes \mathbb {C}^E)\otimes \mathbb {C}^U\) be a unit vector with reduced state \(\rho _{TE}\), and let \(b=I(T{:}E)\). There are an isometry \(V:\mathbb {C}^U\to \mathbb {C}^T\otimes (\mathbb {C}^E\oplus \mathbb {C}^U)\) and unit vectors \(s\in \mathbb {C}^T\otimes \mathbb {C}^T\) and \(s'\in \mathbb {C}^E\otimes (\mathbb {C}^E\oplus \mathbb {C}^U)\) with
If moreover \(L{\gt}0\) and \(b\le L^{-60}\), the error is at most \(L^{-30}\). This is [ Ope26a , Lemma 6.4 ] .
Let \(T,T':M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) be trace-preserving and Hermiticity-preserving linear maps with \(T'(X)=\operatorname{tr}[X]\, Y\) for some fixed \(Y\in M_{D'}(\mathbb {C})\). If \(T-\varepsilon T'\) is positive for some \(\varepsilon \geq 0\), then for all density operators \(\rho _1,\rho _2\in M_{D}(\mathbb {C})\),
See [ Wol12 , Chapter 8, Theorem 8.17 ] .
For \(a\le b\le c\), one has \(F_{a:c}=F_{a:b}\circ F_{b:c}\). Complete positivity, and trace preservation when present, are retained. For Kraus maps \(E_i(X)=\sum _s A_i^sX(A_i^s)^\dagger \),
Shifting all cut indices by one common offset shifts the selected interval. Identifying equal dimensions does not change the channel property.
- Matrix.channelInterval_self
- Matrix.channelInterval_succ
- Matrix.channelInterval_single
- Matrix.channelInterval_succ_left
- Matrix.channelInterval_comp
- Matrix.channelInterval_shift
- Matrix.channelInterval_isKrausCP
- Matrix.channelInterval_isKrausCPTP
- Kraus.rectangularTransfer_apply
- Kraus.rectangularTransfer_eq_channelInterval
- Matrix.isKrausCPTP_rectangularKrausMap_finCast
If \(\mathcal L:M_{d}(\mathbb {C})\to M_{e}(\mathbb {C})\) is a Hilbert–Schmidt contraction, then
Let \(F:M_{b}(\mathbb {C})\to M_{a}(\mathbb {C})\) preserve trace, let \(b{\gt}0\), and let \(\operatorname{tr}\tau =1\). If \(J(F)\ge (\eta /b)(\tau \otimes I_b)\), then \(F-\eta R_\tau \) is completely positive, scales trace by \(1-\eta \), and \(\eta \le 1\).
More generally, let \(F\) be linear and let a completely positive \(Q\) satisfy \(\operatorname{tr}Q(X)=t\operatorname{tr}X\), \(t\ge 0\), and \(Q(X)=F(X)\) on traceless matrices. For every input density \(\rho \),
Suppose \(D_0{\gt}0\), \(D_N=D_0\), and all \(N\) site maps are trace preserving. There are density matrices \(\sigma _a\in M_{D_a}(\mathbb {C})\), for \(0\le a\le N\), with \(\sigma _N=\sigma _0\) under the closing identification and \(F_{a:b}(\sigma _b)=\sigma _a\) for \(a\le b\le N\). No faithful density or common stationary matrix is assumed.
Let \(Q:M_{b}(\mathbb {C})\to M_{a}(\mathbb {C})\) be completely positive, with \(b{\gt}0\), and suppose \(\operatorname{tr}Q(X)=t\operatorname{tr}X\) for a real \(t\ge 0\). Then \(\| Q\| _{2\to 2}\le bt\). Taking coefficient matrices commutes with subtraction. Identifying equal input or output dimensions preserves this norm and trace-prepare errors.
Let \(D_i{\gt}0\) for \(0\le i\le N\), let every site map preserve trace, and fix \(s\ge 1\) and \(\eta \le 1\). Suppose every nonwrapping \(s\)-window has a density \(\tau _a\) with
Every interval \([a,b)\) has a completely positive residual \(Q\) agreeing with \(F_{a:b}\) on traceless inputs and having trace scale \(t=(1-\eta )^{\lfloor (b-a)/s\rfloor }\). For every density \(\rho \in M_{D_b}(\mathbb {C})\),
Suppose \(Q\) and \(Y\) are disjoint, and fix any two finite auxiliary coordinate sets \(C,R\). Let \(e_{Q,Y}\) be restriction of configurations to \(Q\), \(Y\), and \((Q\cup Y)^c\), in that order, and put \(\psi =\Omega \circ e_{Q,Y}^{-1}\). In the five-factor coordinates \((\mathcal B_Q,\mathcal B_Y,\mathcal B_{(Q\cup Y)^c},C,R)\), the three physical singleton reductions of \(|\psi \rangle \langle \psi |\) satisfy
These are the original physical marginals used in the component estimates of [ Ope26b , Section 8 ] .
Under the hypotheses of Theorem 13.77.2, let \(j\in \{ 0,1,2\} \). For a positive semidefinite matrix \(\rho \) with eigenvalues \(\lambda _a\), define
A zero eigenvalue contributes zero to both expressions. For every real \(v\),
For positive definite matrices \(\rho ,\sigma \) and a positive definite matrix \(\tau \) of unit trace,
Let \(\rho \) and \(\sigma \) be positive semidefinite matrices such that \(\ker \sigma \subseteq \ker \rho \), and let \(\tau \) be positive semidefinite with \(\operatorname{tr}\tau =1\). Then
For positive definite matrices \(\rho ,\sigma \) on a tensor product of a system factor and an ancilla factor,
where \(\operatorname{tr}_C\) is the partial trace over the ancilla factor. This is the positive-definite base case; the source inequality on the support domain \(\ker \sigma \subseteq \ker \rho \) is Theorem 13.6.35.
For positive semidefinite \(\rho ,\sigma \) on a tensor product of a system factor and an ancilla factor of dimension \(d_C\), with the support condition \(\ker \sigma \subseteq \ker \rho \),
where \(\operatorname{tr}_C\) is the partial trace over the ancilla factor.
Let \(A\) and \(B\) be Hermitian matrices of the same size, with spectral resolutions
Write \(w_{ij}=\langle u_i,v_j\rangle \), and use the total real logarithm: \(\log 0=0\), while \(\log x=\log |x|\) for \(x{\lt}0\). Then
This is an algebraic totalized extension to arbitrary Hermitian matrices of the homogeneous trace-log identity \((\mathrm{J1})\), which Jenčová–Ruskai state for strictly positive matrices in arXiv:0903.2895v4, lines 277–287.
For every positive semidefinite operator \(\omega _{XY}\),
No invertibility assumption is made on either marginal. This is [ HJPW04 , Equation (4) ] .
Let \(\rho ,\omega \in M_{D}(\mathbb {C})\) be positive semidefinite matrices of trace one with \(\ker \omega \subseteq \ker \rho \). Assume that for every dimension and every pair of trace-one matrices \(A\succeq 0\) and \(B\succ 0\),
Then
Thus this theorem reduces the singular-reference case to the faithful comparison. Theorem 13.17.14 supplies the hypothesis in (228).
Let \(\rho ,\omega \in M_{D}(\mathbb {C})\) satisfy \(\rho \succeq 0\), \(\omega \succ 0\), and \(\operatorname{tr}\rho =1\). Then
No normalization of \(\omega \) is required.
Let \(\rho ,\omega \in M_{D}(\mathbb {C})\) be positive semidefinite matrices of trace one. If \(\ker \omega \subseteq \ker \rho \), then
Let \(A\) and \(B\) be positive definite, with spectral resolutions \(A=\sum _i\alpha _i|u_i\rangle \! \langle u_i|\) and \(B=\sum _j\beta _j|v_j\rangle \! \langle v_j|\). Put \(w_{ij}=\langle u_i,v_j\rangle \). Let \(L_A\) and \(R_B\) denote left and right multiplication, \(L_A(X)=AX\) and \(R_B(X)=XB\). Then, for \(t{\gt}0\),
Both quadratic forms are continuous on \((0,\infty )\). Moreover,
and the integrand in (153) is continuous and integrable on the positive half-line. This is the positive-definite spectral route of Jenčová–Ruskai, arXiv:0903.2895v4, §4.
- Matrix.sourceAResolventQuadratic
- Matrix.sourceBResolventQuadratic
- Matrix.leftRight_mulVec_vec_transpose
- Matrix.sourceA_resolvent_quadratic_spectral
- Matrix.sourceB_resolvent_quadratic_spectral
- Matrix.sourceAResolventQuadratic_continuousOn
- Matrix.sourceBResolventQuadratic_continuousOn
- Matrix.quantumRelativeEntropy_posDef_spectral
- Matrix.relativeEntropyResolventIntegrand
- Matrix.relativeEntropyResolventIntegrand_integrableOn
- Matrix.relativeEntropyResolventIntegrand_continuousOn
- Matrix.quantumRelativeEntropy_resolvent_integral
Let \(\rho ,\omega \in M_{D}(\mathbb {C})\) be positive semidefinite with \(\ker \omega \subseteq \ker \rho \). Let \(V:\mathbb {C}^k\to \mathbb {C}^D\) satisfy
Then
The logarithm is totalized by \(\log 0=0\) on the kernel.
Let \(A\) and \(B\) be positive semidefinite matrices of the same size, let \(P_B\) be the orthogonal projection onto the support of \(B\), and, for \(t{\gt}0\), set
Write \(S_t^+\) for the generalized inverse that vanishes on \(\ker S_t\). Define
With the spectral notation of Theorem 13.8.15,
Consequently,
The function in (141) is continuous on \((0,\infty )\). If \(\ker B\subseteq \ker A\), then \(A P_B=A\), so \(Q_{A P_B}(t)\) equals the quadratic form with source \(\operatorname{vec}(A^{\top })\).
This is the support-projected form of \((\mathrm{intAB})\) in Jenčová–Ruskai, arXiv:0903.2895v4, §2.1, lines 423–427, with the support convention at lines 717–720.
- Matrix.PosSemidef.supportInv
- Matrix.supportLeftRightSuperoperator
- Matrix.supportSourceAQuadratic
- Matrix.rawSupportSourceAQuadratic
- Matrix.supportSourceBQuadratic
- Matrix.supportRelativeEntropyLeftRightIntegrand
- Matrix.supportLeftRight_sourceA_solution
- Matrix.supportSourceAQuadratic_spectral
- Matrix.supportSourceBQuadratic_spectral
- Matrix.supportRelativeEntropyLeftRightIntegrand_eq_spectral
- Matrix.supportSourceAQuadratic_eq_raw_of_kernel_le
- Matrix.rawSupportSourceAQuadratic_sub_trace_add_sourceB_eq_spectral
- Matrix.supportRelativeEntropyLeftRightIntegrand_continuousOn
Let \(A\) and \(B\) be positive semidefinite matrices of the same size and suppose that \(\ker B\subseteq \ker A\). With the spectral notation of Theorem 13.8.14, define, for \(t{\gt}0\),
Thus no ordinary quotient with \(\alpha _i=\beta _j=0\) is used. Define also
The function \(I_{A,B}\) is integrable on \((0,\infty )\), and
The trace-log identity \((\mathrm{J1})\), the scalar normalization \((\mathrm{intspec})\), and its matrix form \((\mathrm{intAB})\) occur in Jenčová–Ruskai, arXiv:0903.2895v4, at lines 277–287, 406–413, and 423–427, respectively. The support-domain extension is given at lines 717–720.
This theorem concerns the spectral expression \(I_{A,B}\). The next theorem identifies it with the coordinate-free left-right quadratic form underlying the finite Weyl formula.
For Hermitian matrices \(\rho ,\sigma \) and a unitary \(U\),
Let \(\rho \) and \(\sigma \) be positive semidefinite matrices on \(\mathcal{H}_S\otimes \mathbb {C}^{d_C}\) such that \(\ker \sigma \subseteq \ker \rho \), and suppose that \(D(\rho \Vert \sigma )=D(\operatorname{tr}_C\rho \Vert \operatorname{tr}_C\sigma )\). For a primitive \(d_C\)-th root of unity, put \(U_{ab}=\mathbb {1}_S\otimes W(a,b)\) and
Then, for every \(a,b\),
This is a scalar equality-propagation prerequisite for [ HJPW04 , Theorem 3 and equation (8) ] ; it neither characterizes equality in joint convexity nor asserts recovery.
Let \(\rho \) and \(\sigma \) be positive semidefinite matrices on \(\mathcal{H}_S\otimes \mathbb {C}^{d_C}\) such that \(\ker \sigma \subseteq \ker \rho \), and suppose that \(D(\rho \Vert \sigma )=D(\operatorname{tr}_C\rho \Vert \operatorname{tr}_C\sigma )\). For a primitive \(d_C\)-th root of unity, put \(U_{ce}=\mathbb {1}_S\otimes W(c,e)\) and
Then
This scalar identity is associated with the finite Jensen step in the Weyl proof of data processing. It is a prerequisite for [ HJPW04 , Theorem 3 and equation (8) ] ; it neither characterizes equality in joint convexity nor asserts recovery.
Let \(G,H,U,V:\mathbb {R}\to \mathcal M\). Suppose \(G(s)^\dagger =G(s)\) for every \(s\in \mathbb {R}\), and that \(U,V\) are differentiable with \(U^{\prime }(s)=iG(s)U(s)\) and \(V^{\prime }(s)=iH(s)V(s)\) for every \(s\in \mathbb {R}\). Then, for every \(t\in \mathbb {R}\),
There is no continuity assumption on \(G,H\), no Hermiticity assumption on \(H\), and no initial-value condition.
Suppose \(H\Omega =E_0\Omega \), where \(E_0\in \mathbb R\), and \(k{\gt}0\). For every finite-dimensional auxiliary space \(\mathcal K\) and every \(w\in \mathcal K\), \((\overline H\otimes I_{\mathcal K})(\Omega ^{\otimes k}\otimes w) =E_0\Omega ^{\otimes k}\otimes w\). Neither vector is required to be normalized.
For every real function \(f\) on the spectrum of \(N\) and every \(\sigma \in S_k\), \(f(N)U_\sigma =U_\sigma f(N)\). In particular, the closed spectral cutoff \(P_t=\mathbf1_{(-\infty ,t]}(N)\) commutes with every physical copy permutation.
For every real \(b\leq 1\),
This is the unnormalized form of the first exponential moment in [ Ope26b , Section 7, equation (comparator:merge-moments) ] . It includes \(w=0\), \(m=0\) and \(k=0\).
Let \(k,r\) be nonnegative integers with \(r\leq k\). Suppose that \(0\leq \tau \leq \frac12\), \(r\leq \tau k\), and \(a,d,g,K,\Lambda \geq 0\). Let \(C,S,\varepsilon ,L\in \mathbb R\) satisfy \(2kS-\varepsilon \leq L\). Write \(h\) for binary entropy and \(m=k-r\). Then
Let \(\Omega \in \mathcal H\) be a unit vector, let \(k\ge 0\) be an integer, and let \(\mathcal K\) be any finite-dimensional complex Hilbert space. Let \(N\) be the replica defect count, and let \(R_B\) be the exact excitation projection for \(B\subseteq \{ 0,\ldots ,k-1\} \). Fix \(0\le \tau \le 1/2\), \(c\ge 0\), and a positive semidefinite operator \(H\) on \(\mathcal H^{\otimes k}\otimes \mathcal K\). Set
Suppose \(Q_\tau u=u\) and, for every \(B\) with \(|B|\le \tau k\),
Then, with \(h(\tau )=-\tau \log \tau -(1-\tau )\log (1-\tau )\) and \(0\log 0=0\),
Suppose \(\| \Omega \| =1\) and let \(\mathcal K\) be any finite-dimensional auxiliary space. For \(u\in \mathcal H^{\otimes k}\otimes \mathcal K\), put \(u_B=(R_B\otimes I_{\mathcal K})u\). If \((\mathbf1_{(-\infty ,t]}(N)\otimes I_{\mathcal K})u=u\), then
No normalization of \(u\) is required.
Assume \(\| \Omega \| =1\), \(g{\gt}0\), \(k{\gt}0\), \(\tau {\gt}0\), and \(H-E_0I-g(I-|\Omega \rangle \langle \Omega |)\ge 0\), with \(E_0\in \mathbb R\). Let \(v\in \mathcal H^{\otimes k}\otimes \mathcal K\) be a unit vector, and let \(\Pi =\mathbf1_{(-\infty ,\tau k]}(N)\) be the actual spectral projection. Then
The inner products in (432) are real because the operators are self-adjoint.
Retain the data \(\Omega ,k,\mathcal K,\tau ,c,H,Q_\tau \) above, and let \(P\) be an orthogonal projection satisfying \(Q_\tau P=P\). For each vector \(u\) with \(Pu=u\), set \(u_B=(R_B\otimes \mathbb {1}_{\mathcal K})u\). Suppose that for every such \(u\) and every \(B\) with \(|B|\le \tau k\),
Then
No commutation of \(H\) with \(P\), \(Q_\tau \), or the individual excitation projections is assumed.
For any \(\Omega \), \(\sum _B R_B=I\). If \(\| \Omega \| =1\), each \(R_B\) is an orthogonal projection and \(R_BR_C=0\) whenever \(B\ne C\). All assertions include \(k=0\).
Let \(E_0,g\in \mathbb R\). If \(H-E_0I-g(I-|\Omega \rangle \langle \Omega |)\) is positive semidefinite, then \(H_\Sigma -kE_0I-gN\) is positive semidefinite for every \(k\ge 0\). This assertion requires neither normalization nor an eigenvector equation.
In the preceding definitions, suppose that \(v\) is fixed by every simultaneous copy permutation of \(A^k,C^k,D^k\). Then \(\rho _C^{\mathrm{good}}\) commutes with every copy-permutation operator on \(C^m\). No normalization or independence assumption is made. The vector \(\Omega \) is arbitrary, and zero components and zero copy groups are included.
Suppose \(\| \Omega \| =1\). For any \(u\), let \(u_B=(R_B\otimes I_{\mathcal K})u\). For every \(b,g,c\),
This includes \(k=0\), \(B=\varnothing \), \(B=\{ 0,\ldots ,k-1\} \) and \(u_B=0\).
Retain the same \(\Omega ,u,B,w,f\) and density \(\rho _G\), and let \(m=|B^c|\). For every finite family of subsystems \(S_j\) and real coefficients \(a_j\),
Here the left-hand observables are the actual good-subgroup entropies on the full space; those on the right act on the \(m\) good copies. For \(H_g=F_{QC,g}+F_{VR,g}-F_{Y,g}-F_{C,g}-F_{R,g}\), \(\Delta _{QC}=F_{Q,m}+F_{C,m}-F_{QC,m}\), \(\Delta _{VR}=F_{V,m}+F_{R,m}-F_{VR,m}\) and \(G_m=F_{Q,m}+F_{V,m}-F_{Y,m}\), this gives
for every real \(a\). These are exact complex equalities, without normalization, symmetry or commutation assumptions on the region family, as used in [ Ope26b , Section 8, lines 454–560 ] .
Let \(\Omega \) and \(u\) be arbitrary physical and full vectors, and put \(w=(R_B\otimes I)u\). Let \(f\) be \(w\) in five-factor coordinates, and let \(\eta \) be the coordinate decomposition into the actual good copies \(B^c\) and bad copies \(B\). The actual five-factor good density \(\rho _G\) satisfies
No normalization or symmetry is assumed.
Let the original one-copy physical vector have norm one, and let the original vector be fixed by simultaneous permutations of the physical and two auxiliary copy registers. Let \(w\) be its excitation component, let \(m\) be the number of good copies, and let \(\rho _G\) be its actual five-factor good density. For every real \(a\leq 1\),
Each deficit is defined from the actual subsystem copy actions, as in Theorem 13.68.2. The component may vanish and \(m\) may be zero. These are the two separate estimates in [ Ope26b , Section 8 ] .
Let \(\rho _G\) be the actual five-factor good-copy density of an excitation component \(w\), and let \(\rho _{\mathrm{pair}}\) be its common good-pair marginal. With the deficits of Theorem 13.68.2, for every real \(a\),
No normalization or permutation invariance is needed for this identity.
Suppose the one-copy physical vector \(\Omega \) has norm one and the original vector \(u\) is fixed by simultaneous permutations of its physical and two auxiliary copy registers. For a subset \(B\) of bad copies, let \(w\) be the corresponding excitation component and \(m=|B^c|\). If \(a\in \mathbb R\) and \(2a\leq 1\), then
The vector \(u\) need not be normalized, and \(w\) may vanish. Negative \(a\) and zero good copies are included. This is the arithmetic-mean consequence of the paired moments in [ Ope26b , Section 8, lines 520–555 ] .
Let \(w\) be the actual excitation component for a subset \(B\) of the copies. Let \(\rho \) be its reduced density retaining all five good factors \(Q_G,Y_G,V_G,C_G,R_G\), and tracing only the bad physical and auxiliary coordinates. In the coordinates of \(e\), denote this matrix by \(\rho _e\). Then \(\rho \) is positive semidefinite,
where \(\rho _{\mathrm{pair}}\) is the actual common good-pair marginal. Neither the original vector nor its component is required to be normalized or permutation invariant. This is the common density used in [ Ope26b , Section 8, lines 513–549 ] .
With the preceding notation,
for every matrix \(H\) on the good physical copies. No normalization or nonvanishing of \(w\), and no positivity of \(H\), is required.
Let \(\Omega \) be a unit vector on the three physical factors \(Q,Y,V\). For an arbitrary original vector, let \(w\) be its excitation component associated to a set \(B\) of bad copies. Write \(G=B^c\) and \(m=|G|\). Let \(\rho _G\) be the actual density retaining the good copies of all five factors \(Q,Y,V,C,R\). After grouping the physical and auxiliary registers,
where \(\eta _G\) is obtained from \(|w\rangle \langle w|\) by tracing all physical copies and all bad auxiliary copies. In particular, \(\operatorname {Tr}\eta _G=\| w\| ^2\). Before tracing the bad auxiliary copies, the same assertion holds with the whole auxiliary marginal in place of \(\eta _G\). This is the product decomposition used in [ Ope26b , Section 8, lines 520–560 ] .
Let \(\Omega \) be a unit one-copy physical vector. Choose any bipartite coordinate decomposition of the original physical space as \(U\otimes T\), and set \(\sigma _U=\operatorname {Tr}_T|\Omega \rangle \langle \Omega |\). Let \(w\) and \(\rho _G\) be as in Theorem 13.73.4, with \(m\) good copies. For every matrix \(H\) on \(U^{\otimes m}\), interpreted as an observable on the same good-copy density by adjoining identities,
All coordinate changes are induced by the chosen bipartite decomposition. This is the regional reduction in [ Ope26b , Section 8, lines 550–560 ] .
Let \(F_{U,m}\) be the label entropy observable for the copy permutations of \(U^{\otimes m}\). For every real \(a\),
The component may vanish; no division by its mass is involved.
Let \(I_0,\ldots ,I_4\) be finite coordinate sets, and let \(\Omega \in \mathbb C^{I_0}\otimes (\mathbb C^{I_1}\otimes \mathbb C^{I_2})\) be a unit vector. Fix \(k\geq 0\), a set \(B\subseteq \{ 0,\ldots ,k-1\} \), and an arbitrary vector \(u\) on the \(k\) physical copies and the two auxiliary copy registers. Put \(m=|B^c|\), let \(w\) be the component obtained by applying the excitation projection for \(B\) to the physical copies of \(u\), and let \(\rho _G\) be its good-copy density. Fix \(j\in \{ 0,1,2\} \). Write \(\rho _j\) for the original singleton density, \(d_j=|I_j|\), and \(S_j=S(\rho _j)\).
Let \(p_i\) be the eigenvalues of \(\rho _j\), and define \(M_j(v)=\sum _i p_i e^{-v\log p_i}\), with zero weights contributing zero. Suppose \(K,r\in \mathbb R\) satisfy \(\log M_j(v)\leq vS_j+Kv^2\) whenever \(|v|\leq r\). Let \(F_j\) be the entropy observable of the permutation action on the \(m\) good copies of factor \(j\). If \(a\geq 0\), \(2a\leq r\), and \(2a\leq 1\), then
The vector \(u\) need not be a unit vector or permutation invariant, and \(w\) may vanish. These are the signed physical moments used in [ Ope26b , Section 8 ] .
Let \(\Omega \) have norm one, let \(w\) be the actual excitation component of an arbitrary original vector, and let \(\rho _G\) be its five-factor good-copy density. Put \(\rho _j=\operatorname {Tr}_{j^c}|\Omega \rangle \langle \Omega |\), with the partial trace taken in \(e_j\) coordinates. For all \(j\in \{ 0,1,2\} \) and \(a\in \mathbb R\),
No permutation invariance or nonvanishing of the component is required.
Let \(w\) be an excitation component of an arbitrary vector, and let \(D\) be its vector density after tracing the bad physical copies, retaining the good physical copies and the entire auxiliary register. The full good-copy density is obtained from \(D\) by the auxiliary coordinate change \(e\), followed by the trace over the bad auxiliary copies. No normalization of the one-copy vector or of \(w\) is required for this identity.
In the preceding definition suppose \(\| \Omega \| =1\). Let \(P_{QYV}\) be the average of the simultaneous copy-permutation operators on the physical factors \(Q,Y,V\), acting trivially on \(C,R\). Then
The original vector \(u\) need not be symmetric, unit or nonzero. Zero components, zero copies and empty good sets are included.
With the registers separated as above,
Neither \(u\) nor \(w\) need be normalized.
Retain the good physical copies and the entire auxiliary register, and trace the bad physical copies. The resulting density is
after the indicated reordering of registers.
Suppose \(\| \Omega \| =1\) and \((R_B\otimes I_{\mathcal K})u=u\). Then \(u(b\sqcup g,c)=(\prod _{i\in G}\Omega (g_i))w_B(u)(b,c)\) for every \(b,g,c\). Thus \(u\) has the tensor factor \(\bigotimes _{i\in G}\Omega \) on its \(k-|B|\) good physical coordinates, with every other coordinate retained in \(w_B(u)\).
Exchange the exterior physical regions and the auxiliary regions simultaneously, preserving the independent middle region:
Let \(w'=(R'_B\otimes I)u'\) be the actual component determined by \(\Omega '\). Then
The vector \(w'\) is the coordinate exchange of \(w\), rather than a separately chosen excitation component.
The common density has total mass
The trace is a complex number; the right-hand side is the real squared norm included into \(\mathbb C\). The identity includes zero components, zero copies and empty good sets.
Under the preceding hypotheses, suppose that \(u\) is fixed by simultaneous permutations of the physical and both auxiliary copies. Let \(w=(R_B\otimes I)u\), and write \(d_X=|X|\) for each coordinate set. If \(a\geq 0\) and \(2a\leq 1\), then
The component \(w\) may vanish. No normalization of \(u\) or \(w\) is required, and the conclusion includes \(m=0\). This is the rough good-copy moment estimate in [ Ope26b , Section 8, lines 520–555 ] .
Let \(Q,Y,V,C,R\) be finite coordinate sets, let \(\Omega \) be a unit vector on \(QYV\), and let \(u\) be a vector on \(k\) physical copies and \(k\) copies of each auxiliary space. For \(B\subseteq \{ 0,\ldots ,k-1\} \), write \(m=|B^c|\) and let \(\rho _G\) be the actual five-factor good-copy density of \((R_B\otimes I)u\). On the \(m\) good copies, put
For every \(a\geq 0\),
The vector \(u\) need not be symmetric or normalized. This is the physical spectral restriction used in [ Ope26b , Section 8, lines 501–555 ] .
Let \(A,C\) be finite coordinate sets, let \(\Omega \in \mathbb C^A\) be unit, and let \(u\in (\mathbb C^A)^{\otimes k}\otimes \mathbb C^C\) be arbitrary. For an excited subset \(B\subseteq \{ 0,\ldots ,k-1\} \), put \(G=B^c\), \(m=|G|\) and \(w=(R_B\otimes I_C)u\). Enumerate the good copies by one chosen equivalence. Let \(\rho _{A_G C}(w)\) be the actual density obtained from \(|w\rangle \langle w|\) by tracing the bad physical copies, and let \(P_m\) be the orthogonal projection onto \(\operatorname {Sym}^m\mathbb C^A\). Then
The vector \(u\) need not be symmetric, normalized or nonzero. Zero copies and empty good sets are included.
This is the physical symmetric-support assertion used in [ Ope26b , Section 7 ] . For the physical space \(\mathbb C^Q\otimes \mathbb C^Y\otimes \mathbb C^V\), take \(A=Q\times (Y\times V)\). Every middle physical coordinate is retained until the projection \(P_m\) is applied.
Suppose \(\| \Omega \| =1\). Set \(\rho _Q=\operatorname {Tr}_T|\Omega \rangle \langle \Omega |\), and let \(\rho _{C_G}(w)\) be the actual good auxiliary marginal of \(w\). Then
The original vector and its component may be unnormalized or zero. The identity includes zero copies and empty good sets.
Let the one-copy physical vector \(\Omega \) have norm one, and let \(u\) be fixed by simultaneous permutations of the physical and two auxiliary copy registers. For a set \(B\) of bad copies, put \(m=|B^c|\) and \(w=(R_B\otimes I)u\). Let \(\rho _{\mathrm{pair}}\) be the marginal of \(|w\rangle \langle w|\) on the good \(QC\) and \(VR\) coordinates. Write \(d_Q,d_V,d_C,d_R\) for the one-copy dimensions and \(D_{QC},D_{VR}\) for the two lifted merge deficits. For every real \(a\leq 1\),
The component may vanish. These are the separate bounds before their combination in [ Ope26b , Section 8 ] .
Let \(\| \Omega \| =1\), \(0\le \tau \le \tfrac 12\), \(c\ge 0\), and \(H\ge 0\). For \(B\subseteq \{ 0,\ldots ,k-1\} \), let \(R_B\) be the physical projection onto precisely the copies in \(B\) being orthogonal to \(\Omega \). Suppose that, for every vector \(u\) with simultaneous copy symmetry and both original auxiliary labels and every \(B\) with \(|B|\le \tau k\), the components \(w_B=(R_B\otimes I_{CR})u\) satisfy
Then
where \(h(\tau )=-\tau \log \tau -(1-\tau )\log (1-\tau )\), with \(0\log 0=0\). The component estimate remains an explicit hypothesis; this is the subsequent implication used in [ Ope26b , Section 8, (comparator:inverse-compression) ] .
If \(\| \Omega \| =1\), then \(P\) is an orthogonal projection. Every vector \(u\) satisfying \(Pu=u\) lies in the range of \(Q\), has both original auxiliary labels, and is fixed by every simultaneous copy permutation. No commutation with a replica metric is assumed.
Suppose \(\| \Omega \| =1\), \(g{\gt}0\), \(k{\gt}0\), \(\tau {\gt}0\), and
For every unit vector \(v\) with simultaneous copy symmetry and both original auxiliary labels,
This is the retained-mass estimate in [ Ope26b , Section 8, (comparator:defect-mass) ] .
Let \(A\) and \(B\) be finite sets, let \(\mathcal H=\mathbb C^A\) and \(\mathcal K=\mathbb C^B\), and let \(H\) be an arbitrary operator on \(\mathcal H\). For \(k\ge 0\), let \(U_k\) be the unitary induced by the coordinate regrouping \((A\times B)^k\simeq A^k\times B^k\). For each \(0\le i{\lt}k\), the operator \((H\otimes I_{\mathcal K})^{(i)}\) is the pullback under \(U_k\) of \(H^{(i)}\otimes I_{\mathcal K^{\otimes k}}\). The operator \(H^{(i)}\) equals the iterated tensor product with \(H\) in position \(i\) and identities elsewhere. Consequently,
For \(k=0\), set \(\overline H=0\); both normalized sums are zero. This is the identity extension used in [ Ope26b , Sections 6 and 7 ] .
Let \(A\) be a finite set, let \(\Omega \in \mathbb C^A\), and let \(d,k\in \mathbb N\). For every label \(\lambda \) of \(S_k\), the initial vector \(v_{k,\lambda }\) has label \(\lambda \) on both auxiliary systems:
The identities include \(d=0\), \(k=0\), and the zero physical vector, with the conventions of Definition 13.79.1.
There is one sequence \((\lambda _k)\) for which every \(k\ge 1\) satisfies
The vector has label \(\lambda _k\) on both auxiliary systems and is invariant under every simultaneous copy permutation on the physical, left auxiliary and right auxiliary systems. For all sufficiently large \(k\),
and \(\log d_{\lambda _k}=kS(\rho )+o(k)\). The initial projection of \(U_k\) is required only to be nonzero; no inverse polynomial lower bound on its probability is asserted.
For every label \(\lambda \) and every permutation \(\sigma \in S_k\), let \(R_A(\sigma )\) and \(R_d(\sigma )\) permute the copies of the physical and auxiliary systems, respectively. Then
Write \(\rho _Q=\operatorname {Tr}_T|\Omega \rangle \langle \Omega |\) and \(\rho _{\mathcal K}(w)=\operatorname {Tr}_{(QT)^{\otimes k}} |w\rangle \langle w|\). After regrouping the retained coordinates as \(Q^{\otimes m}\otimes \mathcal K\), one has
Neither \(u\) nor \(w\) need be normalized or nonzero. Zero copies and empty good sets are included.
For every real \(a\) with \(2a\leq 1\),
No normalization or nonvanishing of \(w\) is required. Zero copies and an empty good set are included. This is an auxiliary polynomial bound for the rough estimate in [ Ope26b , Section 8 ] .
If in addition \(\| 0_s\| =\| 0_X\| =1\), then \(\mathcal R_X\) is an isometry and
In particular this equality introduces no factor \(\| R_0\| \).
Suppose \(p_x{\gt}0\) for every \(x\in E\), \(Q^\dagger =Q\), and \(T^\dagger =T\). For every physical operator \(L\) and every physical vector \(\Omega \),
No normalization, projection, commutation, or operator norm hypothesis is needed for this identity. Unselected eigenvalues may vanish.
Write \(b=0_s\), \(c=0_X\), and \(w_s=\mathbf1_{s\in E}(\sqrt{p_s})^{-1}\). A unit blank satisfies \(\sum _u\overline{b_u}b_u=1\). The restoring operator with its ancillary spectator has entries
If \(\| b\| =\| c\| =1\), then
Let \(E\subseteq \mathsf X\). If \(0\le M\le \rho \), then
The first inequality requires only \(M\ge 0\); the second holds for an arbitrary positive-semidefinite reference, without requiring it to be diagonal. No commutation assumption is imposed.
If \(M\ge 0\), then
Both indices range over the entire basis, including zero-probability coordinates.
Every \(p_x\) is nonnegative, and \(\rho ^+=\operatorname {diag}(p_x^{-1})\).
Let \(\rho \) be an operator on \(X\otimes Y\), and set \(\rho _Y=\operatorname {tr}_X\rho \). Suppose \(Q\) and \(T\) are orthogonal projections and \(c_X,c_Q,c_Y\ge 0\). Assume the following inequalities, with the scalar inequality required for every \(x\in E\):
Then \(B_Y\le c_Xc_Qc_Y I_Y\).
Suppose \(Q^\dagger =Q\), \(Q^2=Q\), and \(T^\dagger =T\). The matrix \(B_Y\) is positive semidefinite and
Transport \(R_0\otimes I_e\) by the permutation
to obtain \(\widehat R_0\). Then
No commutation between \(Q\) and \(I_X\otimes T\) is required. More generally, positivity of \(B_Y\) only requires \(Q\ge 0\) and \(T^\dagger =T\). The source uses the special case in which \(T\) is also an orthogonal projection.
Assume the normalization and selected positivity conditions of Theorem 13.46.5. Suppose that \(Q,T\) are orthogonal projections, \([\rho _{XY},Q]=0\), and \(\rho _X=\operatorname {tr}_Y\rho _{XY}=\operatorname {diag}(p_x)\). Then
and consequently \(\| P_\Omega R_0\phi \| \le 1\). The marginal may be singular, and no commutation between \(Q\) and \(I_X\otimes T\) is assumed.
For arbitrary \(Q,T,\Omega \),
With unit \(s\) and \(X\) blanks, the actual ground component satisfies
The coordinate \(e\) ranges over the entire basis of \(X\).
Suppose \(\| \Omega \| =\| 0_s\| =\| 0_X\| =1\) and \(p_x{\gt}0\) for \(x\in E\). Then
For every additional unit blank \(0_e\), one also has \(g=P_\Omega B_0\psi \), where \(\psi =|0_s,0_e\rangle \otimes \Omega \). This last equality requires only that the \(X\) and \(e\) blanks be unit.
The reduced density is positive semidefinite. If \(\| \Omega \| =1\), then \(\operatorname{tr}\rho _{XY}=1\) and \(P_\Omega \) is an orthogonal projection. For every enlarged vector \(v\), every ancillary pair \((s,e)\), and every physical coordinate \((a,z)\),
Suppose \(\rho \ge 0\), \(Q\) and \(T\) are orthogonal projections, and \(\rho Q=Q\rho \). Then
No commutation between \(Q\) and \(I_X\otimes T\) is assumed.
Let \(\rho \) be an operator on \(X\otimes Y\), set \(\rho _Y=\operatorname {tr}_X\rho \), and suppose \(Q,T\) are orthogonal projections. Assume \(p_x{\gt}0\) for every \(x\in E\) and \(\| 0_s\| =\| 0_X\| =\| 0_e\| =1\). Let \(S_X,S_{XY},S_Y,w,\mathcal I\) be real numbers satisfying \(\mathcal I=S_X+S_{XY}-S_Y\). Assume the following inequalities, with the scalar inequality required for every \(x\in E\):
Then
In the spectral application, take \(S_X=S(X)\), \(S_{XY}=S(XY)\), and \(S_Y=S(Y)\).
Let \(\rho \) be an operator on \(X\otimes Y\), and set \(\rho _Y=\operatorname {tr}_X\rho \). Suppose \(Q,T\) are orthogonal projections, \(c_X,c_Q,c_Y\ge 0\), and (406) holds. Assume \(p_x{\gt}0\) for every \(x\in E\). If \(\| 0_s\| =\| 0_X\| =1\), then \(\| R_0\| \le \sqrt{c_Xc_Qc_Y}\). Independently, if \(\| 0_s\| =\| 0_e\| =1\), then \(\| B_0\| \le \sqrt{c_Xc_Qc_Y}\). Neither bound requires positivity of the unselected \(p_x\) or commutation between \(Q\) and \(I_X\otimes T\).
Suppose \(Q\) and \(T\) are orthogonal projections and retain the selected positivity and unit-blank assumptions above. Write \(A=(P_E\otimes I_Y)\otimes I_Z\), \(B=(I_X\otimes T)\otimes I_Z\), and \(C=Q\otimes I_Z\). If
then
Taking \(\varepsilon =\sqrt\delta \) gives the adjoint error bound used in the source. No commutation among the three projections is required.
Let \(\rho \) be a density matrix and \(\sigma \succeq 0\) with \(\ker \sigma \subseteq \ker \rho \). Then
The normalization of \(\sigma \) is not needed.
Let \(\rho ,\sigma \succeq 0\). For every unitary \(U\),
and some unitary \(U\) attains \(\operatorname{tr}[(\sqrt\rho \sqrt\sigma )^\dagger U]=F(\rho ,\sigma )\). In particular \(|\operatorname{tr}\sqrt\rho \sqrt\sigma |\le F(\rho ,\sigma )\).
Let \(\rho _{AB}\succeq 0\) have positive definite marginals \(\rho _A\) and \(\rho _B\). Then
No trace normalization is required.
Let \(\rho _{AB}\succeq 0\) be any finite-dimensional bipartite operator. Then
No trace normalization or positive-dimension hypothesis is required. The statement includes the cases in which either marginal support has dimension zero.
Let \(\rho \) be a square matrix and let \(\omega \succeq 0\) have the same finite index set. Let \(e\) be a bijection onto another finite index set. Then
Let \(\rho ,\omega \in M_{D}(\mathbb {C})\) be positive semidefinite with \(\ker \omega \subseteq \ker \rho \). Let \(V:\mathbb {C}^k\to \mathbb {C}^D\) satisfy (211). Then
If \(\omega \succ 0\), then, for every square matrix \(\rho \) of the same size,
Let \(T:M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) be a positive linear map with \(\operatorname{tr}[T(\rho )] = c\, \operatorname{tr}[\rho ]\) for some nonnegative real \(c\) and all \(\rho \in M_{D}(\mathbb {C})\). Then for all Hermitian \(H\in M_{D}(\mathbb {C})\), \(\lVert T(H)\rVert _{\operatorname{tr}}\leq c\cdot \lVert H\rVert _{\operatorname{tr}}\). Generalizes Theorem 13.1.19 from the trace-preserving case \(c=1\).
For \(k\ge 0\) and any actual central label \(\lambda \) on \(R^k\), let
Regroup the factors into \((AC)^k\otimes (R^k\otimes B^k)\) and put \(Q_k=(|\beta \rangle \langle \beta |)^{\otimes k}\otimes I_{R^kB^k}\). Then
The right label acts on a factor disjoint from the Bell projection.
Suppose in addition that \(\| \Omega \| =1\) and \(H\Omega =E_0\Omega \), where \(E_0\in \mathbb R\). Write \(\psi (b,r)=\chi (r,b)\), so that
There is one sequence \((\lambda _k)\) such that, for every \(k\ge 1\), the actual initial vector in 499 is nonzero, has norm at most one, and satisfies
It has label \(\lambda _k\) on both \(C\) and \(R\), and is fixed by simultaneous copy permutations of the physical and both auxiliary systems. For all sufficiently large \(k\),
The Bell identity 500 applies to this same sequence.
Let \(\rho \) be a permutation-invariant density matrix on \(Q^{\otimes k}\), where \(\dim Q=q\). Write \(F\) for its Schur-label observable and \(L=-\log \rho \) on the support of \(\rho \), with zero value on the kernel. For a real center \(s\), put
Suppose \(C_0\ge 0\), \(c_0{\gt}0\), and \(\mathcal B\ge 1\), and assume the actual centered surprisal estimate
Then \(c=\min (c_0,1)/2\) is positive. For \(0\le u\le c/\sqrt{\mathcal B}\),
In particular, throughout the symmetric interval \(|t|\le c/\sqrt{\mathcal B}\),
The quadratic coefficient and the interval constant are independent of \(q\). The center is arbitrary; the specialization \(s=kS(Q)\) requires the actual independent-copy surprisal estimate at that center.
Let \(S\) be a finite orthonormal basis and let \(v\) be a unit vector in \(\mathbb C^S\otimes (\mathbb C^\Omega )^{\otimes k}\). There is an irreducible label \(\lambda \) such that \(\| (I_S\otimes \pi ^\lambda )v\| ^2\ge (k+1)^{-q^2}\). In particular, \((I_S\otimes \pi ^\lambda )v\ne 0\).
Let \(\Omega \in \mathcal H_A\otimes \mathcal H_B\), and diagonalize \(\rho _A=\operatorname {Tr}_B|\Omega \rangle \langle \Omega |\) in an orthonormal basis \((e_i)\), with eigenvalues \((p_i)\). Choose a set \(E\) of eigenvector indices with \(z=\sum _{i\in E}p_i{\gt}0\). Write \(\Pi _E\) for the corresponding spectral projection and put \(\sigma =z^{-1}\Pi _E\rho _A\Pi _E\). Compress the selected factor to \(\mathbb C^E\), normalize by \(z^{-1/2}\), interchange the two factors, and relabel \(E\) by \(\{ 1,\ldots ,|E|\} \). If \(\psi \in \mathcal H_B\otimes \mathbb C^{|E|}\) is this vector, then
No normalization of the original vector is required.
Let \(A\) be a positive definite complex matrix, \(r\in \mathbb {R}\setminus \{ 0\} \), and \(\rho \) any complex matrix of the same size. Then \(A^r\) commutes with \(\rho \) if and only if \(A\) commutes with \(\rho \). If \(x\ge 0\) and \(b{\gt}0\), then \((x+b\mathbb {1})^r\) commutes with \(\rho \) if and only if \(x\) commutes with \(\rho \). Consequently, for \(a{\gt}0\), commutation of \(\rho \) with the regularized filter \((x+b\mathbb {1})^{-a/2}\) implies \([\rho ,x]=0\). This is the functional-calculus implication in [ Ope26a , Section 4, descending stationarity ] .
Let \(\rho _{ABC}\) be a tripartite density matrix and set \(\sigma _{ABC}=(\mathbf1_A/d_A)\otimes \rho _{BC}\). Then equality holds in strong subadditivity if and only if relative-entropy data processing under the partial trace over \(C\) is saturated for this pair:
By Lemma 13.8.3, the reference on the right is \((\mathbf1_A/d_A)\otimes \rho _B\).
This is an equivalent hypothesis-free criterion with a different reference state. The exact product-marginal formulation is Theorem 13.8.48.
Let \(\rho _{ABC}\) be a tripartite density matrix. Then equality holds in strong subadditivity if and only if relative-entropy data processing under the partial trace over \(C\) is saturated for the pair \(\rho _{ABC}\) and \(\rho _A\otimes \rho _{BC}\):
Moreover, \(\operatorname{tr}_C(\rho _A\otimes \rho _{BC})=\rho _A\otimes \rho _B\). This is the product-marginal formulation in [ HJPW04 , Equations (5)–(7) ] .
Let \(\rho _{ABC}\) be a tripartite density matrix attaining equality in strong subadditivity. The raw Petz support map for the reference \(\rho _A\otimes \rho _{BC}\) recovers \(\rho _{ABC}\) from \(\rho _{AB}\). Moreover,
where \(\widehat{\mathcal R}_{\rho _{BC}}\) is a trace-preserving completely positive extension of the support formula. This is equation (11) of [ HJPW04 ] , obtained from Theorem 3 and equation (8) together with the supported form of equation (10).
No marginal is required to be invertible. If \(\rho _A\) is singular, the displayed factorization is asserted on the supported input \(\rho _{AB}\) only; it is not a global factorization of an ambient product-reference completion.
Let \(\rho \) be a Hermitian operator on \(A\otimes B\otimes C\), and let \(e_A:A'\to A\), \(e_B:B'\to B\), and \(e_C:C'\to C\) be bijections. Define \(\rho '\) by
If \(\rho \) satisfies equality in strong subadditivity, then so does \(\rho '\).
For a positive semidefinite \(\omega \) on \(A\otimes B\otimes C\) of any trace, \(S(\omega _{ABC})+S(\omega _B)\le S(\omega _{AB})+S(\omega _{BC})\). For a positive semidefinite \(\omega \) on \(A\otimes B\) with trace \(t\), \(S(\omega _{AB})+\eta (t)\le S(\omega _A)+S(\omega _B)\) and \(S(\omega _B)+\eta (t)\le S(\omega _A)+S(\omega _{AB})\) [ AL70 ] .
Let \(S\) be a \(*\)-subalgebra of \(M_{D}(\mathbb {C})\). There are \(K\in \mathbb {N}\), positive dimensions \(d_0,\ldots ,d_{K-1}\) and multiplicities \(m_0,\ldots ,m_{K-1}\) with \(\sum _kd_km_k=D\), realized by an explicit identification of the index sets, and a unitary \(U\in M_{D}(\mathbb {C})\) such that a matrix \(A\in M_{D}(\mathbb {C})\) belongs to \(S\) exactly when
for some matrices \(B_k\in M_{d_k}(\mathbb {C})\); that is, up to reordering the two tensor factors of each block,
This is the block representation of a finite-dimensional \(*\)-algebra in Equation (1.39) of [ Wol12 ] , invoked by [ Wol12 , Theorem 6.14 ] , in the unital case: a \(*\)-subalgebra contains the identity matrix, so there is no zero block.
Let \(\rho ,\omega \in M_{D}(\mathbb {C})\) be positive semidefinite and suppose that \(\ker \omega \subseteq \ker \rho \). If \(V:\mathbb {C}^k\to \mathbb {C}^D\) satisfies \(VV^\dagger =P_{\operatorname{supp}(\omega )}\), then
No condition on \(V^\dagger V\) is needed for this identity.
If \(0\le M\le \rho \), then \(\ker \rho \subseteq \ker M\) and \(MP_\rho =P_\rho M=M\).
If \(0\le M\le \rho \), then \(M\rho ^+M\le M\), even when \(\rho \) is singular or \(M\) and \(\rho \) do not commute.
Let \(A\) and \(B\) be positive semidefinite. Their positive square roots, support inverse square roots, and support projections satisfy
Moreover,
The same support projection absorbs the square root:
If \(A\) is positive definite, then \(P_A=\mathbf1\).
- Matrix.PosSemidef.sqrt_kronecker
- Matrix.PosSemidef.supportInvSqrt_kronecker
- Matrix.PosSemidef.cfc_sqrt_mul_supportInvSqrt
- Matrix.PosSemidef.supportInvSqrt_mul_cfc_sqrt
- Matrix.PosSemidef.cfc_sqrt_mul_supportProj
- Matrix.PosSemidef.supportProj_mul_cfc_sqrt
- Matrix.PosSemidef.supportProj_kronecker
- Matrix.PosDef.supportProj_eq_one
Let \(A,B\) be positive semidefinite, let \(t{\gt}0\), set
and let \(P_B\) be the support projection of \(B\). Then
Consequently,
This is the one-pair algebraic identification used in the singular equality argument of Jenčová–Ruskai, arXiv:0903.2895v4, lines 783–790. It does not assert that equality of relative entropies gives a common resolvent for a finite family.
Let \(A\in M_{n}(\mathbb {C})\) be positive semidefinite and let \(v\in \mathbb {C}^n\) satisfy \(\langle v,v\rangle =1\) and \(P_{\operatorname{supp}(A)}v=v\). Then
Here \(\log A\) is defined by the continuous functional calculus with \(\log 0=0\). Compare the finite-dimensional vector-state Jensen argument in [ Bha97 , Chapter V ] .
Let \(I\) be a finite nonempty set. For each \(i\in I\), let \(A_i\) and \(B_i\) be positive-semidefinite matrices satisfying \(\ker B_i\subseteq \ker A_i\). Put
and suppose that
Then, for every \(i\in I\) and \(t{\gt}0\),
Thus the shifted relative-modular resolvents agree on \((\ker B_i)^\perp \). The local support projection is essential; no ambient equality is asserted. This is the support-restricted conclusion of Jenčová–Ruskai, arXiv:0903.2895v4, lines 766–793.
Let \(I\) be a finite nonempty set. For each \(i\in I\), let \(A_i\) and \(B_i\) be positive-semidefinite matrices of the same size satisfying \(\ker B_i\subseteq \ker A_i\). Put
Then the function
is continuous on \((0,\infty )\) and integrable there, and
This is the finite-family support-domain form of \((\mathrm{intspec})\) and \((\mathrm{intAB})\) in Jenčová–Ruskai, arXiv:0903.2895v4, lines 406–431, with the positive-semidefinite convention and kernel hypotheses at lines 717–720 and 766–785.
Under the hypotheses and notation of Theorem 13.8.20, for every \(t{\gt}0\) one has
This is the coefficient-correct combination of the two source defects in \((\mathrm{intAB})\) of Jenčová–Ruskai, arXiv:0903.2895v4, lines 423–435.
Under the hypotheses and notation of Lemma 13.8.24, suppose that
Then, for every \(i\in I\),
This is the support-domain form of the common-resolvent equation \((\mathrm{basiceq})\) in Section 3.1 of Jenčová–Ruskai, arXiv:0903.2895v4. Its residual calculation is the one in the Appendix, equations \((\mathrm{Mj})\) and \((\mathrm{eq:Schz1})\).
Under the hypotheses of Theorem 13.8.20, suppose
Then, for every \(t{\gt}0\),
This is the source-\(B\) pointwise-vanishing passage in Jenčová–Ruskai, arXiv:0903.2895v4, lines 433–435, 652–674, and 788–790. The common projected resolvent conclusion is stated downstream in Theorem 13.8.35.
Under the hypotheses and notation of Lemma 13.8.17, suppose that the source-\(B\) defect vanishes:
Put
and let \(P_{S_i}\) be the support projection of \(S_i\). Then
This is the fixed-parameter support-domain residual step behind \((\mathrm{basiceq})\) in Jenčová–Ruskai, arXiv:0903.2895v4, lines 652–660 and 788–790. No kernel inclusion is needed for this algebraic implication.
Let \(\rho \geq 0\) be a bipartite complex matrix whose first marginal is faithful. Choose an eigenbasis in which \(\operatorname{tr}_B\rho =\operatorname{diag}(p_1,\ldots ,p_{d_A})\) with every \(p_i{\gt}0\), and define the linear map \(\Phi _\rho \) on matrix units by
Write \(\sigma =\operatorname{diag}(p_1,\ldots ,p_{d_A})\) and \(\tau =\operatorname{tr}_A\rho \). Then \(\Phi _\rho \) is completely positive and trace preserving,
and application of \(\Phi _\rho \) to the first half of \(\sum _{i,j}\sqrt{p_ip_j}\, E_{ij}\otimes E_{ij}\), followed by restoring the order of the two factors, reconstructs \(\rho \).
Under the hypotheses of Theorem 23.43.1, let \(\rho \ge 0\) satisfy \(J\rho =\rho \). Then
No normalization of \(\rho \) is assumed.
For every \(A\in M_{D}(\mathbb {C})\), with \(\lvert A\rvert =\sqrt{A^\dagger A}\) the positive-semidefinite square root of \(A^\dagger A\),
This is the formula \(\lVert A\rVert _1=\operatorname{tr}[\lvert A\rvert ]\) of [ Wol12 , Chapter 8, Section 8.1 ] ; the trace of the positive-semidefinite matrix \(\lvert A\rvert \) is real.
Let \(T:M_{D}(\mathbb {C})\to M_{D}(\mathbb {C})\) be positive and trace preserving, let \(\rho \) be a density operator, and let \(n{\gt}0\). Then
Here the displayed transfer-matrix norm equals \(\lVert T^n-T_\varphi ^n\rVert _{2\to 2}\), the Hilbert–Schmidt operator norm of the corresponding superoperator. The explicit \(n{\gt}0\) records the paper’s positive-natural convention: at \(n=0\), both superoperator powers are the identity, so the displayed right-hand side vanishes. This is the upper assertion of [ Wol12 , Chapter 8, Proposition “Convergence towards asymptotic states”, Eqs. (8.112), (8.114)–(8.116) ] .
Let \(T:M_{D}(\mathbb {C})\to M_{D'}(\mathbb {C})\) be a trace-preserving positive linear map. Then for all Hermitian \(H\in M_{D}(\mathbb {C})\), \(\lVert T(H)\rVert _{\operatorname{tr}}\leq \lVert H\rVert _{\operatorname{tr}}\). See [ Wol12 , Chapter 8, Theorem 8.16 ] .
For every \(A\in M_{D}(\mathbb {C})\),
Also, \(\lVert A\rVert _{\operatorname{tr}}=0\) if and only if \(A=0\). Equivalently, \(\lVert A\rVert _{\operatorname{tr}}{\gt}0\) if and only if \(A\neq 0\).
For every \(A\in M_{D}(\mathbb {C})\),
The first inequality is the \(p=1\), \(p'=2\) case of [ Wol12 , Eq. (8.1) ] ; the second is the corresponding case of [ Wol12 , Eq. (8.7) ] . Both are used in the proof of trace-norm convergence toward asymptotic states.
The Schatten one-norm and trace norm are the sums over the finite support of the singular-value sequence. Equivalently, the trace norm is the sum over the indices below the rank of the represented linear map.
For all \(A,B\in M_{D}(\mathbb {C})\), \(\lVert A+B\rVert _{\operatorname{tr}} \leq \lVert A\rVert _{\operatorname{tr}}+\lVert B\rVert _{\operatorname{tr}}\). Together with homogeneity (Theorem 13.1.6) and definiteness (Theorem 13.1.4), this completes the norm axioms of [ Wol12 , Chapter 8, Section 8.1 ] for the trace norm.
For all unitaries \(U,V\in M_{D}(\mathbb {C})\) and every \(A\in M_{D}(\mathbb {C})\),
The trace norm is thus unitarily invariant [ Wol12 , Chapter 8, Section 8.1 ] .
For every \(A\in M_{D}(\mathbb {C})\),
and the maximum is attained: some unitary \(U\) satisfies \(\operatorname{tr}[A^\dagger U]=\lVert A\rVert _{\operatorname{tr}}\). See [ Wol12 , Chapter 8, Eq. (8.11) ] .
Let \(\rho =\sum _ip_i|i\rangle \langle i|\) and \(\sigma =\sum _jq_j|j'\rangle \langle j'|\) be spectral decompositions of Hermitian matrices, and let \(f,g\) be real functions. Then
For a linear map \(S:M_{D}(\mathbb {C})\to M_{D}(\mathbb {C})\), let \(\lVert S\rVert _{2\to 2}\) be its operator norm for the Hilbert–Schmidt norm. Then
where the norm on the transfer matrix is its largest-singular-value norm. The transfer representation also preserves subtraction and powers.
Regroup the copies canonically as \(\mathcal H_{AC}^{\otimes k}\otimes (\mathcal H_R^{\otimes k}\otimes \mathcal H_B^{\otimes k})\). Denote the transported product vectors by \(\mathrm{pre}_k\) and \(\mathrm{post}_k\). For any operator \(\Lambda \) on \(\mathcal H_R^{\otimes k}\), put \(Q=P^{\otimes k}\otimes I_{R^kB^k}\) and \(T_\Lambda =I_{(AC)^k}\otimes (\Lambda \otimes I_{B^k})\). Then
No self-adjointness, projection property or commutation assumption is required for \(\Lambda \).
For every \(k\ge 0\), \(\| \beta ^{\otimes k}\| =1\), and \(P^{\otimes k}\) is an orthogonal projection. Simultaneously permuting the \(AC\) copies fixes \(\beta ^{\otimes k}\). The permutation assertion holds without the assumption \(z{\gt}0\).
The selected Bell vector satisfies \(\| \beta \| =1\), and \(P\) is an orthogonal projection: \(P^2=P=P^\dagger \).
The selected coordinate embedding satisfies \(J^\dagger J=I_R\) and \(JJ^\dagger =P_E\).
Fix \(\theta \ge 0\) and \(C{\gt}0\). There is an integer \(N\ge 2\), depending only on these two constants, such that for every integer \(n\ge N\) and every \(0{\lt}\mathcal B\le Cn\),
Fix \(\theta \ge 0\) and \(C{\gt}0\). There is an integer \(N\ge 2\), depending only on these two constants, such that for every integer \(n\ge N\) and every \(0{\lt}\mathcal B\le Cn(\log n)^{12}\),
Fix \(\theta \ge 0\), \(C{\gt}0\), \(n{\gt}1\), and \(0{\lt}\mathcal B\le Cn(\log n)^{12}\). With \(c=(32\sqrt{(1+\theta )C})^{-1}\), one has
Let \(\psi \in \mathbb {C}^{A}\otimes \mathbb {C}^{R}\) purify \(\rho \) and \(\varphi \in \mathbb {C}^{A}\otimes \mathbb {C}^{S}\) purify \(\sigma \), with \(\dim \mathbb {C}^S\ge \dim \mathbb {C}^A\) and \(\dim \mathbb {C}^S\ge \dim \mathbb {C}^R\). Then there is an isometry \(V:\mathbb {C}^R\to \mathbb {C}^S\) with
Neither purification need be minimal, and \(V\) is defined on all of \(\mathbb {C}^R\). This is the purification clause of [ Ope26a , Lemma 2.2 ] ; compare [ Uhl76 , Sections 2 and 5 ] .
Let \(\psi \in \mathbb {C}^{A}\otimes \mathbb {C}^{R}\) purify \(\rho \) and \(\varphi \in \mathbb {C}^{A}\otimes \mathbb {C}^{S}\) purify \(\sigma \), with no condition on the dimensions. Regard \(\varphi \) as a vector \(\widehat\varphi \) in \(\mathbb {C}^A\otimes (\mathbb {C}^S\oplus \mathbb {C}^A\oplus \mathbb {C}^R)\) that vanishes on the added summands; it still purifies \(\sigma \). There is an isometry \(V:\mathbb {C}^R\to \mathbb {C}^S\oplus \mathbb {C}^A\oplus \mathbb {C}^R\) with \(\langle \widehat\varphi ,(\mathbb {1}\otimes V)\psi \rangle =F(\rho ,\sigma )\).
Let \(C\in \mathcal M\) and \(G,U:\mathbb {R}\to \mathcal M\). Suppose \(U(0)=I\), \(G(s)^\dagger =G(s)\), \(U^{\prime }(s)=iG(s)U(s)\), and \(CG(s)=G(s)C\) for every \(s\in \mathbb {R}\). Then \(U(t)^\dagger C U(t)=C\) for every \(t\in \mathbb {R}\). The matrix \(C\) need not be Hermitian or unitary.
Let \(G,H:\mathbb {R}\to \mathcal M\) be continuous, and suppose \(G(s)^\dagger =G(s)\) for every \(s\in \mathbb {R}\). Let \(U,V:\mathbb {R}\to \mathcal M\) satisfy \(U(0)=I\), \(V(0)=I\), and be differentiable with \(U^{\prime }(s)=iG(s)U(s)\) and \(V^{\prime }(s)=iH(s)V(s)\) for every \(s\in \mathbb {R}\). Then, for every \(t\in \mathbb {R}\),
Hermiticity of \(H\) is not required.
Let \(G,H:\mathbb {R}\to \mathcal M\) be continuous with \(G(s)^\dagger =G(s)\) and \(H(s)^\dagger =H(s)\) for every \(s\in \mathbb {R}\). Let \(U,V:\mathbb {R}\to \mathcal M\) satisfy \(U(0)=I\), \(V(0)=I\), and be differentiable with \(U^{\prime }(s)=iG(s)U(s)\) and \(V^{\prime }(s)=iH(s)V(s)\) for every \(s\in \mathbb {R}\). For every \(t,\varepsilon \in \mathbb {R}\), if \(\| G(s)-H(s)\| \le \varepsilon \) for every \(s\in J_t\), then
Nonnegativity of \(\varepsilon \) follows from the bound at \(s=0\).
Let \(C\in \mathcal M\) and \(G,U:\mathbb {R}\to \mathcal M\). Suppose \(G(s)^\dagger =G(s)\) and \(U^{\prime }(s)=iG(s)U(s)\) for every \(s\in \mathbb {R}\). Then, for every \(t\in \mathbb {R}\),
Neither Hermiticity of \(C\) nor an initial-value condition is required.
Let \(G,H:\mathbb {R}\to \mathcal M\) be continuous with \(G(s)^\dagger =G(s)\) and \(H(s)^\dagger =H(s)\) for every \(s\in \mathbb {R}\). Let \(U,V:\mathbb {R}\to \mathcal M\) satisfy \(U(0)=I\), \(V(0)=I\), and be differentiable with \(U^{\prime }(s)=iG(s)U(s)\) and \(V^{\prime }(s)=iH(s)V(s)\) for every \(s\in \mathbb {R}\). Then, for every \(t\in \mathbb {R}\),
Let \(G,U:\mathbb {R}\to \mathcal M\) with \(G(s)^\dagger =G(s)\) for every \(s\in \mathbb {R}\). Suppose \(U(0)=I\) and \(U\) is differentiable with \(U^{\prime }(s)=iG(s)U(s)\) for every \(s\in \mathbb {R}\). Then \(U(t)\) is unitary for every \(t\in \mathbb {R}\).
Let \(G:\mathbb {R}\to \mathcal M\) be continuously differentiable with \(G(t)^\dagger =G(t)\) for every \(t\in \mathbb {R}\). Let \(M\ge 0\) satisfy \(\| G(t)\| \le M\) for every \(t\in \mathbb {R}\). There is a differentiable path \(U:\mathbb {R}\to \mathcal M\) with \(U(0)=I\) such that, for every \(t\in \mathbb {R}\),
For every path \(V:\mathbb {R}\to \mathcal M\), if \(V(0)=I\) and \(V\) is differentiable with \(V^{\prime }(t)=iG(t)V(t)\) for every \(t\in \mathbb {R}\), then \(V=U\). In particular, uniqueness does not assume unitarity of \(V\).
Put \(|D|=(D^\dagger D)^{1/2}\). There is a unitary \(U:\mathcal H\to \mathcal H\) such that \(D=U|D|\) and, simultaneously for all \(\psi ,\phi ,\eta \in \mathcal H\),
The second inequality holds for every factorization \(D=UP\) with \(U\) unitary and \(P\ge 0\).
Fix any unitary \(U\) satisfying \(D=U(D^\dagger D)^{1/2}\). For every finite-dimensional complex Hilbert space \(\mathcal K\), put \(E=D\otimes I_{\mathcal K}\) and \(V=U\otimes I_{\mathcal K}\). Then \(V\) is unitary, \(E=V(E^\dagger E)^{1/2}\), and
for arbitrary \(\psi ,\phi ,\eta \in \mathcal H\otimes \mathcal K\). The same local \(U\) is used for every spectator space; the vectors need not be product vectors.
Let \(\rho \) and \(\sigma \) be matrices on \(\mathcal H_S\otimes \mathbb C^{d_C}\), with \(\sigma \) positive semidefinite, and set \(\overline\sigma =(\operatorname{tr}_C\sigma )\otimes d_C^{-1}\mathbf1_C\). If the identity summand obeys the support sandwich identity
then the raw support Petz map recovers \(\rho \): \(\mathcal R_\sigma (\operatorname{tr}_C\rho )=\rho \). This is the algebraic reduction in [ HJPW04 , Theorem 3, equation (8) ] . It does not derive the support sandwich identity from equality of relative entropies.
Fix a dimension \(d\ge 1\) and a primitive \(d\)-th root of unity \(\zeta \). The cyclic shift \(X\), the clock operator \(Z\), and every Weyl operator \(W(a,b)=X^aZ^b\) are unitary.
For the positive definite finite-Weyl family, let
and define \(\operatorname{Def}_B(t)\) analogously, with the real parts of the corresponding source-\(B\) pairings. Then both defects are non-negative and continuous for \(t{\gt}0\), and
The integrand is continuous, non-negative, and integrable on \((0,\infty )\). The coefficient of the source-\(B\) defect is exactly \(t\), as prescribed by the integral formula and equality analysis of Jenčová–Ruskai, arXiv:0903.2895v4, §4.
- Matrix.weightedWeylConjugate
- Matrix.weightedWeylAverage
- Matrix.weylSourceAResolventDefect
- Matrix.weylSourceBResolventDefect
- Matrix.weylRelativeEntropyGap
- Matrix.weyl_relativeEntropy_gap_integral
- Matrix.weylSourceAResolventDefect_continuousOn
- Matrix.weylSourceBResolventDefect_continuousOn
- Matrix.weylSourceAResolventDefect_nonneg
- Matrix.weylSourceBResolventDefect_nonneg
- Matrix.weylRelativeEntropyGapIntegrand_integrableOn
- Matrix.weylRelativeEntropyGapIntegrand_continuousOn
- Matrix.weylRelativeEntropyGapIntegrand_nonneg
Under the positive-definite finite-Weyl hypotheses, suppose that \(\sum _gD(A_g\Vert B_g)-D(A\Vert B)=0\). Then \(\operatorname{Def}_B(t)=0\) for every \(t{\gt}0\), and consequently \(T_g^{-1}(B_g)=T^{-1}(B)\) for every \(t{\gt}0\) and every Weyl index \(g\). In particular, equality of relative entropy under the right partial trace implies this conclusion by Theorem 13.8.12. This is the positive-definite conclusion of the equality argument in Jenčová–Ruskai, arXiv:0903.2895v4, §4 and Appendix. It makes no assertion at \(t=0\) or for singular inputs.
Let \(\rho \) and \(\sigma \) be positive definite on \(\mathcal H_S\otimes \mathbb C^{d_C}\), let \(q=d_C^{-2}\), and put
where \(U_g=\mathbf1_S\otimes W_g\). For \(t{\gt}0\), let
Then
This is the positive-definite, fixed-\(t\) identity in Jenčová–Ruskai, arXiv:0903.2895v4, Appendix, lines 1313–1343. It does not infer zero defect from equality of relative entropies and makes no assertion about singular supports.
Under the hypotheses and notation of the preceding theorem, suppose that
Then \(T_g^{-1}(B_g)=T^{-1}(B)\) for every Weyl index \(g\). In particular this holds for the identity Weyl element \(g=(0,0)\). This is the common-resolvent conclusion in Jenčová–Ruskai, arXiv:0903.2895v4, §4, lines 652–674; its squared-defect input is in Appendix, lines 1313–1343. This fixed-\(t\), positive-definite conclusion does not assert that equality of relative entropies implies the scalar hypothesis in (157).
Under the notation of Theorem 13.8.26, set \(\Gamma _t=T^{-1}(A)\). Then, for every \(t{\gt}0\),
This is the second defect family in Jenčová–Ruskai, arXiv:0903.2895v4, §4 and Appendix.
Fix a dimension \(d\ge 1\) and a primitive \(d\)-th root of unity \(\zeta \), and let \(X\) be the cyclic shift \(|i\rangle \mapsto |i+1\rangle \) and \(Z=\operatorname{diag}(\zeta ^0,\ldots ,\zeta ^{d-1})\) the clock operator. For every matrix \(M\) on \(\mathbb {C}^d\), the uniform average of the conjugations by the \(d^2\) Weyl operators \(W(a,b)=X^aZ^b\) is the completely depolarizing channel: